Showing posts with label EIA. Show all posts
Friday, June 6, 2014
Tech Talk - what the EPA Plan neglects
One of the problems, I suspect, with predictions of future energy use and production is that physical reality can become entangled in the politics of the day. Thus news that tends to negate the optimistic views of future American oil and natural gas production is subsumed by the need to keep the level of those predictions hecause of other political needs.
President Obama has now announced his decisions on a new incentive to combat his perception of the future as it sits threatened by the increased carbon dioxide produced by the burning of fossil fuels, particularly coal. As announced by the EPA, the Clean Power Plan “will maintain an affordable, reliable energy system, while cutting pollution and protecting our health and environment.”
The proposed rule has the intent of lowering carbon dioxide emissions by 30% from the levels of 2005, by 2030. As with many energy-related plans this one will take some time to implement, particularly since individual states have some input to the final program that will be put in place. More to the point, it will influence the thinking of power generators and legislators over the next few years.
Beyond the actual implementation, the real impact will be in the planning departments of the utility companies around the country. There is at least an even chance that, at some time in the future, these will become the regulations that must be followed, and as future power plant construction is planned, so the options that will be considered will now be changed to accommodate these likely regulations.
Realistically the closure of coal-fired plants will likely be followed by the construction of more natural gas plants, since the overall electrical energy needs of the country are unlikely to fall significantly. In the short term this is unlikely to be a problem. However as one moves into the intermediate term (say more than 5 years out) the old plants will have gone, and the country will become increasingly dependent on natural gas, in the same way as Europe is at present. As the old coal plants are demolished, they, and the coal mines that supply them, cannot be resurrected within a five-year period given the amount of permitting, financing and overall planning that is now required for such construction.
Natural gas has advantages over coal, in that it can be supplied by pipeline that makes it less susceptible to weather. But by the same token it is rarely stored on site, but metered along the pipeline as demand rises and falls. As history has shown, this can lead to critical shortages when, at times of high demand, the pipeline cannot keep up with demand.
At present the likelihood of problems seems remote, wells continue to be sunk and production in increasing in fields around the country. But if one goes beyond the picture that is projected as reassurance to those concerned for energy supply in the future the numbers revealed are not that comforting.
Figure 1. The changing picture of natural gas demand (EIA)
One begins with the prediction that the US has about 100 years of natural gas supply with a total extractable volume in reserves and resources of over 2,718 Tcf. It is a reassuring number but, as with the total volumes of either oil or coal in the ground, it does not really give that much information on what will be available as demand continues to rise.
Consider that, increasingly, the volumes of natural gas that are being sought are in shales, where the well must turn and drill along the shale horizon, before being fracked to produce gas and oil within the rock.
Figure 2. Number of rigs defined by type of well (Baker Hughes via EIA and Penn Energy)
The increasing dominance of horizontal well completions brings with it a considerable increase in well costs. You can see this as the technique became of increasing importance after 2005.
Figure 3. Change in the average cost of natural gas wells (EIA )
Well construction prices have continued to rise since that time, with numbers now running up to and beyond $10 million. The rising costs makes it harder to achieve a reasonable return on that investment, particularly as there has been no great increase in the overall price of natural gas to reflect its increased popularity, in large part because of the rush to drill and produce the known reserves.
Figure 4. Recent changes in natural gas prices (EIA )
As a result the number of rigs working in the natural gas fields has fallen, to the lowest levels of the recent past.
Figure 5. Change in the natural gas rig count over the past year. (Baker Hughes )
If you can’t make a profit on the merchandise, then after a while you stop trying to produce it. Despite the optimism that leads folk to anticipate large volumes of low-priced natural gas being able to sustain us into the foreseeable future if the companies cannot make a profit, after a while they stop. Which means that prices will go up, re-opening the cycle, but on a higher step. In time this will bring natural gas prices back up to around $8.00 per tcf, which will make the industry more comfortable.
What it will not do, however, will be to favorably impact the economics of the electricity business, where doubling the cost of fuel has a quite negative effect on prices and overall economics. But concerns over the rising price to be paid has had little impact yet on political decisions on energy in Europe, and one has to presume that a similar blindness to energy price consequences will also prevail in the United States. After all there is lots of natural gas around, it just has to be perceived as remaining a cheap fuel to validate the political plans . . .right ??!!
Read more!
Wednesday, April 16, 2014
Tech Talk - Of production stability, peaks and the future
Jeffrey Brown (Westexas from TOD) is quoted extensively in Kurt Cobb’s recent piece that points out that global crude production has pretty reasonably stayed constant at between 64 and 67 mbd since 2005. (H/t Nate Hagens). While there has been a total increase in the total refined products side of the house (with the total number floating around 90 mbd) this includes a number of different sources that, within generally defined standards, are not considered crude. The four main culprits that he lists are biofuels, natural gas plant liquids (NGLs), lease condensate and refinery gains. He makes a good point.
Figure 1. Crude oil production alone over the past decade (Kurt Cobb)
I can remember that it was some years ago, when looking at the OPEC reports on production, that I suddenly realized that the projected increases in NGL production made a significant difference in the overall volumes that they were producing. (It is anticipated to average 5.95 mbd in 2014). Back in 2001 OPEC just defined the fluid as natural gas liquids, but went through significant revisions of numbers in 2002 and in March 2004 redefined the volume counted as “OPEC natural gas liquids and non-conventional oils”.
Figure 2. NGL and unconventional oil production by OPEC (OPEC MOMR )
Over the past decade volumes have almost doubled. In the United States, with the increased development of the shale gases, production has also increased.
Figure 3. Increase in production of NGL in the United States (EIA )
The price obtained for these fluids, however, falls below that of conventional gasoline. For example:
Figure 4. Relative prices of NGL fuels relative to crude and gasoline. (EIA)
The EIA is reporting a continued growth in US production:
Looking at the supply side for this year, and bearing in mind that gains must more than offset lost production if the total increase in supply OPEC are projecting an overall gain in supply of 1.34 mbd, largely to come from outside of OPEC. This is expected to come from the OECD Americas (the USA, Canada and Mexico) group, while the increased production from countries such as those of the Former Soviet Union is expected, to rise by 150 kbd or less.
There has been relatively little change in the estimates of where the increases in North American production are anticipated to come. By the end of the year US production is expected to reach 12.45 mbd by the last quarter of the year. As OPEC noted:
The total gain in production from the Gulf is currently anticipated to increase, this year alone, to perhaps 1.55 mbd, and to pass the previous record Gulf production of 1.8 mbd by 2016. In addition the Cardamom project is expected to add 50 kbd to the Olympus figure, and the start of oil production from Phase 3 of the Na Kika field is expected to add an additional 40 kbd to the 130 kbd which Na Kika is currently producing. However Gulf wells have a habit of going south a little earlier than predicted and I have borrowed the following graph from Ron Patterson which illustrates the cumulative fate of the combined Atlantis, Thunder Horse, Tahiti and Blind Faith fields.
Figure 5. Changes in production from major Gulf of Mexico fields over time (Ron Patterson )
When this is combined with Dennis Coyle’s prediction that the Eagle Ford field will peak in 2015, at 1.4 mbd, with a declining rate of production increase as one reaches that peak. Similarly the number of wells that can continue to be drilled in North Dakota in the sweeter counties of the state are limited, and beyond that there is a concern (which I have expressed before, and which others have explained much better than I) that as the estimates of production fall in the less successful regions of the state that it will become harder to raise the capital for the new wells needed to sustain and increase production.
That being said, I am beginning to suspect that this may be the year that the OPEC estimates for US production may get a bit ahead of what actually is produced. And if that is the case, then that means that the following two years will become even more interesting as the nations of the world start to realize that yes, there is a peak. Which might mean that the coal resurrection might be greater than I currently anticipate, but perhaps I will have more on that next time.
Figure 1. Crude oil production alone over the past decade (Kurt Cobb)
I can remember that it was some years ago, when looking at the OPEC reports on production, that I suddenly realized that the projected increases in NGL production made a significant difference in the overall volumes that they were producing. (It is anticipated to average 5.95 mbd in 2014). Back in 2001 OPEC just defined the fluid as natural gas liquids, but went through significant revisions of numbers in 2002 and in March 2004 redefined the volume counted as “OPEC natural gas liquids and non-conventional oils”.
Figure 2. NGL and unconventional oil production by OPEC (OPEC MOMR )
Over the past decade volumes have almost doubled. In the United States, with the increased development of the shale gases, production has also increased.
Figure 3. Increase in production of NGL in the United States (EIA )
The price obtained for these fluids, however, falls below that of conventional gasoline. For example:
Figure 4. Relative prices of NGL fuels relative to crude and gasoline. (EIA)
The EIA is reporting a continued growth in US production:
Altogether, in the Bakken, Niobrara, Permian, and Eagle Ford, oil production is expected to increase by 70,000 bbl/d in May 2014. The monthly growth rate is 3,000 bbl/d more than in April 2014 due to solid gains in Permian rig count and continuous rig productivity gains across the regions. While the DPR does not forecast weather impact, the spring thaw season has officially started in the Bakken region and may disrupt some drilling activity between now and June.These additional resources take on an increasing importance as world demand is anticipated to increase another 1.14 mbd this year, slightly up on this year’s figure. This gain in demand was largely offset by increased production from the Americas, though OPEC note that overall global suppliy decreased last month to average 90.63 mbd but is expected to reach peak demand in the fall, at 92.24 mbd.
Looking at the supply side for this year, and bearing in mind that gains must more than offset lost production if the total increase in supply OPEC are projecting an overall gain in supply of 1.34 mbd, largely to come from outside of OPEC. This is expected to come from the OECD Americas (the USA, Canada and Mexico) group, while the increased production from countries such as those of the Former Soviet Union is expected, to rise by 150 kbd or less.
There has been relatively little change in the estimates of where the increases in North American production are anticipated to come. By the end of the year US production is expected to reach 12.45 mbd by the last quarter of the year. As OPEC noted:
Based on the US Energy Information Administration (EIA)’s monthly oil production report for January, regular crude oil output registered at 4.93 mb/d, tight oil production increased to 3 mb/d, NGLs output reached 2.64 mb/d and biofuels and other non- conventional oils recorded the highest output at 1.22 mb/d. The use of energy from biomass resources in the United States grew by more than 60% over the decade between 2002 and 2013 — primarily through increased use of biofuels like ethanol and biodiesel which are produced from biomass. According to the EIA, biomass accounted for about half of all renewable energy consumed in 2013 and 5% of total US energy consumed.This month the OPEC MOMR focused on increased production from the Gulf of Mexico, with anticipated gains from the Olympus project at Mars B.
The total gain in production from the Gulf is currently anticipated to increase, this year alone, to perhaps 1.55 mbd, and to pass the previous record Gulf production of 1.8 mbd by 2016. In addition the Cardamom project is expected to add 50 kbd to the Olympus figure, and the start of oil production from Phase 3 of the Na Kika field is expected to add an additional 40 kbd to the 130 kbd which Na Kika is currently producing. However Gulf wells have a habit of going south a little earlier than predicted and I have borrowed the following graph from Ron Patterson which illustrates the cumulative fate of the combined Atlantis, Thunder Horse, Tahiti and Blind Faith fields.
Figure 5. Changes in production from major Gulf of Mexico fields over time (Ron Patterson )
When this is combined with Dennis Coyle’s prediction that the Eagle Ford field will peak in 2015, at 1.4 mbd, with a declining rate of production increase as one reaches that peak. Similarly the number of wells that can continue to be drilled in North Dakota in the sweeter counties of the state are limited, and beyond that there is a concern (which I have expressed before, and which others have explained much better than I) that as the estimates of production fall in the less successful regions of the state that it will become harder to raise the capital for the new wells needed to sustain and increase production.
That being said, I am beginning to suspect that this may be the year that the OPEC estimates for US production may get a bit ahead of what actually is produced. And if that is the case, then that means that the following two years will become even more interesting as the nations of the world start to realize that yes, there is a peak. Which might mean that the coal resurrection might be greater than I currently anticipate, but perhaps I will have more on that next time.
Read more!
Labels:
coal production,
crude oil production,
Economist,
EIA,
GOM,
NGL,
North Dakota,
OPEC MOMR,
Thunder Horse,
Westexas
Sunday, December 22, 2013
Tech Talk - The ExxonMobil 2014 Outlook for Energy
Each year the large oil companies produce their forecasts for future demand and supply of fuel, and these can be compared – both with earlier forecasts and with each other and the forecasts from different agencies. Last week, for example, I looked at the IEA forecast through 2035, while today’s subject is the ExxonMobil (EM) 2014 Outlook for Energy. (See also the 2013 Outlook Review and the 2011 Outlook Review).
In conformity with the IEA review EM consider that the energy growth rate for India will be perhaps one of the more significant metrics of the future. EM note that by 2040 one third of the global population will live in either India or China and between them they amount for half the global increase in energy demand, which is anticipated to be about 35% higher than the 2010 figure. India has already become the third largest energy consumer (after China and the United States).
One of the greatest drivers to energy demand growth comes as the population moves from the farms to the city and, as EM note, China has seen the urban population grow from 25 to 50% of the total in the past 20 years increasing residential power demand 20-fold. But that growth will slow in the future, reaching 75% by 2040. India (and Africa) are however further behind this curve with India being at 30% and Africa at 40%. Thus, as they still have further to move up the ladder, EM anticipate there will be concomitant increases in demand as these changes occur.
Figure 1. Projected growth in energy demand for major groups until 2040. (Illustrations are taken from EM The Outlook for Energy:A View to 2040 except where stated) (The key growth countries are Brazil, Indonesia, Saudi Arabia, Iran, South Africa, Nigeria, Thailand, Egypt Mexico and Turkey).
One of the small niggles with this projection is that it assumes a virtually limitless source of fuel.
This is noteworthy because, as yet there is not much gap in the world between the quantities of fuels desired, and those available. Yet China is moving aggressively to ensure that it will be able to get what it needs when this changes. Such is not the case either with India, which has often failed in head-to-head bids for energy supplies when going against China, or much of the rest of the world who continue to accept the assurances that EM inter alia are promulgating with reports such as this, that there is a plentiful sufficiency.
Continuing along this unrestricted “ideal world” trail that EM are laying out, they continue to foresee that there will be a substantial improvement in energy efficiency over the next decades, leading to an increased decoupling of the relationship between GDP growth and Energy demand.
Figure 2. Projected growth in GDP and Energy demand through 2040.
Some of this EM project will come from the increased efficiency of automobiles and the greater acceptance of hybrid vehicles, with a penetration of 35% of the market – up from the 1% it held in 2010. While they do not expect that natural gas will have much impact on personal vehicles they do expect some impact with commercial transportation. The changes will lift the light vehicle mileage from the 24 mpg of 2010 to 46 mpg by 2040. (This is 1 mpg lower than their projection for mileage change given last year).
Figure 3. Changes in the composition and size of the global car fleet.
In terms of electricity supply EM foresee a sharply changing picture of the composition of the fuel sources for global supply, with coal barely holding its own throughout the period, and oil declining, while the remaining sources all grow in market size.
Figure 4. Sources of fuel and market size for electric power generation through 2040.
So where will the oil supply come from? Well EM remain confident in the future growth of North American oil.
Figure 5. EIA projections for US petroleum production through 2040 (EIA).
Ron, has refined this plot and shows that US production may well peak in either 2015 or 2016, and go into significant decline by 2020. This is quite a contrast to the EM projection.
Figure 6. EM projection for change in liquids production through 2040
EM expect that Deepwater production will increase with major supplies coming from Angola, Nigeria, the Gulf of Mexico and Brazil, with production rising to a peak in around 2040. They expect tight oil supplies, however, to increase by a factor of tenfold from 2010 to 2040. The major new player in that field is anticipated to be Russia whose output is still expected to trail that in North America (which includes Canada and Mexico).
One of the great questions of the next decade relates to the development of the heavy oils of Venezuela and Canada. EM expects that the Canadian production will increase 200% with the rest of the total gain of 300% of the 2010 total presumably coming from Venezuela. However Venezuelan development remains a complex situation.
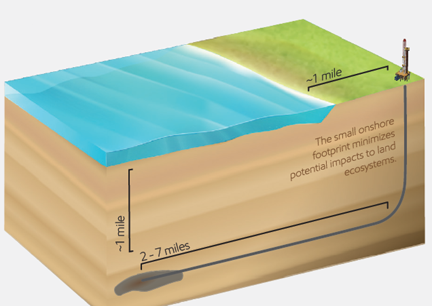
One of the most promising developments that EM describe is the use of extended reach horizontal wells, that are now allowing sub-sea deposits to be tapped using land-based rigs. At Sakhalin Island, for example, they note that they were able to drill one well in the Chayvo field that extended out 7 miles.
Figure 7. Illustration by EM of their extended reach well capabilities.
The other source that EM cite for increased production comes from OPEC and production gains in the Middle East. Given that Saudi Arabia have stated that 10 mbd is their intended upper limit to production (give or take a little) one presumes that the roughly 9 mbd gain is largely anticipated to come from Iraq. EM don’t actually say, nor did they last year, but it is interesting to end by comparing last year’s projection for future growth with the one shown in Figure 6.
Figure 8. The projected volumes for liquid supply growth as provided by ExxonMobil last year in their 2013 report.
On which cheerful note I wish you all the Compliments of the Season, and hopes that you have a safe and happy break.
In conformity with the IEA review EM consider that the energy growth rate for India will be perhaps one of the more significant metrics of the future. EM note that by 2040 one third of the global population will live in either India or China and between them they amount for half the global increase in energy demand, which is anticipated to be about 35% higher than the 2010 figure. India has already become the third largest energy consumer (after China and the United States).
One of the greatest drivers to energy demand growth comes as the population moves from the farms to the city and, as EM note, China has seen the urban population grow from 25 to 50% of the total in the past 20 years increasing residential power demand 20-fold. But that growth will slow in the future, reaching 75% by 2040. India (and Africa) are however further behind this curve with India being at 30% and Africa at 40%. Thus, as they still have further to move up the ladder, EM anticipate there will be concomitant increases in demand as these changes occur.
Figure 1. Projected growth in energy demand for major groups until 2040. (Illustrations are taken from EM The Outlook for Energy:A View to 2040 except where stated) (The key growth countries are Brazil, Indonesia, Saudi Arabia, Iran, South Africa, Nigeria, Thailand, Egypt Mexico and Turkey).
One of the small niggles with this projection is that it assumes a virtually limitless source of fuel.
Ongoing advances in exploration and production technology continue to expand the size of the world’s recoverable crude and condensate resources. Despite rising liquids production, we estimate that by 2040, about 65 percent of the world’s recoverable crude and condensate resource base will have yet to be produced.While that projection will be discussed a little further later, it should be noted that in the next decade China’s energy demand will continue to grow at roughly current rates and that they have been quite assiduous in finding new sources to provide that energy. This is already providing some of the backstory to the growing tensions between China and its neighbors in the South and East China seas.
This is noteworthy because, as yet there is not much gap in the world between the quantities of fuels desired, and those available. Yet China is moving aggressively to ensure that it will be able to get what it needs when this changes. Such is not the case either with India, which has often failed in head-to-head bids for energy supplies when going against China, or much of the rest of the world who continue to accept the assurances that EM inter alia are promulgating with reports such as this, that there is a plentiful sufficiency.
Continuing along this unrestricted “ideal world” trail that EM are laying out, they continue to foresee that there will be a substantial improvement in energy efficiency over the next decades, leading to an increased decoupling of the relationship between GDP growth and Energy demand.
Figure 2. Projected growth in GDP and Energy demand through 2040.
Some of this EM project will come from the increased efficiency of automobiles and the greater acceptance of hybrid vehicles, with a penetration of 35% of the market – up from the 1% it held in 2010. While they do not expect that natural gas will have much impact on personal vehicles they do expect some impact with commercial transportation. The changes will lift the light vehicle mileage from the 24 mpg of 2010 to 46 mpg by 2040. (This is 1 mpg lower than their projection for mileage change given last year).
Figure 3. Changes in the composition and size of the global car fleet.
In terms of electricity supply EM foresee a sharply changing picture of the composition of the fuel sources for global supply, with coal barely holding its own throughout the period, and oil declining, while the remaining sources all grow in market size.
Figure 4. Sources of fuel and market size for electric power generation through 2040.
So where will the oil supply come from? Well EM remain confident in the future growth of North American oil.
North American liquids production is expected to rise by more than 40 percent from 2010 to 2040, boosted by gains in oil sands, tight oil and NGLs. With production rising and demand falling, North America is expected to shift from a significant crude oil importer to a fairly balanced position by 2030.The concern with these projections (which are substantially more optimistic than the IEA forecast, lies in their assumption of unfettered growth. As Ron Patterson just noted the EIA is anticipating that US volumes will peak in 2019, and then decline.
Latin American liquids production will nearly double through 2040 with the development of the Venezuelan oil sands, Brazilian deepwater and biofuels.
The Middle East is expected to have the largest absolute growth in liquids production over the Outlook period — an increase of more than 35 percent. This increase will be due to conventional oil developments in Iraq, as well as growth in NGLs and rising production of tight oil toward the latter half of the Outlook period.
Figure 5. EIA projections for US petroleum production through 2040 (EIA).
Ron, has refined this plot and shows that US production may well peak in either 2015 or 2016, and go into significant decline by 2020. This is quite a contrast to the EM projection.
Figure 6. EM projection for change in liquids production through 2040
EM expect that Deepwater production will increase with major supplies coming from Angola, Nigeria, the Gulf of Mexico and Brazil, with production rising to a peak in around 2040. They expect tight oil supplies, however, to increase by a factor of tenfold from 2010 to 2040. The major new player in that field is anticipated to be Russia whose output is still expected to trail that in North America (which includes Canada and Mexico).
One of the great questions of the next decade relates to the development of the heavy oils of Venezuela and Canada. EM expects that the Canadian production will increase 200% with the rest of the total gain of 300% of the 2010 total presumably coming from Venezuela. However Venezuelan development remains a complex situation.
One of the most promising developments that EM describe is the use of extended reach horizontal wells, that are now allowing sub-sea deposits to be tapped using land-based rigs. At Sakhalin Island, for example, they note that they were able to drill one well in the Chayvo field that extended out 7 miles.
Figure 7. Illustration by EM of their extended reach well capabilities.
The other source that EM cite for increased production comes from OPEC and production gains in the Middle East. Given that Saudi Arabia have stated that 10 mbd is their intended upper limit to production (give or take a little) one presumes that the roughly 9 mbd gain is largely anticipated to come from Iraq. EM don’t actually say, nor did they last year, but it is interesting to end by comparing last year’s projection for future growth with the one shown in Figure 6.
Figure 8. The projected volumes for liquid supply growth as provided by ExxonMobil last year in their 2013 report.
On which cheerful note I wish you all the Compliments of the Season, and hopes that you have a safe and happy break.
Read more!
Labels:
China,
EIA,
Energy future,
ExxonMobil,
hybrids,
IEA,
India,
Iraq,
World oil production
Wednesday, May 29, 2013
OGPSS - Future oil production from Iraq - an optimistic view
There is often quite a debate in the Peak Oil community over the difference between a reserve and a resource. Simplistically a resource is the amount of, for the sake of discussion, oil that is in the ground in a certain country, while the reserve is the amount of oil that can be both technically and economically recovered from that resource. The numbers can differ quite markedly, and the judgment as to whether a certain body is a reserve is finally made when a well is drilled down, and production (or not) begins.
Just having the reserve available is not, however, within the global discussion of Peak Oil, an adequate sufficiency. Because oil well flow declines over time it is important that the rate of oil production from that reservoir, and the timeliness of its arrival within the supply chain be considered. This is particularly true in discussions over the help that the reserve will provide in ensuring that there is an adequate supply available when the global demand needs it. Normally, as noted, the decisions on production are made on geologic and economic grounds, but it would be foolish not to recognize that there are other factors. Consider the case of Iraq. It is common to find the assumption that Iraqi oil production will rise considerably, with some suggesting it will reach the levels currently only achieved by Russia and Saudi Arabia, although there are some who project it might even rise to as much as 13 mbd, given that there are contracts in place, which if all were fulfilled on time, would raise Iraqi production four-fold to 12 mbd by 2017.
In their Special Report on Iraq last year the IEA noted that the country is already the world’s third-largest oil exporter, with the potential and intent to increase production much further. And, as the EIA notes, Iraq became the second largest oil producer in OPEC, when it passed Iran at the end of last year.

Figure 1. Iraqi production of oil since 1990. (EIA)
Iraq is currently producing around 3.1 mbd of crude and thus the potential production levels, and their contribution to reserves and to the daily global need for supply, still has a way to go. With so much oil potentially available, and yet with considerable question over the rate at which it will arrive, it is worth examining the conclusions that the IEA came to, before the current increase in violence occurred. This new spate of attacks come after an interval when violence was decreasing in the country, and may prove a further impediment to significant growth in production.

Figure 2. Level of violence in Iraq showing the number of attacks each week since 2007. (IEA )
The IEA built three different scenarios in their report, for which their was extensive consultation in country. The main or Central Scenario that they project anticipates that GDP in the country will continue to rise, though tapering off as stability are achieved in the out years.

Figure 3. Anticipated growth rates for Iraqi GDP under the different models the IEA used. (IEA )
The Iraqi GDP grew 10.2% last year, and has been growing at an increasing rate over the past few years.

Figure 4. Actual annual growth rate in Iraq GDP (Trading Economics )
The oil fields in the country are largely concentrated in two separate regions, down around Basra in the south of the country, and in the region around Kirkuk and Mosul in the North.

Figure 5. Oil and gas fields in Iraq (IEA ).
This division is somewhat unfortunate from a politically stable point of view since the region in the south is predominantly Shiite, while the reserves in the north lie in the Kurdish region of the country. There is significantly less within the Sunni communities which are largely found in the central region of the country.
In recent times Euan Mearns has written of the potential for oil production in the Kurdish region in the north. In total this is estimated to hold around 4 billion barrels of oil, or around 17% of the national reserve. However, as exploration of the potential fields in Kurdistan continues, this estimate has been increased by the local government to a possible 45 billion barrels. Euan, for example, wrote about the development of the Shaikan oil field and the potential size of between 8 and 13.4 billion barrels that it showed in January 2012. Current plans are for production to reach 40,000 bpd “soon”, with production ramping up to 400,000 bpd. The Kurdistan Regional Government (KRG) see it playing a considerable role in achieving their target of 400 kbd this year, 1 mbd by 2015, and 2 mbd by 2019. The field is being developed by Gulf Keystone Petroleum.
In the south current production is centered around the Rumaila oil fields. BP has committed $2.85 billion toward improvements in Rumaila this year, with the intent of raising production from the current 1.4 mbd, through 1.45 mbd at the end of this year, up to 6 mbd by 2017. 300 new wells will be drilled in the field over the next five years, to meet the goal, with 150 of these being drilled in the second half of this year. BP operates the field in partnership with CNPC.

Figure 6. Detail showing the location of the Rumaila fields in south Iraq. (Energy-pedia)
The overall scale of Chinese involvement is of concern to some, since as oil supplies tighten in the years to come, it is expected that up to 80% of future Iraqi production will head towards Asia, and particularly to China.
With the growing development of the Majnoon field, with an estimated reserve of 38 billion barrels, it might thus appear that the country is well on its way to meeting the projections that the contracts might suggest. However there are many constraints on future production, including infrastructure and water availability, and I will discuss these and why they limit the IEA to an optimistic assessment that the country will produce 6 mbd by 2020, and only reach 8.3 mbd by 2035 in the next post.
Read more!
Thursday, May 16, 2013
OGPSS - The weather, corn, ethanol and oil production
News of the future was, in my youth, something that one found by crossing the palm of a lady in a dark tent with a piece or two of silver (or the modern equivalent) at one of the fairs that came to town. Such opportunities still exist, with all the caveats that existed back then likely still being in force. However projecting the future, whether of the weather, the likely corn crop this year in the United States, or the production of crude oil by the nations of the world has become a much bigger business with copious tables, graphs and theories replacing the rather worn pack of cards or crystal ball of my youthful experience.
Our part of the world underwent a drought last year severe enough to kill several trees in our yard, for example, as well as hurting the corn crop. This year, corn plantings have been severely impacted by the heavy rains and cold weather, so that decisions on crop plantings have become more complicated and delayed, with follow-on impacts on the ultimate yield in a number of Mid-Western states. Corn yield apparently falls at an average rate of 2.3 bushels per acre per day of delay in Northern Wisconsin. These changing conditions make it difficult to assess how much ethanol, for example, will be available to meet demand, although the latest EIA TWIP holds out some optimism for this year.
The impact of the drought on corn prices, and the consequent fall in ethanol production, as production costs rose, are directly visible from their plot of the two over the last year.

Figure 1. A comparison of corn prices and ethanol production in the USA (EIA TWIP )
However, with the weather impacts still being assessed it is already being concluded that the US corn crop is unlikely to reach the record level of close to 14.6 billion bushels that were earlier projected. It still, however, has the potential to reach around 12.3 billion bushels, which would satisfy the just under 5 billion bushel need for ethanol, as well as other demands of the market. By May 12th only 28% of this year's expected crop had been planted, in contrast with a normal year where 65% would be in the ground. Thus even the relatively short-term projections of the EIA could yet be in trouble for this year.
Moving to the slightly longer-term the nations that form OPEC must try and estimate global demand for their products, and the amount that other non-OPEC nations will produce, so that they can balance supply and demand at such a level that will sustain prices at a level they are comfortable with. Their estimates come out as Monthly Oil Market Reports and in the latest (May) version they continue to expect global demand to increase by 0.8 mbd over 2013, but are beginning to hedge that bet, as the global economy continues to appear anemic, with Russian and Asian economies slowing. Yet by the fourth quarter of the year they anticipate that global demand will reach 90.9 mbd.
Figure 2. Global oil demand by region (OPEC MOMR)
OPEC anticipates that, with the major increase coming from the Americas, that non-OPEC oil production will increase by just under 1 mbd to reach an a level of 54.41 mbd in the fourth quarter of the year. The majority of that growth (some 0.59 mbd) will come from the United States, with the Permian, Bakken and Eagle Ford being cited as the anticipated source of these gains. OPEC, having looked at current rig counts, project that these numbers may be revised upwards over the course of the year. And yet it is worth noting this:

Figure 3. OPEC member production as reported by secondary sources (OPEC MOMR)

Figure 4. OPEC member production as reported directly (OPEC MOMR)
It would appear, with Manifa coming on line, that Saudi Arabia is increasing production again, while Venezuela and Iran would have you believe they are producing more than they are, and Iraq, which is now producing above 3 mbd, is directly reporting less (though that could be because some of that production is coming from the north, and there are some communication problems between there and Baghdad).
As long as OPEC has available reserves it can continue this balance to keep enough oil available at an acceptable price to allow the world economy to continue at its present pace. And with that ongoing adjustment available, their projections for this year of a relatively stable price would seem fairly founded, absent some major change in one of the larger producing states.
Iraq overtook Iran as the second largest producer in OPEC last year (according to secondary sources) and expects that with production from Majnoon, it will increase production capability by upwards of 200 kbd by the end of the year. Ultimately the goal is to achieve a target production of 1.8 mbd. However, as overall production levels increase, Iraq may join with the Kingdom in controlling production to maintain price.
Yet even with those abilities OPEC is becoming cautious over predicting that their estimate of the demand:supply balance numbers for this year will be accurate over that time interval.
With these uncertainties in even short-term projections of future production whether it be corn, ethanol or crude it is perhaps wise to continue a somewhat cynical view of projections over a longer time period. Although the bounding bar of a decline in existing field production continues to exist and will continue to require an offset in increased production from new wells to offset. Perhaps that lady in the tent of my youth may prove as prescient as some of the more optimistic forecasts that we continue to see.
Our part of the world underwent a drought last year severe enough to kill several trees in our yard, for example, as well as hurting the corn crop. This year, corn plantings have been severely impacted by the heavy rains and cold weather, so that decisions on crop plantings have become more complicated and delayed, with follow-on impacts on the ultimate yield in a number of Mid-Western states. Corn yield apparently falls at an average rate of 2.3 bushels per acre per day of delay in Northern Wisconsin. These changing conditions make it difficult to assess how much ethanol, for example, will be available to meet demand, although the latest EIA TWIP holds out some optimism for this year.
The impact of the drought on corn prices, and the consequent fall in ethanol production, as production costs rose, are directly visible from their plot of the two over the last year.

Figure 1. A comparison of corn prices and ethanol production in the USA (EIA TWIP )
However, with the weather impacts still being assessed it is already being concluded that the US corn crop is unlikely to reach the record level of close to 14.6 billion bushels that were earlier projected. It still, however, has the potential to reach around 12.3 billion bushels, which would satisfy the just under 5 billion bushel need for ethanol, as well as other demands of the market. By May 12th only 28% of this year's expected crop had been planted, in contrast with a normal year where 65% would be in the ground. Thus even the relatively short-term projections of the EIA could yet be in trouble for this year.
Moving to the slightly longer-term the nations that form OPEC must try and estimate global demand for their products, and the amount that other non-OPEC nations will produce, so that they can balance supply and demand at such a level that will sustain prices at a level they are comfortable with. Their estimates come out as Monthly Oil Market Reports and in the latest (May) version they continue to expect global demand to increase by 0.8 mbd over 2013, but are beginning to hedge that bet, as the global economy continues to appear anemic, with Russian and Asian economies slowing. Yet by the fourth quarter of the year they anticipate that global demand will reach 90.9 mbd.
Figure 2. Global oil demand by region (OPEC MOMR)
OPEC anticipates that, with the major increase coming from the Americas, that non-OPEC oil production will increase by just under 1 mbd to reach an a level of 54.41 mbd in the fourth quarter of the year. The majority of that growth (some 0.59 mbd) will come from the United States, with the Permian, Bakken and Eagle Ford being cited as the anticipated source of these gains. OPEC, having looked at current rig counts, project that these numbers may be revised upwards over the course of the year. And yet it is worth noting this:
On a quarterly basis, US oil supply is seen to average 10.62 mb/d, 10.67 mb/d, 10.62 mb/d and 10.61 mb/d respectively.The sustained gain in North American production comes about because:
On a quarterly basis, Canada’s production is anticipated to average 4.02mb/d, 3.97 mb/d, 4.02 mb/d and 4.12 mb/d respectively.Russia is expected to continue to lead in oil production over the course of the year, although it is not longer expected to increase production above current levels.
On a quarterly basis, Russian oil supply is seen to average 10.45 mb/d, 10.43 mb/d, 10.43 mb/d and 10.43 mb/d respectively.And this brings us back around to OPEC as they try and balance their production against the gap between global demand and non-OPEC supply. As has been the case for a while, OPEC produced two separate tables showing production, as reported by secondary sources, as well as those directly reported by the countries themselves.

Figure 3. OPEC member production as reported by secondary sources (OPEC MOMR)

Figure 4. OPEC member production as reported directly (OPEC MOMR)
It would appear, with Manifa coming on line, that Saudi Arabia is increasing production again, while Venezuela and Iran would have you believe they are producing more than they are, and Iraq, which is now producing above 3 mbd, is directly reporting less (though that could be because some of that production is coming from the north, and there are some communication problems between there and Baghdad).
As long as OPEC has available reserves it can continue this balance to keep enough oil available at an acceptable price to allow the world economy to continue at its present pace. And with that ongoing adjustment available, their projections for this year of a relatively stable price would seem fairly founded, absent some major change in one of the larger producing states.
Iraq overtook Iran as the second largest producer in OPEC last year (according to secondary sources) and expects that with production from Majnoon, it will increase production capability by upwards of 200 kbd by the end of the year. Ultimately the goal is to achieve a target production of 1.8 mbd. However, as overall production levels increase, Iraq may join with the Kingdom in controlling production to maintain price.
Yet even with those abilities OPEC is becoming cautious over predicting that their estimate of the demand:supply balance numbers for this year will be accurate over that time interval.
With these uncertainties in even short-term projections of future production whether it be corn, ethanol or crude it is perhaps wise to continue a somewhat cynical view of projections over a longer time period. Although the bounding bar of a decline in existing field production continues to exist and will continue to require an offset in increased production from new wells to offset. Perhaps that lady in the tent of my youth may prove as prescient as some of the more optimistic forecasts that we continue to see.
Read more!
Labels:
corn ethanol,
corn planting,
EIA,
Iran,
Iraq,
Manjoon,
MOMR,
TWIP,
weather
Thursday, January 31, 2013
OGPSS - Coal power and air pollution
Fifty years ago I began my undergraduate studies at the University of Leeds in the UK. It is not something I particularly dwell on, but the stories out of Beijing this week, describing the air pollution in the Chinese capital, brought back a memory. The story on CNN notes that visibility in Beijing has been cut to under 200 yards. Back in Leeds in December of 1962 the air quality had registered the highest levels of sulfur dioxide in the air that had ever been recorded, as air conditions generated smogs that covered large parts of the country. What made it personal for me was that I lived about a mile from the University and had to walk there through the smog that covered the city. Despite it being daylight there came a point where I could not see (and I still remember doing this) my hand when held at the full stretch of my arm. Crossing the Park to the University there were cries in the mist, as folk fell over some of the, now invisible, decorative iron edging along the walkways. From that time on the air quality regulations took increasing effect, and before long the black buildings that I had walked past on my way through town were being cleaned and brought back to their original white condition, which they have retained in the years since.
Immediately after the Second World War Britain needed the coal to power the reconstruction of the country, but in the time that I was in college it was already clear that the days of unrestricted mining were over, and the transition to other fuels had already begun. It was not, however, the air pollution in Leeds that was the driving force for the regulations, but more likely the presence of similar smogs in London and the South, where those who governed the country lived. The major legislation began after the Great Smog of 1952. In a four-day period at the beginning of December the combination of a fog, an inversion in the immediate atmosphere, and the increased use of coal fires to provide additional warmth generated a smog that is blamed for the immediate death of around 4,000 people and a strong influence on the consequent death of some 8,000 others.
I bring this up because the air pollution in both Beijing, and in New Delhi is reaching levels where the government is beginning to move to help abate the immediate problem. In both capitals it is a combination of vehicle exhaust and power generation that is generating the problem, whereas back in the UK, fifty and sixty years ago, vehicular exhaust was not nearly as much of a problem as burning coal. Yet, I suspect that those problems in Asia are not yet at the levels that they reached in the UK, they may be less tractable of solution.
Burning coal to generate power remains a relatively simple process, as does mining of the coal, for which a realistic estimate would suggest that there remains, for now, a plentiful sufficiency. (That latter point is, however, disputed by some). The EIA has recently pointed out, that we are at a point where China is about to consume about half of the global supply of coal each year.
Figure 1. Chinese coal consumption relative to that of the rest of the world. (EIA)
At the rate of increase reported, it is likely that the two lines will cross before the end of this year. However it should also be noted that India has been importing more thermal coal than China (a projected 118 million tons for 2012, in contrast with the 102 million tons imported by China). And as Mongolian coal becomes more available, so India may take over parts of the international supply that now flows to China from Australia, Indonesia and Africa.
The need for increasing levels of power to sustain the growth rates of India and China are most often discussed in terms of the oil and natural gas that these two countries are consuming, but it has been estimated that India has a shortage of around 10% between the level of demand and actual supply, leading to crippling blackouts, such as that of last July.
It should be noted that the levels of air pollution from power generation can be controlled. The United States uses most of the roughly billion tons of coal a year that it produces for power consumption, but air quality has been successively cleaned to higher standards over the decades, so that smogs are now only a historic curiosity.
Figure 2. Coal consumption in the United States by end use. (EIA )
The efforts of the EPA, among others, have had a considerable impact on American Air Quality. This, for example, is the median air quality index for the District of Columbia over the past 30 years. (I am not sure where to get earlier data).
Figure 3. Median Air Quality Index for Washington D.C. (EPA )
It is thus, demonstrably possible for China and India to clean up their air, even as they increase their demand for coal. It should also be noted that over those past 30 years the miles that Americans drive has also increased, as I recently commented, and so, based on the above, the argument applies also to vehicular exhaust.
It is true that part of the imposed solution to date, in terms of the American coal used, has transferred demand to the lower sulfur coals of Wyoming, rather than the higher calorific value, but also higher sulfur contents of more Eastern states, but as regulations have changed the power plant requirements, so some of that earlier loss to Wyoming is being recovered.
Figure 4. The top coal shipping and receiving states in the third quarter of 2012 (EIA )
Based on American experience it is thus demonstrable that both China and India could clean up their air to American standards, while still generating the power that they need through burning coal. Unfortunately, however, as the experience with mine accidents in China has shown, there are still too many operations too far from Beijing for central regulation to be, as yet, fully enforced and complied with.
Addendum The Air Quality Index should be described. As the EPA Airnow site explains:
Figure 5. The gradation of the Air Quality Index. (EPA)
Immediately after the Second World War Britain needed the coal to power the reconstruction of the country, but in the time that I was in college it was already clear that the days of unrestricted mining were over, and the transition to other fuels had already begun. It was not, however, the air pollution in Leeds that was the driving force for the regulations, but more likely the presence of similar smogs in London and the South, where those who governed the country lived. The major legislation began after the Great Smog of 1952. In a four-day period at the beginning of December the combination of a fog, an inversion in the immediate atmosphere, and the increased use of coal fires to provide additional warmth generated a smog that is blamed for the immediate death of around 4,000 people and a strong influence on the consequent death of some 8,000 others.
I bring this up because the air pollution in both Beijing, and in New Delhi is reaching levels where the government is beginning to move to help abate the immediate problem. In both capitals it is a combination of vehicle exhaust and power generation that is generating the problem, whereas back in the UK, fifty and sixty years ago, vehicular exhaust was not nearly as much of a problem as burning coal. Yet, I suspect that those problems in Asia are not yet at the levels that they reached in the UK, they may be less tractable of solution.
Burning coal to generate power remains a relatively simple process, as does mining of the coal, for which a realistic estimate would suggest that there remains, for now, a plentiful sufficiency. (That latter point is, however, disputed by some). The EIA has recently pointed out, that we are at a point where China is about to consume about half of the global supply of coal each year.
Figure 1. Chinese coal consumption relative to that of the rest of the world. (EIA)
At the rate of increase reported, it is likely that the two lines will cross before the end of this year. However it should also be noted that India has been importing more thermal coal than China (a projected 118 million tons for 2012, in contrast with the 102 million tons imported by China). And as Mongolian coal becomes more available, so India may take over parts of the international supply that now flows to China from Australia, Indonesia and Africa.
The need for increasing levels of power to sustain the growth rates of India and China are most often discussed in terms of the oil and natural gas that these two countries are consuming, but it has been estimated that India has a shortage of around 10% between the level of demand and actual supply, leading to crippling blackouts, such as that of last July.
It should be noted that the levels of air pollution from power generation can be controlled. The United States uses most of the roughly billion tons of coal a year that it produces for power consumption, but air quality has been successively cleaned to higher standards over the decades, so that smogs are now only a historic curiosity.
Figure 2. Coal consumption in the United States by end use. (EIA )
The efforts of the EPA, among others, have had a considerable impact on American Air Quality. This, for example, is the median air quality index for the District of Columbia over the past 30 years. (I am not sure where to get earlier data).
Figure 3. Median Air Quality Index for Washington D.C. (EPA )
It is thus, demonstrably possible for China and India to clean up their air, even as they increase their demand for coal. It should also be noted that over those past 30 years the miles that Americans drive has also increased, as I recently commented, and so, based on the above, the argument applies also to vehicular exhaust.
It is true that part of the imposed solution to date, in terms of the American coal used, has transferred demand to the lower sulfur coals of Wyoming, rather than the higher calorific value, but also higher sulfur contents of more Eastern states, but as regulations have changed the power plant requirements, so some of that earlier loss to Wyoming is being recovered.
Figure 4. The top coal shipping and receiving states in the third quarter of 2012 (EIA )
Based on American experience it is thus demonstrable that both China and India could clean up their air to American standards, while still generating the power that they need through burning coal. Unfortunately, however, as the experience with mine accidents in China has shown, there are still too many operations too far from Beijing for central regulation to be, as yet, fully enforced and complied with.
Addendum The Air Quality Index should be described. As the EPA Airnow site explains:
EPA calculates the AQI for five major air pollutants regulated by the Clean Air Act: ground-level ozone, particle pollution (also known as particulate matter), carbon monoxide, sulfur dioxide, and nitrogen dioxide. For each of these pollutants, EPA has established national air quality standards to protect public health .Ground-level ozone and airborne particles are the two pollutants that pose the greatest threat to human health in this country.
Figure 5. The gradation of the Air Quality Index. (EPA)
Read more!
Labels:
Air Quality Index,
Beijing,
China,
coal demand,
EIA,
EPA,
India,
New Dehli,
power generation,
vehicular traffic,
Washington DC
Tuesday, December 11, 2012
OGPSS - Iran and the new EIA and OPEC Reports
With the possibility that demand for Iranian oil may fall below 1 million barrels a day (mbd) as sanctions continue to bite, Iran has announced that it wants OPEC to cut back production to the agreed quotas, rather than the overall additional 1 mbd that is actually being produced, and sold. Such a move would, of course, ,make it more difficult for those customers who have found a way of replacing Iranian oil, and perhaps incline them more towards disregarding the embargo.
OPEC has just released their December Monthly Oil Market Report (MOMR) in which they anticipate that earlier projections for 2013 oil demand growth will still be valid, at 0.8 mbd. (Though they note that December 2012 growth y-o-y was at 1.0 mbd as the US economy continued to improve). They expect that all of this increase will be met by non-OPEC increases in supply, and that demand for OPEC oil may even drop 0.4 mbd. Part of that projection continues to rely on increased US crude production, and the EIA TWIP of December 5th had the latest chart showing that projected growth, based on the newly released Annual Energy Outlook 2013.
Figure 1. Projections of future growth in US crude oil production. (EIA TWIP) from Annual Energy Outlook 2013)
As a footnote to that graph the Alyeska pipeline pumped an average of 582,755 bd in November, which brings the annual average up to 544, 625 bd. It is clear from looking at that plot that the gains in production are all assumed to come from increased production from the "tight" oil deposits that have produced the overall gains achieved to date. The optimism of this projection goes a little beyond the levels that I anticipate being achieved.
Coming back to the MOMR their projections do not include the recent news that Venezuelan President Chavez has had to have a fourth operation for cancer, and has named a successor, although the operation was apparently successful. This may complicate the decisions on how much to allocate among the OPEC partners, especially since all continue to need higher priced oil.
OPEC also give the price of various commodities in their report, and before going on to discuss country production, those prices are informative. (And can be read more easily by clicking on the table to get a better image). At present, with the decline in overall global demand, metal prices in particular seem to be continuing to slide.
Figure 2. OPEC report of commodity prices for November (OPEC December MOMR) Equally informative is the demand that OPEC anticipates from the various regions of the world for oil in 2013.
Figure 3. OPEC estimates for regional oil demand in 2013. (OPEC December MOMR) In total OPEC anticipates that global demand will reach 90.83 mbd by the fourth quarter of 2013, with the greatest growth continuing to be from China and the other Asian nations. Looking at where this oil might come from, the main increase is still anticipated to come from North America. Figure 4. Non-OPEC supply projections for 2013 (OPEC December MOMR) The conflict in Syria is now reported to have led government forces to withdraw from the Omar and Al-Ward fields in the Deir Ezzor region, where much of Syria’s exports were produced. However the rebels do not, as yet control any of the refineries or export terminals and the result is that oil production is estimated to have fallen from 380 kbd to 160 kbd over the past few months. The regime is making up the shortfall in its needs by importing from Iraq. Which brings us back to OPEC production levels. (Note that this is for crude oil and does not include the roughly 6 mbd in NGL that are currently being produced). Firstly, this is what the various governments are reporting that they are producing:
Figure 5. OPEC production from official sources (OPEC December MOMR) The total shows, among other things, how Libyan has recovered from their “Arab Spring.” In contrast with the official figures OPEC also posts the values from “secondary sources”.
Figure 6. OPEC production from secondary sources. (OPEC December MOMR) The difference between the two figures for Iran is at around 1 mbd. Overall OPEC production is declining with the increase in non-OPEC production, so perhaps Iran won’t have quite as difficult a time persuading their colleagues to drop production a little more, to help them out. That won’t be at the latest meeting of the OPEC Ministers, which was held in Vienna on December 12th, where it was decided to maintain the current ceiling of 30 mbd. The meeting was largely distracted by debate over who should be the new Secretary General, with this being “kicked down the road” for a decision at the end of May. On the other hand, while Malaysia had promised to halt imports of oil from Iran last March, the IEA is reporting that they increased crude purchases from Iran in November. Whether this is oil ultimately destined for that country, or whether this a convenient transshipment point from Iranian tankers bringing in crude, which is then transferred to other carriers and a second purchaser is not clear, although a Chinese oil trader appears to be involved. A move to make US natural gas available to NATO allies has begun in the Senate, with the intent that perhaps this could wean countries like Turkey from their use of Iranian and Russian natural gas. Whether this will ever amount to much is not clear, since Senator Lugar, the initial author, was defeated in the primary to the last election and thus leaves the Senate at the end of the term.
Read more!
Labels:
EIA,
global demand,
global production,
Iran,
Iraq,
OPEC oil production,
TWIP
Thursday, June 14, 2012
OGPSS - Current oil production and the future of Ghawar
(Updated intro)There is a growing impression being given in the discussion of oil and natural gas supplies, that the world is moving into a period where there will soon be such a plentiful sufficiency of crude that the US may consider exporting some of its production. (h/t Leanan). But if one looks behind the headlines, and particularly at the current status of the largest oilfield contributing toward this rosy picture, the Ghawar field in Saudi Arabia, that optimism becomes more evidently built on a very transient set of data that, as this series of posts seeks to show, will not be sustainable for any significant period into the future.
The three major oil producers (i.e. those producing more than 5 mbd each) are currently seeing surges in production as the world moves to an overall production of 90 mbd. The OPEC June Monthly Oil Market Report (MOMR) notes that this has brought Russia to 10.33 mbd in May, some 100 kbd over the same period in 2011; and Saudi Arabia is reported to have averaged 9.917 mbd in May, up 40 kbd over April. The United States is running at 6.236 Mbd of crude (from the EIA TWIP), while importing 9.117 mbd. The MOMR reports US oil supply at 9.66 mbd on average, but counts more than just crude in this value. The gain over the past year is around 600 kbd. It is interesting to note, in regard to OPEC production the continued difference between the volumes that OPEC reports from direct contact with the suppliers, and that when the numbers are obtained from “secondary sources.”
Figure 1. OPEC production from its members, with values provided by them (OPEC June MOMR)

Figure 2. OPEC production from information provided by secondary sources (OPEC June MOMR).
This surge from the majors has, in part, led the EIA to project that oil prices will, for the remainder of the year, remain relatively stable.

Figure 3. EIA estimate of crude oil prices going forward over the next eighteen months (EIA TWIP)
In the short term, and leading into a national election, there is no significant event (short of a hurricane or two) that obviously threatens this projection – though the Iranian situation and the questionable stability of nations in the Middle East and North Africa (MENA) has to remain a concern. But sadly the continued ill health of the global economy, with no evident savior or realistic plan for growth now visible, means that demand – which OPEC projects will still grow 1.17 mbd y-o-y on average this year, may continue to be met.
I have, however, in previous posts, given my reasons for anticipating that the surge in both Russian production and that in the United States are at near peak, and will soon decline. Saudi Arabia’s fall will be less dramatic and a little later, but the combination does not bode well for the international supply in the next presidential term. The big question with Saudi Arabian production has been, to date, more focused on the production from Ghawar, which at 5 mbd has been the rock on which the overall production builds. But that rock is continuously eroding under the long production periods that its different regions have seen. The final major new effort to bring new production on line in the overall field was the effort at Haradh, down in the South tip of the field.
JoulesBurn has written comprehensively on this region, beginning with the first well that came into production. In 1979, as the late Matt Simmons pointed out in “Twilight in the Desert”, the three northern segments of Ghawar, Ain Dar, Shedgum and North Uthmaniyah were producing 4.2 mbd of the 5.3 mbd total Ghawar output, with South Uthmaniyah producing another 400 kbd. By 2006 North Uthmaniyah was running at a 46% water cut. Joules has taken the historic record for that region of the field and made a short movie presentation included in a post that shows how Uthmaniyah was developed over the years.

Figure 4. Single frame from the movie on drill site development in Uthmaniyah, over time (JoulesBurn)
The sequence of wells, moving inexorably to the crest of the field, shows how the wells had to move as the underlying reservoir became more depleted in oil. Uthmaniyah is the region where the test program to inject carbon dioxide to enhance EOR is under construction, as mentioned earlier, and scheduled for completion in the fourth quarter of 2013. It is worth noting that Aramco are also planning on using more steam injection for enhanced oil recovery (EOR) and that plans have just been signed to increase steam production at the Ju’aymah, Shedgum and Uthmaniyah plants, with completion dates in 2014 and 2015.
Figure 5. Sectors of Ghawar with the date of discovery (Afifi )
As one moves south the quality of the reservoir changes, and becomes more difficult to produce. However as Greg Croft has noted the two lower segments of the field Hawiyah and Haradh were developed with horizontal wells, rather than the vertical wells further north in Ghawar. This has overcome some of the geological constraints and the fact that the productivity index drops from around 140 barrels of oil per day/psi to 45 BOPD/psi at Hawiyah, and 31 at Haradh. In 2008 the Hawiyah NGL recovery plant was commissioned, to yield 310 kbd of ethane and NGL.
The three major oil producers (i.e. those producing more than 5 mbd each) are currently seeing surges in production as the world moves to an overall production of 90 mbd. The OPEC June Monthly Oil Market Report (MOMR) notes that this has brought Russia to 10.33 mbd in May, some 100 kbd over the same period in 2011; and Saudi Arabia is reported to have averaged 9.917 mbd in May, up 40 kbd over April. The United States is running at 6.236 Mbd of crude (from the EIA TWIP), while importing 9.117 mbd. The MOMR reports US oil supply at 9.66 mbd on average, but counts more than just crude in this value. The gain over the past year is around 600 kbd. It is interesting to note, in regard to OPEC production the continued difference between the volumes that OPEC reports from direct contact with the suppliers, and that when the numbers are obtained from “secondary sources.”

Figure 1. OPEC production from its members, with values provided by them (OPEC June MOMR)

Figure 2. OPEC production from information provided by secondary sources (OPEC June MOMR).
This surge from the majors has, in part, led the EIA to project that oil prices will, for the remainder of the year, remain relatively stable.

Figure 3. EIA estimate of crude oil prices going forward over the next eighteen months (EIA TWIP)
In the short term, and leading into a national election, there is no significant event (short of a hurricane or two) that obviously threatens this projection – though the Iranian situation and the questionable stability of nations in the Middle East and North Africa (MENA) has to remain a concern. But sadly the continued ill health of the global economy, with no evident savior or realistic plan for growth now visible, means that demand – which OPEC projects will still grow 1.17 mbd y-o-y on average this year, may continue to be met.
I have, however, in previous posts, given my reasons for anticipating that the surge in both Russian production and that in the United States are at near peak, and will soon decline. Saudi Arabia’s fall will be less dramatic and a little later, but the combination does not bode well for the international supply in the next presidential term. The big question with Saudi Arabian production has been, to date, more focused on the production from Ghawar, which at 5 mbd has been the rock on which the overall production builds. But that rock is continuously eroding under the long production periods that its different regions have seen. The final major new effort to bring new production on line in the overall field was the effort at Haradh, down in the South tip of the field.
JoulesBurn has written comprehensively on this region, beginning with the first well that came into production. In 1979, as the late Matt Simmons pointed out in “Twilight in the Desert”, the three northern segments of Ghawar, Ain Dar, Shedgum and North Uthmaniyah were producing 4.2 mbd of the 5.3 mbd total Ghawar output, with South Uthmaniyah producing another 400 kbd. By 2006 North Uthmaniyah was running at a 46% water cut. Joules has taken the historic record for that region of the field and made a short movie presentation included in a post that shows how Uthmaniyah was developed over the years.

Figure 4. Single frame from the movie on drill site development in Uthmaniyah, over time (JoulesBurn)
The sequence of wells, moving inexorably to the crest of the field, shows how the wells had to move as the underlying reservoir became more depleted in oil. Uthmaniyah is the region where the test program to inject carbon dioxide to enhance EOR is under construction, as mentioned earlier, and scheduled for completion in the fourth quarter of 2013. It is worth noting that Aramco are also planning on using more steam injection for enhanced oil recovery (EOR) and that plans have just been signed to increase steam production at the Ju’aymah, Shedgum and Uthmaniyah plants, with completion dates in 2014 and 2015.
As one moves south the quality of the reservoir changes, and becomes more difficult to produce. However as Greg Croft has noted the two lower segments of the field Hawiyah and Haradh were developed with horizontal wells, rather than the vertical wells further north in Ghawar. This has overcome some of the geological constraints and the fact that the productivity index drops from around 140 barrels of oil per day/psi to 45 BOPD/psi at Hawiyah, and 31 at Haradh. In 2008 the Hawiyah NGL recovery plant was commissioned, to yield 310 kbd of ethane and NGL.
The further development of the lowest segment of Ghawar, down at Haradh, was one of the major projects that Aramco listed as contributing to their ability to produce up to 12.5 mbd. The latest development built on earlier development and because the use of horizontal wells had transitioned into maximum reservoir contact (MRC) designs by the time of Haradh III reduced the anticipated number of wells from 280 verticals to 32 MRC wells.
Figure 6. Planned well layout in Haradh III (from Aramco via JoulesBurn)
In his initial review of how that developed JoulesBurn showed how the wells were developed and laid out and explained how he was able to use satellite images to determine the different components of the production equipment.
It is relevant to note that Joules updated his view of the region in 2010 when he noted that, after looking at the satellite images of the region, he was able to show that instead of the production coming from the original 32 wells, there were actually some 52 production wells connected up, which – as he noted – raise a few questions as to the actual performance of the wells over the original projections.
Aramco have reported, however (pdf) using Real-Time Reserve Management, that it had by the summer of 2009, been more successful than anticipated.
Some of the additional wells drilled were to allow cross-hole tomography (pdf) to monitor the location of the oil:water front which, as production evolved, did not follow the anticipated path. This was particularly important to establish given the 1 km spacing between wells and the more complex geology relative to that further north in Ghawar.
Figure 7. Schematic showing how cross-hole tomography is carried out (Stephen Prenskey )
Figure 8. Image from Crosshole tomography at Haradh (out (Stephen Prenskey)
What is, however, also clear from looking at the different regions of Ghawar is that there are no places left for new programs to restore production as wells become exhausted. If KSA is to sustain its production it must look beyond the King of Oil Fields, who now lies stricken in years.
Read more!
Labels:
crude oil price,
crude oil production,
EIA,
Ghawar,
Haradh,
MOMR,
OPEC,
Saudi Arabia,
Uthmaniyah
Monday, June 27, 2011
The gas shale e-mails and the NYT stories about them
I doubt that this will ever reach the levels of public interest that has led earlier exposures of information to acquire a “gate” appendage, but the New York Times (NYT) has begun a running series of articles, starting this weekend, on e-mails that they have acquired that largely deal with the gas shale business. In the discussion on Focus today, it was the first topic of conversation, and so I thought I would write about what the fuss is about. Not, I should hasten to add, that any of this should come as a surprise to you gentle readers, since many of the “revelations” have been covered here in the past.
There is a considerable body of literature that tends to look at future supplies of natural gas, particularly from shales, through very optimistic lenses. This includes reports from such agencies as the EIA and the IEA that suggest that the world is entering the “Golden Age of Natural Gas.” Recent discoveries and projections have led to estimates that the world will be afloat on natural gas for the foreseeable future, as many countries have natural gas tied to shale layers, and American success in developing these deposits could lead to similar success in other countries, providing large volumes of indigenous fuel, at potentially low cost. Unfortunately, as those who have read my posts here know, much of this is over-inflated and not going to happen. While I discussed the problems with the EIA report back in April (haven’t got round to writing on the IEA report yet,) the fundamental points remain valid. The point brought out by the NYT is that the concerns that I have written about are also prevalent within the industry itself, even while it seeks to draw investors into putting up money to drill more wells. And in that activity, as the articles note, industry has been very successful.
If I can re-iterate some of the concerns, they begin with the cost of the drilling and completion operation. Both parts of this are expensive, the initial cost to drill a vertical well, and then turn it horizontal and run it out thousands of feet within the shale costs millions of dollars, as then does the subsequent series of events that includes fracturing the horizontal well a number (perhaps 30) times and using expensive suspension fluids to force small particles into those cracks so as to prop them open and allow gas to migrate from the rock into the well. The costs as a rough initial marker, run around $5 million dollars per well, though they can go considerably higher.
This sort of investment requires a significant return on investment, and in the best wells initial flow rates of over 10 million cubic feet per day can be achieved. However, as the industry has long known, but likely not the general public, those wells are proving to drop in production very quickly. As I quoted back in that earlier piece:
Part of the problem comes in that the companies seeking investors suggest that the wells will continue to produce for up to 50 years. I would not deny that were the wells to remain open that long that some gas would be still coming out of the wells at the end of that period. However natural gas is a lot less valuable cubic inch for cubic inch than oil, and whereas a simple pump can raise a fractional barrel of oil a day and be profitable, this is much harder to do with a marginal gas producer.
The reason for this is that, unlike oil and coal, natural gas is usually carried (after cleaning to remove water oil and any other contaminants) through a pipeline that often runs (via additional pumps) directly to the customer. They, in turn, don’t usually store it, but burn it as needed, drawing the supply straight from the pipe. The problem that this gives the marginal producer is that the gas in the line must be at a certain pressure if it is to move down that pipe to the customer, and then come out of the nozzles at sufficient flow to be useful. That pressure has to be achieved, at the well once the natural pressure of the gas in the well has fallen over time and production, with a compressor, which cost money to install, run and maintain. At a certain point in the well life the gas being produced falls below the point at which it becomes economic to pay for that compressor (which is only a part of the total costs that an operating well will incur). It may even be (at the rates of decline being seen in many current wells) that the decline is so swift that as soon as the natural pressure falls below that needed for the pipeline, that the well closes and a compressor is never economical. In these cases the well life may well only be three or four years, rather than the fifty of the company model.
There is another concern that the NYT articles raise, and that deals with the change in reserve estimates that are now being made for new wells. I commented on this back when the changes were made in January 2009. To simplify the explanation of the changes before then a company had to physically prove that it had the reserve, and the volume over which it could estimate that the reserve existed was restricted to a relatively short distance from the validation point (usually a well). Investors thus had some degree of certainty about the size of the reserve that they were investing in. (And those who followed the reality Coal series on Spike this season will have seen how the geology changes rapidly, having an immediate impact on production in even a short distance underground - thereby illustrating why the original rules were realistic as a way of protecting the investor).
The change removed the requirement for physical proof, and allowed the company to make an estimate based on the geological data, as established remotely, and without the need for physical validation. As the NYT article notes, this allowed companies to revise their estimates and some did by up to 200%, with the rationale for doing so no longer as clearly visible and verifiable. As the wells are now brought into production those estimates are not always proving valid, according to e-mails within the industry and which the NYT obtained for their stories. The conclusion of monitors in the EIA, as evidenced by similar e-mails released by the agency, is that many of the companies will go bankrupt.
In some ways the response of the industry reminds me a little of what happened after the climate change e-mails were released to the web in what became known as Climategate. Very little specific focus on the criticism, rather moves to obfusticate the issue, and change the subject. In this regard it is sad to note that in the response that Aubrey K. McClendon, Chesapeake's Chief Executive Officer, released on the story his major defense seemed to be
As I mentioned at the top of the post there is little in the NYT stories that is not well known within the industry. The e-mails bear that out. But it will be interesting to see how many papers pick this story up and also to see whether it acquires legs, or is allowed to quietly fade back into the noise. It isn’t after all as though we were betting our economic future on this, is it?
(Wonder if Andrew Montford is going to be tempted to write a new book?)
There is a considerable body of literature that tends to look at future supplies of natural gas, particularly from shales, through very optimistic lenses. This includes reports from such agencies as the EIA and the IEA that suggest that the world is entering the “Golden Age of Natural Gas.” Recent discoveries and projections have led to estimates that the world will be afloat on natural gas for the foreseeable future, as many countries have natural gas tied to shale layers, and American success in developing these deposits could lead to similar success in other countries, providing large volumes of indigenous fuel, at potentially low cost. Unfortunately, as those who have read my posts here know, much of this is over-inflated and not going to happen. While I discussed the problems with the EIA report back in April (haven’t got round to writing on the IEA report yet,) the fundamental points remain valid. The point brought out by the NYT is that the concerns that I have written about are also prevalent within the industry itself, even while it seeks to draw investors into putting up money to drill more wells. And in that activity, as the articles note, industry has been very successful.
If I can re-iterate some of the concerns, they begin with the cost of the drilling and completion operation. Both parts of this are expensive, the initial cost to drill a vertical well, and then turn it horizontal and run it out thousands of feet within the shale costs millions of dollars, as then does the subsequent series of events that includes fracturing the horizontal well a number (perhaps 30) times and using expensive suspension fluids to force small particles into those cracks so as to prop them open and allow gas to migrate from the rock into the well. The costs as a rough initial marker, run around $5 million dollars per well, though they can go considerably higher.
This sort of investment requires a significant return on investment, and in the best wells initial flow rates of over 10 million cubic feet per day can be achieved. However, as the industry has long known, but likely not the general public, those wells are proving to drop in production very quickly. As I quoted back in that earlier piece:
The Day Kimball Hill #A1 is located in Southeast Tarrant County, Texas, and produced an average of 12.97 million cubic feet of natural gas per day in October 2009. Since shale gas wells decline sharply during the first few years, this Barnett Shale well has seen its production fall to 8.66 million cubic feet in November and 6.79 million in December.The initial high yields from these wells fall by as much as 85% in the first year, and while this may still make the producers such as the Day Kimball profitable, that was the most successful well Chesapeake had drilled until then. For the less successful payback is lower and may not cover costs.
Part of the problem comes in that the companies seeking investors suggest that the wells will continue to produce for up to 50 years. I would not deny that were the wells to remain open that long that some gas would be still coming out of the wells at the end of that period. However natural gas is a lot less valuable cubic inch for cubic inch than oil, and whereas a simple pump can raise a fractional barrel of oil a day and be profitable, this is much harder to do with a marginal gas producer.
The reason for this is that, unlike oil and coal, natural gas is usually carried (after cleaning to remove water oil and any other contaminants) through a pipeline that often runs (via additional pumps) directly to the customer. They, in turn, don’t usually store it, but burn it as needed, drawing the supply straight from the pipe. The problem that this gives the marginal producer is that the gas in the line must be at a certain pressure if it is to move down that pipe to the customer, and then come out of the nozzles at sufficient flow to be useful. That pressure has to be achieved, at the well once the natural pressure of the gas in the well has fallen over time and production, with a compressor, which cost money to install, run and maintain. At a certain point in the well life the gas being produced falls below the point at which it becomes economic to pay for that compressor (which is only a part of the total costs that an operating well will incur). It may even be (at the rates of decline being seen in many current wells) that the decline is so swift that as soon as the natural pressure falls below that needed for the pipeline, that the well closes and a compressor is never economical. In these cases the well life may well only be three or four years, rather than the fifty of the company model.
There is another concern that the NYT articles raise, and that deals with the change in reserve estimates that are now being made for new wells. I commented on this back when the changes were made in January 2009. To simplify the explanation of the changes before then a company had to physically prove that it had the reserve, and the volume over which it could estimate that the reserve existed was restricted to a relatively short distance from the validation point (usually a well). Investors thus had some degree of certainty about the size of the reserve that they were investing in. (And those who followed the reality Coal series on Spike this season will have seen how the geology changes rapidly, having an immediate impact on production in even a short distance underground - thereby illustrating why the original rules were realistic as a way of protecting the investor).
The change removed the requirement for physical proof, and allowed the company to make an estimate based on the geological data, as established remotely, and without the need for physical validation. As the NYT article notes, this allowed companies to revise their estimates and some did by up to 200%, with the rationale for doing so no longer as clearly visible and verifiable. As the wells are now brought into production those estimates are not always proving valid, according to e-mails within the industry and which the NYT obtained for their stories. The conclusion of monitors in the EIA, as evidenced by similar e-mails released by the agency, is that many of the companies will go bankrupt.
In some ways the response of the industry reminds me a little of what happened after the climate change e-mails were released to the web in what became known as Climategate. Very little specific focus on the criticism, rather moves to obfusticate the issue, and change the subject. In this regard it is sad to note that in the response that Aubrey K. McClendon, Chesapeake's Chief Executive Officer, released on the story his major defense seemed to be
If the Times was interested in reporting the facts and advancing the debate about the prospective benefits of natural gas usage to energy consumers, it could easily have contacted respected independent reservoir evaluation and consulting firms that annually provide reserve certifications to the U.S. Securities and Exchange Commission or contacted experts at the U.S. Energy Information Administration, the Colorado School of Mines' Potential Gas Committee, the Massachusetts Institute of Technology, Navigant Consulting and others who would gladly have gone on record to confirm the abundant resources that have been made available thanks to the horizontal drilling and hydraulic fracturing techniques that Chesapeake and other industry peers have pioneered in deep shale formations across the U.S.As I noted in my comment on the EIA report there is a huge difference between a reserve (which is economically realizable) and a resource, which is not necessarily economic. The response did not address, in sufficient technical detail, the points that the NYT and released e-mails make, about the decline rates and thus long-term viability of the wells in production. Nor did it highlight in sufficient detail how, outside of the sweet spots such as the Day Kimbell well site, the less productive wells can be expected to remain economically competitive when their production costs could well be over 50% higher than the current price of natural gas as it is sold to the pipeline. Bear in mind also that the gas from shale is competing against natural gas produced from more conventional wells (at lower cost) and against Liquefied Natural Gas (LNG) which is available on the world market. The response by Michael Levi was similarly disappointing, since it tried to diminish the number of operators who might have problems along the “much ado about nothing,” line. While that by Christopher Helman tries to change the subject a little by suggesting that some wells also produce oil that helps with the economics, (this largely relates at the moment to the Eagle Ford shale) rather than the reality that it is the oil that is driving the well production, not the natural gas. And this was covered in these pages last December.
As I mentioned at the top of the post there is little in the NYT stories that is not well known within the industry. The e-mails bear that out. But it will be interesting to see how many papers pick this story up and also to see whether it acquires legs, or is allowed to quietly fade back into the noise. It isn’t after all as though we were betting our economic future on this, is it?
(Wonder if Andrew Montford is going to be tempted to write a new book?)
Read more!
Subscribe to:
Posts (Atom)