Showing posts with label Iraq. Show all posts
Wednesday, December 31, 2014
Tech Talk - Projections 2
It is the end of another year, or more optimistically the start of a new one. Last year I was tempted to make a couple of predictions for the future. And while I can make the case that they were not too wrong, they did not include the drop in oil prices, which has now taken the price of our local gas to below $1.85 a gallon. China has, in recent months, seemed less belligerent about claiming large sections of the China Seas. Whether this has anything to do with the relative success of rigs that have drilled in those waters is something that still remains an unknown.
But it is the changing price of gasoline, itself reflective of the drop in oil prices that is the big news. WTI closed at $53.56 today, and Brent at $57.50 a barrel. Predictions include some who would suggest that the price will continue to fall, until it reaches $20 a barrel, and there it may stay for some time. Well it certainly grabs a headline, but that is about all the value that particular forecast contains. The futures prices suggest that the price has yet to bottom out, though it may be getting close to that value.
Figure 1. Crude oil futures prices (EIA TWIP)
None of the recent news suggests that there will be a further increase in supply to sustain the current imbalance between available supply and demand. Libya is descending even further into a mess, with the oil facilities at the port of Es Sider now being destroyed. The likelihood of significant increases in production and the return to export levels achieved earlier this summer seems increasingly nonexistent. Neither Russia nor Saudi Arabia are likely to increase production, although the latter are continuing to produce the increased volume that they originally put on the market to replace Libyan losses. And so this leaves Iraq and the United States as the key producers who can significantly change the current supply:demand balance in any significant way.
It is probable that, with the agreement between the Kurds and the Central Government now having generated a second payment of $500 million to the KRG that the agreement may be sustained and grow. At present the Kurds are to supply about 550 kbd, of which 300 kbd will travel through the new pipeline to Turkey and thence onto the world market. The rest will be supplied to Baghdad. Meanwhile production in the south (which gets exported through Basra) has seen some increase.
Whether the Kurdish production can increase to over 1 mbd by the end of next year remains open to some doubt, given the ongoing conflict, and the target 6 mbd by the end of the decade for the entire country will likely require changes that the current conflict, which shows no signs of ending, will inhibit.
One of my responses, when the drop in price first started, was to note that the oil supply system has a certain inertia to it. And here I am not talking about the fluctuations in price that one sees in the stock market, and in the price of the crude, but rather in the time that it takes to stop current drilling, postpone future plans and to reduce the production from existing and new developments.
Thus the drop in investment in new production, whether in Russia, Iraq or the United States takes some time to have an impact. Unfortunately for those expecting the price to continue to fall, in the face of the overabundant supply, the situation has changed since historic times, where well production was relatively stable and the oversupply situation was corrected by shutting in production (mainly by Saudi Arabia). Even then it was the perception of the response that drove price rebounds, rather than the immediate reality of the changes.
The system this time is different. The increase in production in the United States has been sustained, and over the last two years has produced more than 2 mbd more than at the start of that period.
Figure 2. US crude oil production over the past two years. (EIA TWIP)
The rig count in North Dakota has already fallen to 170 rigs compared with 187 at this time last year. Concern about the oil price has led companies to cut their investment plans for next years, in some case by 20% so that the rig count is likely to continue to fall. And with the short life at high production values for most wells that will soon affect production. The North Dakota Oil and Gas Division of DMR shows the consequences of this:
Figure 3. Future production estimates from the ND DMR Oil and Gas Division.
The blue line requires about 225 rigs in continuous action, so that won’t happen. By the same token the black line is with no more drilling, and that won’t happen either. The result will be somewhere in between, probably moving the peak out beyond the current projection, but also lowering it as the existing baseline drops with less wells significantly contributing. (Bear in mind it is taking 11,892 wells to sustain current production levels.) But in the short term the line will likely dip down until the price rebounds.
The question now becomes how soon that drop in US production will become evident, and have some impact. I doubt that it will be before June of 2015.
On which note may I wish all readers a Happy, Healthy, Successful and Prosperous 2015.
But it is the changing price of gasoline, itself reflective of the drop in oil prices that is the big news. WTI closed at $53.56 today, and Brent at $57.50 a barrel. Predictions include some who would suggest that the price will continue to fall, until it reaches $20 a barrel, and there it may stay for some time. Well it certainly grabs a headline, but that is about all the value that particular forecast contains. The futures prices suggest that the price has yet to bottom out, though it may be getting close to that value.
Figure 1. Crude oil futures prices (EIA TWIP)
None of the recent news suggests that there will be a further increase in supply to sustain the current imbalance between available supply and demand. Libya is descending even further into a mess, with the oil facilities at the port of Es Sider now being destroyed. The likelihood of significant increases in production and the return to export levels achieved earlier this summer seems increasingly nonexistent. Neither Russia nor Saudi Arabia are likely to increase production, although the latter are continuing to produce the increased volume that they originally put on the market to replace Libyan losses. And so this leaves Iraq and the United States as the key producers who can significantly change the current supply:demand balance in any significant way.
It is probable that, with the agreement between the Kurds and the Central Government now having generated a second payment of $500 million to the KRG that the agreement may be sustained and grow. At present the Kurds are to supply about 550 kbd, of which 300 kbd will travel through the new pipeline to Turkey and thence onto the world market. The rest will be supplied to Baghdad. Meanwhile production in the south (which gets exported through Basra) has seen some increase.
Whether the Kurdish production can increase to over 1 mbd by the end of next year remains open to some doubt, given the ongoing conflict, and the target 6 mbd by the end of the decade for the entire country will likely require changes that the current conflict, which shows no signs of ending, will inhibit.
One of my responses, when the drop in price first started, was to note that the oil supply system has a certain inertia to it. And here I am not talking about the fluctuations in price that one sees in the stock market, and in the price of the crude, but rather in the time that it takes to stop current drilling, postpone future plans and to reduce the production from existing and new developments.
Thus the drop in investment in new production, whether in Russia, Iraq or the United States takes some time to have an impact. Unfortunately for those expecting the price to continue to fall, in the face of the overabundant supply, the situation has changed since historic times, where well production was relatively stable and the oversupply situation was corrected by shutting in production (mainly by Saudi Arabia). Even then it was the perception of the response that drove price rebounds, rather than the immediate reality of the changes.
The system this time is different. The increase in production in the United States has been sustained, and over the last two years has produced more than 2 mbd more than at the start of that period.
Figure 2. US crude oil production over the past two years. (EIA TWIP)
The rig count in North Dakota has already fallen to 170 rigs compared with 187 at this time last year. Concern about the oil price has led companies to cut their investment plans for next years, in some case by 20% so that the rig count is likely to continue to fall. And with the short life at high production values for most wells that will soon affect production. The North Dakota Oil and Gas Division of DMR shows the consequences of this:
Figure 3. Future production estimates from the ND DMR Oil and Gas Division.
The blue line requires about 225 rigs in continuous action, so that won’t happen. By the same token the black line is with no more drilling, and that won’t happen either. The result will be somewhere in between, probably moving the peak out beyond the current projection, but also lowering it as the existing baseline drops with less wells significantly contributing. (Bear in mind it is taking 11,892 wells to sustain current production levels.) But in the short term the line will likely dip down until the price rebounds.
The question now becomes how soon that drop in US production will become evident, and have some impact. I doubt that it will be before June of 2015.
On which note may I wish all readers a Happy, Healthy, Successful and Prosperous 2015.
Read more!
Monday, October 13, 2014
Tech Talk - Pessimistic Talk in a time of surplus
The oil markets are concerned that there is too much oil currently available on the market, and that, as a consequence, oil prices may continue to tumble. Saudi Arabia is reportedly telling Reuters that it is happy with prices that may fall as low as $80 a barrel. As I mentioned the other day, some of this has to do with market share, and the KSA increasing production, and thereby seeking to weaken the likelihood of investment in other places, in turn ensuring their share holds up, not just now, but also down the road. The effect on gas prices has been rapid, with prices in parts of Missouri down to $2.65 a gallon – about a dollar less than I was paying only a week ago.
The effect will also have the benefit of a boost to the economy, which of course can’t hurt in the run-up to an election. But in the longer term it is hard to see how this boost can be sustained for more than a year. In the last post on this I mentioned that, outside of the US, Russia and KSA global oil production had dropped around 3 mbd over the past couple of years. Yet increased production (KSA raised production by 100 kbd in September as part of a total 400 kbd increase from OPEC overall) has, for now, been able to match and surpass this in order to meet the global demand. OPEC continues to expect that demand will increase by a million barrels a day this year and 1.19 mbd next. They further expect that the increased production to meet this will be met from outside the cartel, with the gain declining from 1.68 mbd this year, to 1.24 mbd next year, holding OPEC production to a decline of 300 kbd from the current 29.5 mbd. Simplistically the gains are maximized in increased production from the United States (880 kbd); Canada (250 kbd) and Brazil (190 kbd). They are anticipating a slight drop in Russian production, as part of an overall decline of 80 kbd for the FSU countries.
Part of the problem in projecting the balance revolves around estimating the production from Libya, Iraq and Iran (LII). Libya has reported raising production back to around 800 kbd, but some of that comes from the Shahara field, which was still involved in factional fighting, even as it came back on line at some 20% of normal. The three countries produce around 7 mbd (Iran 3 mbd, Iraq 3.2 mbd; Libya .8 mbd) so that the fluctuations in their production and sales can have a very significant impact on the global oil market, and the prices that are paid – but they function within OPEC, and it may be that the current drops in price are reminder that the big dog in that trailer is KSA, currently running at around 9.7 mbd.
It is foolish to try and predict, over the immediate short-term, how the fighting in Libya and Iraq will progress. Similarly it is hard to see how relations with Iran will change, potentially easing sanctions and allowing them to sell more product into the global market would upset the current balance in trade, and could, in the short-term, increase the glut and lower prices.
But supplies from those outside the cartel and the Americas are continuing to decline. That is not going to change. The rates may fluctuate a little (though the current drop in prices is not going to encourage large scale investment in declining fields) but the overall trend is steadily downward. And it is within that picture that potential changes in the production from the three LII countries have to be placed.
Figure 1. Libyan oil production through September 2013. (EIA)
Yet, as the fields have brought oil back to the market, there is a concurrent fall in global prices, as the EIA note.
Figure 2. Recent oil production from Libya and the price of Brent Crude (EIA)
Pre-conflict Libya was producing over 1.6 mbd, it recovered to 1.4 and is now struggling at around 0.8 mbd. But the prospects for the levels of peace required to sustain even that level do not seem promising. The conflict is worsening and seen as spiraling out of control.
Moving East to Iraq, despite the use of air power, the situation in the North is not improving, although the Kurds have now a pipeline to carry oil up into Turkey that is not controlled by the Islamic State. While it is still a matter of debate how much oil they will be able to sell, they hope that, by the end of next year they may be able to pump as much as 1 mbd, up from the initial 0.1 mbd when the pipeline went on line. At the same time, in the South, the oil fields lie some distance from the conflict, and there seems little threat, at the moment, to the plans to increase production, and move the majority of the oil to the coast for export. It is, therefore possible to foresee an increase in Iraqi production of perhaps a million barrels a day in the next couple of years. Is it likely? It is hard to say. Factional fighting is always hard to predict, and the willingness of those involved to use explosives makes it even more of a problem to predict what will occur, given the vulnerability of pipelines to attack.
Predicting how Iran will change is similarly conflicted, in that it is hard to predict the behavior of those who control the country, and in turn impact oil exports.
But putting this within the context of OPEC, I suspect that overall production will not fall much outside of the current volumes that the MOMR are predicting – which is sensibly overall stable output over the next year or so. And if that is the case, then I would, as mentioned last time, expect to see that the global surplus of oil supply over demand will gradually disappear over the next year, with the impact becoming evident once we reach the summer of 2016. It would be nice to be wrong, but I think it unlikely.
The effect will also have the benefit of a boost to the economy, which of course can’t hurt in the run-up to an election. But in the longer term it is hard to see how this boost can be sustained for more than a year. In the last post on this I mentioned that, outside of the US, Russia and KSA global oil production had dropped around 3 mbd over the past couple of years. Yet increased production (KSA raised production by 100 kbd in September as part of a total 400 kbd increase from OPEC overall) has, for now, been able to match and surpass this in order to meet the global demand. OPEC continues to expect that demand will increase by a million barrels a day this year and 1.19 mbd next. They further expect that the increased production to meet this will be met from outside the cartel, with the gain declining from 1.68 mbd this year, to 1.24 mbd next year, holding OPEC production to a decline of 300 kbd from the current 29.5 mbd. Simplistically the gains are maximized in increased production from the United States (880 kbd); Canada (250 kbd) and Brazil (190 kbd). They are anticipating a slight drop in Russian production, as part of an overall decline of 80 kbd for the FSU countries.
Part of the problem in projecting the balance revolves around estimating the production from Libya, Iraq and Iran (LII). Libya has reported raising production back to around 800 kbd, but some of that comes from the Shahara field, which was still involved in factional fighting, even as it came back on line at some 20% of normal. The three countries produce around 7 mbd (Iran 3 mbd, Iraq 3.2 mbd; Libya .8 mbd) so that the fluctuations in their production and sales can have a very significant impact on the global oil market, and the prices that are paid – but they function within OPEC, and it may be that the current drops in price are reminder that the big dog in that trailer is KSA, currently running at around 9.7 mbd.
It is foolish to try and predict, over the immediate short-term, how the fighting in Libya and Iraq will progress. Similarly it is hard to see how relations with Iran will change, potentially easing sanctions and allowing them to sell more product into the global market would upset the current balance in trade, and could, in the short-term, increase the glut and lower prices.
But supplies from those outside the cartel and the Americas are continuing to decline. That is not going to change. The rates may fluctuate a little (though the current drop in prices is not going to encourage large scale investment in declining fields) but the overall trend is steadily downward. And it is within that picture that potential changes in the production from the three LII countries have to be placed.
Figure 1. Libyan oil production through September 2013. (EIA)
Yet, as the fields have brought oil back to the market, there is a concurrent fall in global prices, as the EIA note.
Figure 2. Recent oil production from Libya and the price of Brent Crude (EIA)
Pre-conflict Libya was producing over 1.6 mbd, it recovered to 1.4 and is now struggling at around 0.8 mbd. But the prospects for the levels of peace required to sustain even that level do not seem promising. The conflict is worsening and seen as spiraling out of control.
Moving East to Iraq, despite the use of air power, the situation in the North is not improving, although the Kurds have now a pipeline to carry oil up into Turkey that is not controlled by the Islamic State. While it is still a matter of debate how much oil they will be able to sell, they hope that, by the end of next year they may be able to pump as much as 1 mbd, up from the initial 0.1 mbd when the pipeline went on line. At the same time, in the South, the oil fields lie some distance from the conflict, and there seems little threat, at the moment, to the plans to increase production, and move the majority of the oil to the coast for export. It is, therefore possible to foresee an increase in Iraqi production of perhaps a million barrels a day in the next couple of years. Is it likely? It is hard to say. Factional fighting is always hard to predict, and the willingness of those involved to use explosives makes it even more of a problem to predict what will occur, given the vulnerability of pipelines to attack.
Predicting how Iran will change is similarly conflicted, in that it is hard to predict the behavior of those who control the country, and in turn impact oil exports.
But putting this within the context of OPEC, I suspect that overall production will not fall much outside of the current volumes that the MOMR are predicting – which is sensibly overall stable output over the next year or so. And if that is the case, then I would, as mentioned last time, expect to see that the global surplus of oil supply over demand will gradually disappear over the next year, with the impact becoming evident once we reach the summer of 2016. It would be nice to be wrong, but I think it unlikely.
Read more!
Labels:
FSU,
Iran,
Iran oil exports,
Iraq,
KSA,
Kurdistan,
Libya,
OPEC MOMR,
Russian production
Sunday, June 29, 2014
Tech Talk - the numbers keep going down
One problem with defining a peak in global oil production is that it is only really evident some time after the event, when one can look in the rearview mirror and see the transition from a growing oil supply to one that is now declining. Before that relatively absolute point, there will likely come a time when global supply can no longer match the global demand for oil that exists at that price. We are beginning to approach the latter of these two conditions, with the former being increasingly probable in the non-too distant future. Rising prices continually change this latter condition, and may initially disguise the arrival of the peak, but it is becoming inevitable.
Over the past two years there has been a steady growth in demand, which OPEC expects to continue at around the 1 mbd range, as has been the recent pattern. The challenge, on a global scale, has been to identify where the matching growth in supply will come from, given the declining production from older oilfields and the decline rate of most of the horizontal fracked wells in shale.
Figure 1. Growth in global demand for oil (OPEC MOMR )
At present the United States is sitting with folk being relatively complacent, anticipating that global oil supplies will remain sufficient, and that the availability of enough oil in the global market to supply that reducing volume of oil that the US cannot produce for itself will continue to exist.
Increasingly over the next couple of years this is going to turn out to have created a false sense of security, and led to decisions on energy that will not easily be reversed. Consider that the Canadians have now decided to built their Pipeline to the Pacific. The Northern Gateway pipeline that Enbridge will build from the oil sands to the port of Kitimat.
Figure 2. Route for the Northern Gateway pipeline (Northern Gateway )
The 731 mile long pipeline will carry 525 kbd to the port, and a twin pipe will carry some 193 kbd of condensate back to Bruderheim to help in the processing of the initial crude. It will, sensibly, move the oil that was to have come down through the Keystone pipeline to American refineries instead to tankers out to the Canadian coast, where it will be shipped to Asia to meet their growing demands. Given the investment in the pipe, infrastructure etc once this oil is committed to that market and the US will not be able to gain that supply back when it is needed in a few years.
There is a secondary impact to the opening of that market that may not be evident for a little time, but it something that the Russians discovered after the gas pipeline connected Turkmenistan to China. Suddenly there is a second market for the product, and producers are no longer tied to having to accept the price that the sole purchaser is willing to pay. At the moment, when there is a sufficiency of oil, that is an incidental, with significant impact only in improving the economics of the oil sand operations, but since it now ties the American refineries that would have received this oil more closely to the Venezuelan production it now receives (a somewhat less reliable supplier) this change remains as something of a future concern. It is not likely, in itself, to initially change the price of oil much ( a minor increase) but it will change the names and nationalities of those that profit from the trade.
The problems that the Keystone pipeline had are, to a degree, a function of the lack of concern over the supply of oil to the American market. As long as oil production continues to increase, from the Bakken and Three Forks in North Dakota, and the Eagle Ford in Texas, then there is no clear evidence for concern. But those wells are cumulatively starting to reach peak production, and the next shales on the list (the Spearfish and the Tyler) don’t hold the potential to match the gains that have been achieved to date. Particularly this is when, as the North Dakota DMR notes, the wells see an average decline of 65% in the first year.
Figure 3. Typical Oil production from a well in the Bakken:Three Forks region of North Dakota (ND DMR Oil and Gas Division )
The projections that gains in production continue thus rely on a continued high level of drilling and production with a defined rig count required having been estimated, and an assumed sustained level of production even beyond the time that the “sweet spots” start to disappear.
Figure 4. Projected production from the Bakken:Three Forks formations, assuming well productions are sustained and that the rigs are available. (ND DMR Oil and Gas Division )
At the end of June, 2014 the rig count in North Dakota is less than 190 (DNR says 189, but Kirk Eggleston notes that some 15 of these are moving, so that the real number is 173, a bit less than 225. That suggests that peak production may be delayed, and lowered from 1.75 mbd down to around 1.4 mbd. This reduction in short-term supply will have less impact in the US than elsewhere since it will be used to release oil that the US would otherwise have bought to the world market, but less than anticipated, and at a slower rate than expected. (Note that Eagle Ford production growth rate is also slowing and that this also affects OPEC projections which anticipates that US oil production will grow some 950 kbd this year).
At the same time, as I have noted in an earlier piece the reliance of many models of future oil supply have focused on Iraq as the next major supplier to sustain growth in production, even as other suppliers decline. But those projections are increasingly obsolete. It is unrealistic to expect the oil export business from Iraq to be sustained and continue to grow in the face of the developing civil war. The nature of the conflict makes it difficult to see how it can be easily resolved, and particularly if the country becomes divided, then the oil pipelines become a target of opportunity to attack the financial underpinnings of the different sectors. It is likely that the pipeline from Kurdistan into Turkey will carry increasing volumes up to Ceyhan and thence to the world market, under better security, given that does not now venture into Sunni territory, but the vulnerabilities likely remain.
The result of these declines in anticipated production (not to mention Libya, the Sudan’s etc) is likely to become evident within a year, while demand continues to grow. The balance need change only a small amount however, for the consequences to be dire. As Mr. Micawber said in “David Copperfield”:
Over the past two years there has been a steady growth in demand, which OPEC expects to continue at around the 1 mbd range, as has been the recent pattern. The challenge, on a global scale, has been to identify where the matching growth in supply will come from, given the declining production from older oilfields and the decline rate of most of the horizontal fracked wells in shale.
Figure 1. Growth in global demand for oil (OPEC MOMR )
At present the United States is sitting with folk being relatively complacent, anticipating that global oil supplies will remain sufficient, and that the availability of enough oil in the global market to supply that reducing volume of oil that the US cannot produce for itself will continue to exist.
Increasingly over the next couple of years this is going to turn out to have created a false sense of security, and led to decisions on energy that will not easily be reversed. Consider that the Canadians have now decided to built their Pipeline to the Pacific. The Northern Gateway pipeline that Enbridge will build from the oil sands to the port of Kitimat.
Figure 2. Route for the Northern Gateway pipeline (Northern Gateway )
The 731 mile long pipeline will carry 525 kbd to the port, and a twin pipe will carry some 193 kbd of condensate back to Bruderheim to help in the processing of the initial crude. It will, sensibly, move the oil that was to have come down through the Keystone pipeline to American refineries instead to tankers out to the Canadian coast, where it will be shipped to Asia to meet their growing demands. Given the investment in the pipe, infrastructure etc once this oil is committed to that market and the US will not be able to gain that supply back when it is needed in a few years.
There is a secondary impact to the opening of that market that may not be evident for a little time, but it something that the Russians discovered after the gas pipeline connected Turkmenistan to China. Suddenly there is a second market for the product, and producers are no longer tied to having to accept the price that the sole purchaser is willing to pay. At the moment, when there is a sufficiency of oil, that is an incidental, with significant impact only in improving the economics of the oil sand operations, but since it now ties the American refineries that would have received this oil more closely to the Venezuelan production it now receives (a somewhat less reliable supplier) this change remains as something of a future concern. It is not likely, in itself, to initially change the price of oil much ( a minor increase) but it will change the names and nationalities of those that profit from the trade.
The problems that the Keystone pipeline had are, to a degree, a function of the lack of concern over the supply of oil to the American market. As long as oil production continues to increase, from the Bakken and Three Forks in North Dakota, and the Eagle Ford in Texas, then there is no clear evidence for concern. But those wells are cumulatively starting to reach peak production, and the next shales on the list (the Spearfish and the Tyler) don’t hold the potential to match the gains that have been achieved to date. Particularly this is when, as the North Dakota DMR notes, the wells see an average decline of 65% in the first year.
Figure 3. Typical Oil production from a well in the Bakken:Three Forks region of North Dakota (ND DMR Oil and Gas Division )
The projections that gains in production continue thus rely on a continued high level of drilling and production with a defined rig count required having been estimated, and an assumed sustained level of production even beyond the time that the “sweet spots” start to disappear.
Figure 4. Projected production from the Bakken:Three Forks formations, assuming well productions are sustained and that the rigs are available. (ND DMR Oil and Gas Division )
At the end of June, 2014 the rig count in North Dakota is less than 190 (DNR says 189, but Kirk Eggleston notes that some 15 of these are moving, so that the real number is 173, a bit less than 225. That suggests that peak production may be delayed, and lowered from 1.75 mbd down to around 1.4 mbd. This reduction in short-term supply will have less impact in the US than elsewhere since it will be used to release oil that the US would otherwise have bought to the world market, but less than anticipated, and at a slower rate than expected. (Note that Eagle Ford production growth rate is also slowing and that this also affects OPEC projections which anticipates that US oil production will grow some 950 kbd this year).
At the same time, as I have noted in an earlier piece the reliance of many models of future oil supply have focused on Iraq as the next major supplier to sustain growth in production, even as other suppliers decline. But those projections are increasingly obsolete. It is unrealistic to expect the oil export business from Iraq to be sustained and continue to grow in the face of the developing civil war. The nature of the conflict makes it difficult to see how it can be easily resolved, and particularly if the country becomes divided, then the oil pipelines become a target of opportunity to attack the financial underpinnings of the different sectors. It is likely that the pipeline from Kurdistan into Turkey will carry increasing volumes up to Ceyhan and thence to the world market, under better security, given that does not now venture into Sunni territory, but the vulnerabilities likely remain.
The result of these declines in anticipated production (not to mention Libya, the Sudan’s etc) is likely to become evident within a year, while demand continues to grow. The balance need change only a small amount however, for the consequences to be dire. As Mr. Micawber said in “David Copperfield”:
Annual income twenty pounds, annual expenditure nineteen [pounds] nineteen [shillings] and six [pence], result happiness. Annual income twenty pounds, annual expenditure twenty pounds ought and six, result misery.
Read more!
Labels:
Bakken,
complacency,
Copperfield,
Eagle Ford shale,
Iraq,
Kurdistan,
Macawber,
Northern Gateway,
peak oil,
Three Forks
Sunday, June 22, 2014
Tech Talk - More on Iraq
A single picture is sufficient to tell the story of the fate of the Baiji Refinery in Iraq. Recently reached by the ISIS forces, it has been the largest refinery in Iraq, with a capacity of 310 kbd, and has been used to provide products for domestic use. Since it would provide fuel for both sides in the conflict it had been left largely intact, but that “understanding” seems to have fallen apart.
Figure 1. View from space of the fire at the Baiji Refinery in Iraq (Slate)
The remaining significant refineries in Iraq are at Daura near Baghdad which can produce 210 kbd, although promised at 280 kbd and Basra in the south, which can produce 140 kbd. There are an additional 11 very small refineries located around the country.
The conflict has already led to a drop in Iraqi exports of around 300 kbd and while this will not immediately impact the United States, given that imports have been declining in the face of growing domestic production, it will affect the overall global market, with longer term impacts on price and availability. India, for example, is already worried. It is quite possible that Iraq will partition, with the northern tier ending up Kurdish.
Figure 2. The Kurdish part of Iraq (Talking Points Memo)
This region has already run a separate pipeline through its own territory up into Turkey and thence to Ceyhan. From there it is tankered, and the Kurds have just sold a shipment to Israel, which arrived at Ashkelon on Friday and unloaded that night. The report has, however, been denied by the Kurdish Ministry. Three more tanker-loads destined for other customers are now in process at Ceyhan. The tanker was one which has, until recently, been unable to find a market.
The impact of the conflict has already caused bidding on the Nassiriya oilfield and refinery to be postponed indefinitely.
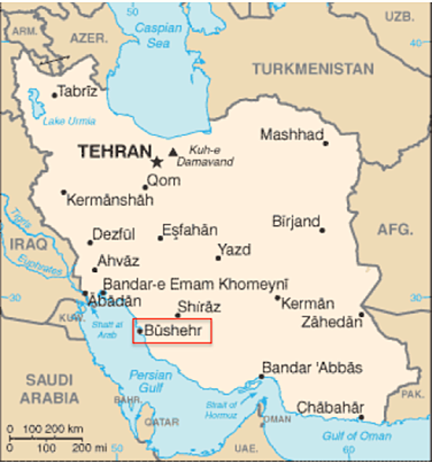
Figure 3. Location of Nassiriya (Red point) (Google Maps)
Bidding on development of the 4 billion barrel oilfield, and associated 300 kbd refinery, was scheduled to have taken place on Thursday, but after being postponed in December and January has now been put off indefinitely.
At the same time Lukoil remains optimistic about expanding the West Qurna 2 field over the next year. The field has started production, and reached 200 kbd and Lukoil is hoping to start filling tankers in the third quarter of this year. The project was shared with Statoil, but they dropped out in 2012. West Qurna is in the South of Iraq, and at present a considerable distance from conflict.
Figure 4. The location of the West Qurna 2 field. (Statoil)
The field is anticipated to ultimately be capable of yielding 1.8 mbd of oil. In order to handle higher flow rates a new agreement has just been signed in which Lukoil will build two new pipelines from the field down to the off-shore terminal at Fao.
As long as the conflict remains north of Baghdad, and the oilfields in the South are not threatened then the major restriction on plans to grow exports from the south to 6 mbd may continue to lie with the Iraqi bureaucracy and the delays in installing the necessary infrastructure needed to support both production and also transport of the oil to the offshore terminals. There has also been some reduction in targets, for example Zubair which had been producing at 200 kbd was originally scheduled to produce at 1.2 mbd a target that was dropped to 850 kbd last year. A 200 kbd gas and oil separation plant (GOSP) has just been contracted, with completion in 2016.
This does not discount, however, that sabotage and terrorist attacks will not have some impact. The main pipeline to Turkey has been closed for months due to such attacks, but while that pipeline runs through Sunni territory, the lines from the Southern fields are all within Shia controlled land, and those in the north are now controlled by the Kurds. Oil companies have, however, as a precaution, begun repatriating some of their employees. Gazprom has just begun production from the Badra field. Originally projected to begin, at 15 kbd, in 2013. Production has now begun, although it is now anticipated that it will be another couple of months before the field reaches that initial 15 kbd target, and 2017 before it peaks at 170 kbd. Gazprom have, at least publically, “no problems” at the site.
Figure 1. View from space of the fire at the Baiji Refinery in Iraq (Slate)
The remaining significant refineries in Iraq are at Daura near Baghdad which can produce 210 kbd, although promised at 280 kbd and Basra in the south, which can produce 140 kbd. There are an additional 11 very small refineries located around the country.
The conflict has already led to a drop in Iraqi exports of around 300 kbd and while this will not immediately impact the United States, given that imports have been declining in the face of growing domestic production, it will affect the overall global market, with longer term impacts on price and availability. India, for example, is already worried. It is quite possible that Iraq will partition, with the northern tier ending up Kurdish.
Figure 2. The Kurdish part of Iraq (Talking Points Memo)
This region has already run a separate pipeline through its own territory up into Turkey and thence to Ceyhan. From there it is tankered, and the Kurds have just sold a shipment to Israel, which arrived at Ashkelon on Friday and unloaded that night. The report has, however, been denied by the Kurdish Ministry. Three more tanker-loads destined for other customers are now in process at Ceyhan. The tanker was one which has, until recently, been unable to find a market.
In May, the Kurds took a further step by leasing two tankers, loading them in Jihan and looking for buyers. Attempts to sell oil to Morocco and other countries were rebuffed, out of solidarity with Iraq and concerns over legal action. It now seems that the Kurds have re-discovered their old ally Israel, which agreed to purchase the oil. To avoid a direct sale, the Kurdish tanker unloaded its oil onto another tanker. It’s unclear if the purchase is a one-off deal or the start of a permanent arrangement.But the Kurdish pipeline is currently limited to a capacity of 100 kbd, whereas the main pipeline running up the center of the country (and through ISIS territory and control) can handle 600 kbd. The potential for a continued drop in Iraqi exports flowing north to Turkey of over 500 kbd is thus now quite possible. However the oilfields in the Kurdish territory are only, at present, producing around 120 kbd. Yet, by the end of the year it is projected that the pipeline can be expanded to handle flows of up to 400 kbd, with that capacity being reached as additional oilfields around Kirkuk are connected into the system and production raised. In the meantime additional oil is being trucked up to Turkey.
The impact of the conflict has already caused bidding on the Nassiriya oilfield and refinery to be postponed indefinitely.
Figure 3. Location of Nassiriya (Red point) (Google Maps)
Bidding on development of the 4 billion barrel oilfield, and associated 300 kbd refinery, was scheduled to have taken place on Thursday, but after being postponed in December and January has now been put off indefinitely.
At the same time Lukoil remains optimistic about expanding the West Qurna 2 field over the next year. The field has started production, and reached 200 kbd and Lukoil is hoping to start filling tankers in the third quarter of this year. The project was shared with Statoil, but they dropped out in 2012. West Qurna is in the South of Iraq, and at present a considerable distance from conflict.
Figure 4. The location of the West Qurna 2 field. (Statoil)
The field is anticipated to ultimately be capable of yielding 1.8 mbd of oil. In order to handle higher flow rates a new agreement has just been signed in which Lukoil will build two new pipelines from the field down to the off-shore terminal at Fao.
As long as the conflict remains north of Baghdad, and the oilfields in the South are not threatened then the major restriction on plans to grow exports from the south to 6 mbd may continue to lie with the Iraqi bureaucracy and the delays in installing the necessary infrastructure needed to support both production and also transport of the oil to the offshore terminals. There has also been some reduction in targets, for example Zubair which had been producing at 200 kbd was originally scheduled to produce at 1.2 mbd a target that was dropped to 850 kbd last year. A 200 kbd gas and oil separation plant (GOSP) has just been contracted, with completion in 2016.
This does not discount, however, that sabotage and terrorist attacks will not have some impact. The main pipeline to Turkey has been closed for months due to such attacks, but while that pipeline runs through Sunni territory, the lines from the Southern fields are all within Shia controlled land, and those in the north are now controlled by the Kurds. Oil companies have, however, as a precaution, begun repatriating some of their employees. Gazprom has just begun production from the Badra field. Originally projected to begin, at 15 kbd, in 2013. Production has now begun, although it is now anticipated that it will be another couple of months before the field reaches that initial 15 kbd target, and 2017 before it peaks at 170 kbd. Gazprom have, at least publically, “no problems” at the site.
Read more!
Labels:
Badra,
Baiji refinery,
Ceyhan,
Gazprom,
Iraq,
Iraqi oil exports,
Israel,
Kirkuk,
Kurdistan,
Lukoil,
oil pipelines,
West Qurna,
Zubair
Sunday, January 5, 2014
Tech Talk - Predictions
From time to time I have written about the dubious assumptions that lie behind some of the predictions made by Energy Agencies and some of the larger oil producing companies as they predict the energy supplies and demands of the next few years.
It is relatively simple to make those criticisms given that one has only to compare ongoing reality with the assumptions to be able to judge that the future is unlikely to be as rosy as any of these folk imagine.
However there is this strong tradition of making the odd prediction at the start of the New Year. Yet having just spent about 2 hours digging snow out of my drive (an hour and a half for the first session which moved most of the snow and then thirty minutes to remove all the snow shifted back into the drive when the snowplow came by clearing the center of the road) my creative buds are a little slow this evening, but I would suspect that it is not hard to make one or two suggestions, and then go back and so how they panned out.
Last year I was quite pessimistic about the future, given the pull back in Arctic drilling following the grounding of the Shell drillship and had some question on the stability of the domestic production levels. Well a year later the situation in the Arctic has perhaps grown a little less encouraging for those who would anticipate early development of those resources, but on the other hand domestic production has continued to increase.
For next year I suspect that the situation with China, in terms of its attitude to acquiring sufficient energy reserves, will not improve. There are already suggestions that China will adjust its position in regard to the importation of Iranian oil and may increase purchases, despite the ongoing sanctions. Similarly it is refusing to recognize arbitration in its dispute over ownership of the China Seas (East and South). To keep the projection vague (and thus less likely to be too far off) I would expect that this will get worse over the next year, and the steps China is willing to take to ensure future energy supplies will become more obvious.
In this regard I suspect China will continue to beat out India in the pursuit of available resources around the world, though the consequences for this in India won’t likely become evident for a couple of years yet.
There will likely continue to be enough available crude to meet demand through next year (depending on how the various conflicts in the different countries of the Middle East develop) but it may be the last year in which this holds true. With the Kingdom of Saudi Arabia determined to hold production at a maximum of around 10 mbd, with Iraq increasingly troubled by growing sectarian violence and with other regional countries similarly destabilizing there are only a few places where increased production can be brought on line to meet demand – and that problem may become evident in 2015.
So having made a couple of relatively obvious suggestions let’s see how 2014 turns out for us all – though I hope it brings you Prosperity and Success!
It is relatively simple to make those criticisms given that one has only to compare ongoing reality with the assumptions to be able to judge that the future is unlikely to be as rosy as any of these folk imagine.
However there is this strong tradition of making the odd prediction at the start of the New Year. Yet having just spent about 2 hours digging snow out of my drive (an hour and a half for the first session which moved most of the snow and then thirty minutes to remove all the snow shifted back into the drive when the snowplow came by clearing the center of the road) my creative buds are a little slow this evening, but I would suspect that it is not hard to make one or two suggestions, and then go back and so how they panned out.
Last year I was quite pessimistic about the future, given the pull back in Arctic drilling following the grounding of the Shell drillship and had some question on the stability of the domestic production levels. Well a year later the situation in the Arctic has perhaps grown a little less encouraging for those who would anticipate early development of those resources, but on the other hand domestic production has continued to increase.
For next year I suspect that the situation with China, in terms of its attitude to acquiring sufficient energy reserves, will not improve. There are already suggestions that China will adjust its position in regard to the importation of Iranian oil and may increase purchases, despite the ongoing sanctions. Similarly it is refusing to recognize arbitration in its dispute over ownership of the China Seas (East and South). To keep the projection vague (and thus less likely to be too far off) I would expect that this will get worse over the next year, and the steps China is willing to take to ensure future energy supplies will become more obvious.
In this regard I suspect China will continue to beat out India in the pursuit of available resources around the world, though the consequences for this in India won’t likely become evident for a couple of years yet.
There will likely continue to be enough available crude to meet demand through next year (depending on how the various conflicts in the different countries of the Middle East develop) but it may be the last year in which this holds true. With the Kingdom of Saudi Arabia determined to hold production at a maximum of around 10 mbd, with Iraq increasingly troubled by growing sectarian violence and with other regional countries similarly destabilizing there are only a few places where increased production can be brought on line to meet demand – and that problem may become evident in 2015.
So having made a couple of relatively obvious suggestions let’s see how 2014 turns out for us all – though I hope it brings you Prosperity and Success!
Read more!
Sunday, December 22, 2013
Tech Talk - The ExxonMobil 2014 Outlook for Energy
Each year the large oil companies produce their forecasts for future demand and supply of fuel, and these can be compared – both with earlier forecasts and with each other and the forecasts from different agencies. Last week, for example, I looked at the IEA forecast through 2035, while today’s subject is the ExxonMobil (EM) 2014 Outlook for Energy. (See also the 2013 Outlook Review and the 2011 Outlook Review).
In conformity with the IEA review EM consider that the energy growth rate for India will be perhaps one of the more significant metrics of the future. EM note that by 2040 one third of the global population will live in either India or China and between them they amount for half the global increase in energy demand, which is anticipated to be about 35% higher than the 2010 figure. India has already become the third largest energy consumer (after China and the United States).
One of the greatest drivers to energy demand growth comes as the population moves from the farms to the city and, as EM note, China has seen the urban population grow from 25 to 50% of the total in the past 20 years increasing residential power demand 20-fold. But that growth will slow in the future, reaching 75% by 2040. India (and Africa) are however further behind this curve with India being at 30% and Africa at 40%. Thus, as they still have further to move up the ladder, EM anticipate there will be concomitant increases in demand as these changes occur.
Figure 1. Projected growth in energy demand for major groups until 2040. (Illustrations are taken from EM The Outlook for Energy:A View to 2040 except where stated) (The key growth countries are Brazil, Indonesia, Saudi Arabia, Iran, South Africa, Nigeria, Thailand, Egypt Mexico and Turkey).
One of the small niggles with this projection is that it assumes a virtually limitless source of fuel.
This is noteworthy because, as yet there is not much gap in the world between the quantities of fuels desired, and those available. Yet China is moving aggressively to ensure that it will be able to get what it needs when this changes. Such is not the case either with India, which has often failed in head-to-head bids for energy supplies when going against China, or much of the rest of the world who continue to accept the assurances that EM inter alia are promulgating with reports such as this, that there is a plentiful sufficiency.
Continuing along this unrestricted “ideal world” trail that EM are laying out, they continue to foresee that there will be a substantial improvement in energy efficiency over the next decades, leading to an increased decoupling of the relationship between GDP growth and Energy demand.
Figure 2. Projected growth in GDP and Energy demand through 2040.
Some of this EM project will come from the increased efficiency of automobiles and the greater acceptance of hybrid vehicles, with a penetration of 35% of the market – up from the 1% it held in 2010. While they do not expect that natural gas will have much impact on personal vehicles they do expect some impact with commercial transportation. The changes will lift the light vehicle mileage from the 24 mpg of 2010 to 46 mpg by 2040. (This is 1 mpg lower than their projection for mileage change given last year).
Figure 3. Changes in the composition and size of the global car fleet.
In terms of electricity supply EM foresee a sharply changing picture of the composition of the fuel sources for global supply, with coal barely holding its own throughout the period, and oil declining, while the remaining sources all grow in market size.
Figure 4. Sources of fuel and market size for electric power generation through 2040.
So where will the oil supply come from? Well EM remain confident in the future growth of North American oil.
Figure 5. EIA projections for US petroleum production through 2040 (EIA).
Ron, has refined this plot and shows that US production may well peak in either 2015 or 2016, and go into significant decline by 2020. This is quite a contrast to the EM projection.
Figure 6. EM projection for change in liquids production through 2040
EM expect that Deepwater production will increase with major supplies coming from Angola, Nigeria, the Gulf of Mexico and Brazil, with production rising to a peak in around 2040. They expect tight oil supplies, however, to increase by a factor of tenfold from 2010 to 2040. The major new player in that field is anticipated to be Russia whose output is still expected to trail that in North America (which includes Canada and Mexico).
One of the great questions of the next decade relates to the development of the heavy oils of Venezuela and Canada. EM expects that the Canadian production will increase 200% with the rest of the total gain of 300% of the 2010 total presumably coming from Venezuela. However Venezuelan development remains a complex situation.
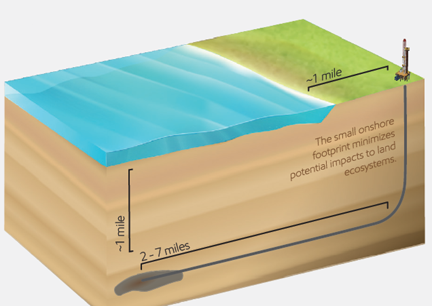
One of the most promising developments that EM describe is the use of extended reach horizontal wells, that are now allowing sub-sea deposits to be tapped using land-based rigs. At Sakhalin Island, for example, they note that they were able to drill one well in the Chayvo field that extended out 7 miles.
Figure 7. Illustration by EM of their extended reach well capabilities.
The other source that EM cite for increased production comes from OPEC and production gains in the Middle East. Given that Saudi Arabia have stated that 10 mbd is their intended upper limit to production (give or take a little) one presumes that the roughly 9 mbd gain is largely anticipated to come from Iraq. EM don’t actually say, nor did they last year, but it is interesting to end by comparing last year’s projection for future growth with the one shown in Figure 6.
Figure 8. The projected volumes for liquid supply growth as provided by ExxonMobil last year in their 2013 report.
On which cheerful note I wish you all the Compliments of the Season, and hopes that you have a safe and happy break.
In conformity with the IEA review EM consider that the energy growth rate for India will be perhaps one of the more significant metrics of the future. EM note that by 2040 one third of the global population will live in either India or China and between them they amount for half the global increase in energy demand, which is anticipated to be about 35% higher than the 2010 figure. India has already become the third largest energy consumer (after China and the United States).
One of the greatest drivers to energy demand growth comes as the population moves from the farms to the city and, as EM note, China has seen the urban population grow from 25 to 50% of the total in the past 20 years increasing residential power demand 20-fold. But that growth will slow in the future, reaching 75% by 2040. India (and Africa) are however further behind this curve with India being at 30% and Africa at 40%. Thus, as they still have further to move up the ladder, EM anticipate there will be concomitant increases in demand as these changes occur.
Figure 1. Projected growth in energy demand for major groups until 2040. (Illustrations are taken from EM The Outlook for Energy:A View to 2040 except where stated) (The key growth countries are Brazil, Indonesia, Saudi Arabia, Iran, South Africa, Nigeria, Thailand, Egypt Mexico and Turkey).
One of the small niggles with this projection is that it assumes a virtually limitless source of fuel.
Ongoing advances in exploration and production technology continue to expand the size of the world’s recoverable crude and condensate resources. Despite rising liquids production, we estimate that by 2040, about 65 percent of the world’s recoverable crude and condensate resource base will have yet to be produced.While that projection will be discussed a little further later, it should be noted that in the next decade China’s energy demand will continue to grow at roughly current rates and that they have been quite assiduous in finding new sources to provide that energy. This is already providing some of the backstory to the growing tensions between China and its neighbors in the South and East China seas.
This is noteworthy because, as yet there is not much gap in the world between the quantities of fuels desired, and those available. Yet China is moving aggressively to ensure that it will be able to get what it needs when this changes. Such is not the case either with India, which has often failed in head-to-head bids for energy supplies when going against China, or much of the rest of the world who continue to accept the assurances that EM inter alia are promulgating with reports such as this, that there is a plentiful sufficiency.
Continuing along this unrestricted “ideal world” trail that EM are laying out, they continue to foresee that there will be a substantial improvement in energy efficiency over the next decades, leading to an increased decoupling of the relationship between GDP growth and Energy demand.
Figure 2. Projected growth in GDP and Energy demand through 2040.
Some of this EM project will come from the increased efficiency of automobiles and the greater acceptance of hybrid vehicles, with a penetration of 35% of the market – up from the 1% it held in 2010. While they do not expect that natural gas will have much impact on personal vehicles they do expect some impact with commercial transportation. The changes will lift the light vehicle mileage from the 24 mpg of 2010 to 46 mpg by 2040. (This is 1 mpg lower than their projection for mileage change given last year).
Figure 3. Changes in the composition and size of the global car fleet.
In terms of electricity supply EM foresee a sharply changing picture of the composition of the fuel sources for global supply, with coal barely holding its own throughout the period, and oil declining, while the remaining sources all grow in market size.
Figure 4. Sources of fuel and market size for electric power generation through 2040.
So where will the oil supply come from? Well EM remain confident in the future growth of North American oil.
North American liquids production is expected to rise by more than 40 percent from 2010 to 2040, boosted by gains in oil sands, tight oil and NGLs. With production rising and demand falling, North America is expected to shift from a significant crude oil importer to a fairly balanced position by 2030.The concern with these projections (which are substantially more optimistic than the IEA forecast, lies in their assumption of unfettered growth. As Ron Patterson just noted the EIA is anticipating that US volumes will peak in 2019, and then decline.
Latin American liquids production will nearly double through 2040 with the development of the Venezuelan oil sands, Brazilian deepwater and biofuels.
The Middle East is expected to have the largest absolute growth in liquids production over the Outlook period — an increase of more than 35 percent. This increase will be due to conventional oil developments in Iraq, as well as growth in NGLs and rising production of tight oil toward the latter half of the Outlook period.
Figure 5. EIA projections for US petroleum production through 2040 (EIA).
Ron, has refined this plot and shows that US production may well peak in either 2015 or 2016, and go into significant decline by 2020. This is quite a contrast to the EM projection.
Figure 6. EM projection for change in liquids production through 2040
EM expect that Deepwater production will increase with major supplies coming from Angola, Nigeria, the Gulf of Mexico and Brazil, with production rising to a peak in around 2040. They expect tight oil supplies, however, to increase by a factor of tenfold from 2010 to 2040. The major new player in that field is anticipated to be Russia whose output is still expected to trail that in North America (which includes Canada and Mexico).
One of the great questions of the next decade relates to the development of the heavy oils of Venezuela and Canada. EM expects that the Canadian production will increase 200% with the rest of the total gain of 300% of the 2010 total presumably coming from Venezuela. However Venezuelan development remains a complex situation.
One of the most promising developments that EM describe is the use of extended reach horizontal wells, that are now allowing sub-sea deposits to be tapped using land-based rigs. At Sakhalin Island, for example, they note that they were able to drill one well in the Chayvo field that extended out 7 miles.
Figure 7. Illustration by EM of their extended reach well capabilities.
The other source that EM cite for increased production comes from OPEC and production gains in the Middle East. Given that Saudi Arabia have stated that 10 mbd is their intended upper limit to production (give or take a little) one presumes that the roughly 9 mbd gain is largely anticipated to come from Iraq. EM don’t actually say, nor did they last year, but it is interesting to end by comparing last year’s projection for future growth with the one shown in Figure 6.
Figure 8. The projected volumes for liquid supply growth as provided by ExxonMobil last year in their 2013 report.
On which cheerful note I wish you all the Compliments of the Season, and hopes that you have a safe and happy break.
Read more!
Labels:
China,
EIA,
Energy future,
ExxonMobil,
hybrids,
IEA,
India,
Iraq,
World oil production
Tuesday, December 17, 2013
Tech Talk - The IEA World Energy Outlook
It is the time of year again that different folk stare into their own versions of a crystal ball and project how much energy the world will need in the future, and where they think that it will come from. It is interesting to look at these various predictions as the global supply picture morphs under a changing reality.
One of the changes in reality that is likely to have significant impact in the near-term is the flow in the Alyeska pipeline. Long-time concerns over the decline in flow and the effect that heat loss has on the contents is leading to new work to change the pipe dynamics and possibly to remove the water before it is pumped, lowering the temperatures at which the line currently has to be maintained.
Figure 1. Historic and Projected flows through the Alaskan pipeline (Alyseka)
The precipitation of ice and water from the oil, within the pipeline will otherwise reach a point that flow will stop – potentially at around 300 kbd, at a date not too far into the future.
In their annual World Energy Outlook, the IEA continue to see, overall, a gain in US oil production through 2025, largely coming through the light tight oil of the sort being produced from North Dakota and West Texas.
Figure 2. IEA projections for global oil production growth in the years to 2035. (IEA)
However in the following years , out to 2035, that supply also declines so that by 2035 the US will likely be in the same sort of supply situation, relying heavily on imports, that it is today.
The IEA make the point that the only longer term places that can be relied on are Brazil, with the off-shore fields, and the Middle East. Looking first at Brazil, which continues to have some problems in bringing their fields on-line on-schedule, the IEA anticipates that the major production growth is likely to be in the next ten years, but will continue beyond that point.
Figure 3. Brazilian oil production through 2035. (IEA)
Because the IEA foresee that Brazil will continue to supply the largest portion of its energy from hydropower this means that the largest volume of the fuel can be exported, where it meets the continually growing demand from the rest of the world.
Figure 4. Anticipates sources of power for electricity generation in 2035 (IEA)
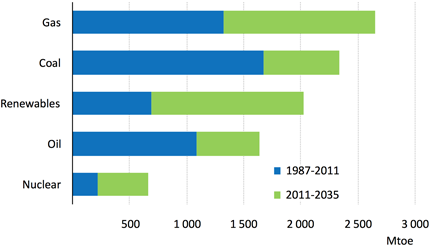
At the same time the IEA anticipate that primary energy demand will still focus heavily on fossil fuel sources through 2035, with renewable energy only slowly nibbling away at the totals so that, by 2035 fossil fuel will have dropped from contributing the current 82% down to 75% of the larger total.
Figure 5. Anticipated changes in the sources of primary global energy through 2035. (IEA)
Although, by that time the IEA foresee a change not only in the places where demand is highest, but also in the relative rankings. The major finding in this regard that they draw attention to is the anticipated greater growth rates in India than in China, as time passes.
Figure 6. Changed picture of global energy demand in the year 2035 (IEA)
Other than projecting the growth in demand there is the need to anticipate where the supply will come from, and in this regard the IEA projects that the largest growth will come from natural gas (Figure 5), although crude oil is still anticipated to grow, with refinery capacity increasing to about 104 mbd.
It is interesting that the IEA projections for oil production growth hang most heavily on increased production from the Middle East. It requires very little glance into their crystal ball to assume that this is likely based on the increased production from Iraq, an assumption that was, last year, a largely common assumption to all future projections. Unfortunately for those earlier projections in the interim the initial Iraqi targets have been cut back, with current targets being reduced below the “best case” scenario that the IEA had projected in their review of the country.
Taken with the possibility of a significant and sudden decline in production from Alaska, and the likelihood that the rate of drilling in the Bakken will decline, as prospects become more uneconomic suggests that it will be difficult to sustain the levels of crude output that the IEA are anticipating can be made available to meet their projected needs.
By the same token the growth in the global demand for natural gas is predicated on the reserves uncovered in the United States being exported, as needed, to the rest of the world. It is, however, also predicated on the price of natural gas remaining relatively stable in terms of current costs.
Figure 7. Anticipated components of the costs of US LNG when shipped to either Asia or Europe (IEA)
The underlying flaw in that assumption is that the costs of purchasing the natural gas in the United States are now starting to rise to a more realistic level relative to the costs of production from tight shales. This week's OGJ, for example has noted the EIA Short Term Energy and Winter Fuels outlook that notes that prices are expected to rise 13% this winter over last (on constant demand) to $3.62 per kcf. Given that the EIA is expecting the price to inch upwards towards $5.00 per kcf over the next year this makes the IEA report appear a little over-optimistic on costs and hence market share.
Figure 8. Natural Gas Prices in the United States (EIA)
This is likely to be particularly true as some of the older gas fields, such as the Haynesville, appear to be in decline even at prices in the $4 - $5 per kcf range.
Figure 9. Natural Gas Production from the Haynesville Shale (OGJ )
Increasing the price of natural gas will reduce its competitive advantage over coal and in consequence I would anticipate that power generating companies will continue to build boilers that can handle both coal and natural gas, and that the longer-term continued switch to natural gas will become more of an economic choice dependent on how much LNG finally comes onto the market from the United States and at what price. I am not convinced that this will be quite the bargain and cornucopia that it is anticipated to become. In other words I still find the IEA view of the future to be a somewhat optimistic one, given the realities that are now unfolding before us.
One of the changes in reality that is likely to have significant impact in the near-term is the flow in the Alyeska pipeline. Long-time concerns over the decline in flow and the effect that heat loss has on the contents is leading to new work to change the pipe dynamics and possibly to remove the water before it is pumped, lowering the temperatures at which the line currently has to be maintained.
Figure 1. Historic and Projected flows through the Alaskan pipeline (Alyseka)
The precipitation of ice and water from the oil, within the pipeline will otherwise reach a point that flow will stop – potentially at around 300 kbd, at a date not too far into the future.
In their annual World Energy Outlook, the IEA continue to see, overall, a gain in US oil production through 2025, largely coming through the light tight oil of the sort being produced from North Dakota and West Texas.
Figure 2. IEA projections for global oil production growth in the years to 2035. (IEA)
However in the following years , out to 2035, that supply also declines so that by 2035 the US will likely be in the same sort of supply situation, relying heavily on imports, that it is today.
The IEA make the point that the only longer term places that can be relied on are Brazil, with the off-shore fields, and the Middle East. Looking first at Brazil, which continues to have some problems in bringing their fields on-line on-schedule, the IEA anticipates that the major production growth is likely to be in the next ten years, but will continue beyond that point.
Figure 3. Brazilian oil production through 2035. (IEA)
Because the IEA foresee that Brazil will continue to supply the largest portion of its energy from hydropower this means that the largest volume of the fuel can be exported, where it meets the continually growing demand from the rest of the world.
Figure 4. Anticipates sources of power for electricity generation in 2035 (IEA)
At the same time the IEA anticipate that primary energy demand will still focus heavily on fossil fuel sources through 2035, with renewable energy only slowly nibbling away at the totals so that, by 2035 fossil fuel will have dropped from contributing the current 82% down to 75% of the larger total.
Figure 5. Anticipated changes in the sources of primary global energy through 2035. (IEA)
Although, by that time the IEA foresee a change not only in the places where demand is highest, but also in the relative rankings. The major finding in this regard that they draw attention to is the anticipated greater growth rates in India than in China, as time passes.
Figure 6. Changed picture of global energy demand in the year 2035 (IEA)
Other than projecting the growth in demand there is the need to anticipate where the supply will come from, and in this regard the IEA projects that the largest growth will come from natural gas (Figure 5), although crude oil is still anticipated to grow, with refinery capacity increasing to about 104 mbd.
It is interesting that the IEA projections for oil production growth hang most heavily on increased production from the Middle East. It requires very little glance into their crystal ball to assume that this is likely based on the increased production from Iraq, an assumption that was, last year, a largely common assumption to all future projections. Unfortunately for those earlier projections in the interim the initial Iraqi targets have been cut back, with current targets being reduced below the “best case” scenario that the IEA had projected in their review of the country.
Taken with the possibility of a significant and sudden decline in production from Alaska, and the likelihood that the rate of drilling in the Bakken will decline, as prospects become more uneconomic suggests that it will be difficult to sustain the levels of crude output that the IEA are anticipating can be made available to meet their projected needs.
By the same token the growth in the global demand for natural gas is predicated on the reserves uncovered in the United States being exported, as needed, to the rest of the world. It is, however, also predicated on the price of natural gas remaining relatively stable in terms of current costs.
Figure 7. Anticipated components of the costs of US LNG when shipped to either Asia or Europe (IEA)
The underlying flaw in that assumption is that the costs of purchasing the natural gas in the United States are now starting to rise to a more realistic level relative to the costs of production from tight shales. This week's OGJ, for example has noted the EIA Short Term Energy and Winter Fuels outlook that notes that prices are expected to rise 13% this winter over last (on constant demand) to $3.62 per kcf. Given that the EIA is expecting the price to inch upwards towards $5.00 per kcf over the next year this makes the IEA report appear a little over-optimistic on costs and hence market share.
Figure 8. Natural Gas Prices in the United States (EIA)
This is likely to be particularly true as some of the older gas fields, such as the Haynesville, appear to be in decline even at prices in the $4 - $5 per kcf range.
Figure 9. Natural Gas Production from the Haynesville Shale (OGJ )
Increasing the price of natural gas will reduce its competitive advantage over coal and in consequence I would anticipate that power generating companies will continue to build boilers that can handle both coal and natural gas, and that the longer-term continued switch to natural gas will become more of an economic choice dependent on how much LNG finally comes onto the market from the United States and at what price. I am not convinced that this will be quite the bargain and cornucopia that it is anticipated to become. In other words I still find the IEA view of the future to be a somewhat optimistic one, given the realities that are now unfolding before us.
Read more!
Labels:
Alaska pipeline,
Brazil,
China,
global demand,
Haynesville shale,
IEA,
India,
Iraq,
Natural gas,
World Energy Outlook
Tuesday, December 3, 2013
Tech Talk - Falling gas prices and Iraq
Filling up at the local gas station yesterday I noted that prices are still below $3.00 a gallon, though at $2.99 only just below. Going back to the BBC Calculator this is still $2.04 less per tank than the regional average, and $86 less than I would pay in Italy. So even though the costs are rising over the last time I looked, they are still relatively low.
Figure 1. Relative fuel costs ($/gal) in different locations around the world. (BBC Calculator)
The orange line in figure 1 shows what I paid, and the darker grey horizontal line the regional cost here in the MidWest.
The EIA have noted in last week’s TWIP that the national price is as low as it has been since the beginning of 2011.
Figure 2. Average US retail prices for gasoline (EIA).
The EIA continues to describe the causes of these relatively low prices:
The problems in Iraq, for example, have now reached the point that the Turkish government is directly working with the Kurds in Northern Iraq, to develop the oil in the Kurdish northern part of Iraq. This comes at a time that Iraq has been negotiating with the different major oil companies that had contracted to help Iraq reach an overall production target of 12 mbd by 2017. There have been considerable doubts cast on that original estimate, with the IEA producing a report, reviewed in an earlier post that concluded that the country would be lucky to achieve a production goal of 6 mbd by 2020, with an out year estimate that the country would be able to reach 8.3 mbd only by 2035.
Recognizing some of the difficulties in gearing up oil production at the different oilfields around Iraq (some of which were discussed in another post last June) production targets for 2017 had already been scaled back to a goal of 9 mbd by 2017, a drop of 25%. Now there has been discussion between Iraq and its partners for the various fields to drop those target values further, despite the large scale of the reserves that are considered available.
Figure 3. Oil reserves by field (Financial Times)
Exxon Mobil had 60% of the stake in the West Qurna oil field, but after it had started to work with the Kurds independently of Baghdad it found that relations with the Central Government rather chilled. Exxon Mobil has thus sold 25% of their stake to Petro China, and 10% to Pertamina of Indonesia, bringing the EM stake down to 25%. The current discussions between the companies and the Iraqi government are aimed at reducing the production target of the field by around 1 mbd..
Oil has just started to be produced at West Qurna Two, but the initial target is to have commercial production by the end of the year has suffered from local disruptions and the initial goal to reach a production of 400 kbd by the end of 2014 is now also in doubt. Commercial production is now not estimated to begin until perhaps the end of the first quarter of 2014. Initially the field was to be producing 1.9 mbd by 2017. That goal had been lowered to 1.2 mbd at the end of 2012. How the current disruptions will play into that target is difficult to estimate yet, but a year ago the parties were assuming that production would have already reached 150 kbd.
Earlier this year ENI had agreed with the Ministry of Oil to lower the target peak production from the Zubair field from 1.2 mbd to 850 kbd with that goal to be reached in 2016.
Discussions are not yet complete on new target production to be achieved from the Majnoon field. Shell has just announced the start of production from the field with the intent of raising production to over 175 kbd by the end of the year. However the long term target of raising production to 1.8 mbd is now in question. Shell is reportedly suggesting that the 2017 target be lowered to 1 mbd.
Similarly over at the Rumaila field BP is in discussion over long-term production, although earlier last month Schlumberger stopped work at the field because of local disturbances. With the field producing 1.4 mbd the disturbance was short-lived and is not reported to have affected current production, though it is indicative of tensions within the country. Current discussions are aimed at lowering the 2017 target production by around 800 kbd.
When these cuts are combined the total reduction is around 3.65 mbd, taking 2017 production down to 5.35 mbd, which is below the earlier best case scenario envisaged by the IEA.
OPEC notes that, after reaching a peak recent production of 3.194 mbd in August, production has fallen back below 3 mbd in September and October, and with Saudi Arabia also cutting back below 10 mbd in October the Organization is lowering production to meet the reduced winter demand, albeit the reduction from Iraq might not have been anticipated.
Figure 4. OPEC production figures through Oct 13, 2013 as reported by others to OPEC (OPEC MOMR )
This means, unfortunately, that if the world was anticipating that the roughly 4 mbd increase in global demand by 2017 would be met largely by increased oil production from Iraq then they are likely to be sadly disappointed. Enjoy the lower gas prices while you may.
Figure 1. Relative fuel costs ($/gal) in different locations around the world. (BBC Calculator)
The orange line in figure 1 shows what I paid, and the darker grey horizontal line the regional cost here in the MidWest.
The EIA have noted in last week’s TWIP that the national price is as low as it has been since the beginning of 2011.
Figure 2. Average US retail prices for gasoline (EIA).
The EIA continues to describe the causes of these relatively low prices:
Lower global crude oil prices, high profitability for diesel fuel that has been encouraging refiners to increase throughput, high inventories, and the switch to less-costly winter grades of gasoline are among the factors currently driving gasoline prices.The OPEC Monthly Oil Market Report (MOMR) reports that global oil prices have fallen $2.04 a barrel (to $106.69) – the first decline in five months, as stocks increase and the Northern Hemisphere moves into winter. The estimate for global demand growth this year remains at 0.9 mbd, with the growth for next year anticipated to be at 1.04 mbd. This steady growth in global demand of a million barrels a day keeps raising the question as to where the increase is likely to come from. This is particularly germane given the disturbed conditions in a number of the MENA countries that provide a significant amount of baseline production, as well as anticipated increases.
The problems in Iraq, for example, have now reached the point that the Turkish government is directly working with the Kurds in Northern Iraq, to develop the oil in the Kurdish northern part of Iraq. This comes at a time that Iraq has been negotiating with the different major oil companies that had contracted to help Iraq reach an overall production target of 12 mbd by 2017. There have been considerable doubts cast on that original estimate, with the IEA producing a report, reviewed in an earlier post that concluded that the country would be lucky to achieve a production goal of 6 mbd by 2020, with an out year estimate that the country would be able to reach 8.3 mbd only by 2035.
Recognizing some of the difficulties in gearing up oil production at the different oilfields around Iraq (some of which were discussed in another post last June) production targets for 2017 had already been scaled back to a goal of 9 mbd by 2017, a drop of 25%. Now there has been discussion between Iraq and its partners for the various fields to drop those target values further, despite the large scale of the reserves that are considered available.
Figure 3. Oil reserves by field (Financial Times)
Exxon Mobil had 60% of the stake in the West Qurna oil field, but after it had started to work with the Kurds independently of Baghdad it found that relations with the Central Government rather chilled. Exxon Mobil has thus sold 25% of their stake to Petro China, and 10% to Pertamina of Indonesia, bringing the EM stake down to 25%. The current discussions between the companies and the Iraqi government are aimed at reducing the production target of the field by around 1 mbd..
Oil has just started to be produced at West Qurna Two, but the initial target is to have commercial production by the end of the year has suffered from local disruptions and the initial goal to reach a production of 400 kbd by the end of 2014 is now also in doubt. Commercial production is now not estimated to begin until perhaps the end of the first quarter of 2014. Initially the field was to be producing 1.9 mbd by 2017. That goal had been lowered to 1.2 mbd at the end of 2012. How the current disruptions will play into that target is difficult to estimate yet, but a year ago the parties were assuming that production would have already reached 150 kbd.
Earlier this year ENI had agreed with the Ministry of Oil to lower the target peak production from the Zubair field from 1.2 mbd to 850 kbd with that goal to be reached in 2016.
Discussions are not yet complete on new target production to be achieved from the Majnoon field. Shell has just announced the start of production from the field with the intent of raising production to over 175 kbd by the end of the year. However the long term target of raising production to 1.8 mbd is now in question. Shell is reportedly suggesting that the 2017 target be lowered to 1 mbd.
Similarly over at the Rumaila field BP is in discussion over long-term production, although earlier last month Schlumberger stopped work at the field because of local disturbances. With the field producing 1.4 mbd the disturbance was short-lived and is not reported to have affected current production, though it is indicative of tensions within the country. Current discussions are aimed at lowering the 2017 target production by around 800 kbd.
When these cuts are combined the total reduction is around 3.65 mbd, taking 2017 production down to 5.35 mbd, which is below the earlier best case scenario envisaged by the IEA.
OPEC notes that, after reaching a peak recent production of 3.194 mbd in August, production has fallen back below 3 mbd in September and October, and with Saudi Arabia also cutting back below 10 mbd in October the Organization is lowering production to meet the reduced winter demand, albeit the reduction from Iraq might not have been anticipated.
Figure 4. OPEC production figures through Oct 13, 2013 as reported by others to OPEC (OPEC MOMR )
This means, unfortunately, that if the world was anticipating that the roughly 4 mbd increase in global demand by 2017 would be met largely by increased oil production from Iraq then they are likely to be sadly disappointed. Enjoy the lower gas prices while you may.
Read more!
Labels:
crude oil production,
gas prices,
Iraq,
Kurds,
Majnoon,
OPEC,
Rumaila,
Turkey,
West Qurna,
Zubair
Monday, October 7, 2013
Tech Talk - complacency does not see the slow erosion of supply
There has been some talk this week over the volumes of oil and natural gas that is being produced in America, with the WSJ, for example, noting that the US is on track to surpass the volumes produced by Russia. Given that Russia is the leading producer of crude oil at the moment, in August OPEC noted that their production was running at 10.51 mbd, in which month they noted that Saudi Arabia was producing 9.96 mbd. OPEC carefully give two numbers for US oil production, total production is given, for August, as 10.88 mbd, but of this only around 7.2 mbd is crude oil. (While the 9.96 mbd of Saudi production is their crude output, and they also produce some NGL’s from their gas production, as well as seeing some refineries gains as their processing capacity increases). However the WSJ notes that the grand total for the US also contains oil, natural gas and other related fuels to reach the 22 mbdoe, relative to the 21.8 mbdoe that Russia is estimated to be producing.
While the overall impression that is being bandied about, that the US will become energy independent, has been shot down more than enough times (see for example Chris Nelder, last year) there remains, however, a broad complacency that, with increasing production from tight rock, in both oil and natural gas, there is no reason to have concern over future supplies.
If one looks at the make-up of the US supply of energy, natural gas has been steadily increasing its share, as has crude oil, to the cost of the coal market.
Composition of the US energy supply sources, supply shown in quadrillion Btu’s (EIA )
The break-out for June gives more explicit figures:
Figure 2. US Energy supply by Source for June, 2013.
The gap between supply and demand for petroleum products (particularly for transportation) can then be assessed by looking at the consumption side of the equation.
Figure 3. US energy consumption by sector (in quads, EIA )
The bull stirring in our China shop (pottery variety) continues to be the levels of petroleum that we need, and that is unlikely to decline all that much in the intermediate term.
The problem that the world faces is that the balance between available supply of crude oil and the demands for it now lie within very narrow range of production. It is still not that much more of a concern that additional oil this month comes from the US, rather than the Kingdom of Saudi Arabia (KSA) since, give or take a few weeks, supplies can still be purchased from different sources and rapidly shipped by tanker to where it is needed. But if the US were to be asked to meet an additional production need of 1 mbd over existing supply, because of even a short-term failure of supply from another country, it would not be able to meet that demand. (Short, that is, of draining the strategic supply).
Most of the other countries in the world are in a similar predicament. And that includes Russia. Russia gets more than half of its budget from oil and gas revenues, and with their economy flattening out it needs more revenue. It would help considerably if that help came in increasing volumes of oil and gas for export. But the remaining oil and gas deposits are being found in more remote parts of the country, where the expense of not only drilling the wells, but also of getting the product to market, requires a very large capital and time investment. Thus, while it would be nice if they could, they can’t be expected to meet an upsurge in external demand by turning the odd tap on an oilfield to produce additional supply.
And if one goes around the world, as I have been noting recently, outside of the KSA, there is virtually no-one else who can relatively rapidly respond to bring the global market into balance. But even the KSA capabilities to meet that demand are limited. I would suspect that they would get uncomfortable if they had to produce over 10 mbd for any length of time.
And this is where the kicker in the story lies, because, if that is the case, and conflicts around the globe continue to nibble away at the production capabilities in places such as Sudan, Iraq, Libya and their neighbors, then the additional global reserve between available supply and demand is going to increasingly tighten. It is a relatively imperceptible change every month. A little less oil flows down the Alaskan pipeline (439,686 bd in August against the average ytd of 528,572 bd); South Sudan is running about 100 kbd behind the figures for January 2012; Libya continues to suffer from the actions of the militia that control two of their oilfields to the point that production is now around 1 mbd below normal production for the country. There are some indications that the situation is now improving, with flows returning to around 700 kbd but this is still only half of the original volumes. And while the problem is political, rather than technical, the optimism of the Libyan oil minister who projects a return to production levels of 1.6 mbd is perhaps difficult to justify realistically.
Figure 4. Recent changes in Libyan oil production (WSJ )
Libya is, perhaps, with Iran, an exemplar of the nations with the potential to produce more, but who are constrained by immediate political problems. Iraq, who might otherwise also be in the group, is challenged also to develop the fields that are required for it to bring in the additional volumes of oil to the world market.
If these countries remain at their current levels of production, and there is little to indicate any positive change in the near term, then the narrow band over which KSA production fluctuates to keep the balance may not be enough for much longer.
Complacency that there is currently enough oil and natural gas to go around, at current levels of price, lets the market focus on other, more immediately pressing issues. But the slow erosion of the remaining global production surplus continues, and accumulates, and the time when this becomes evident may only be when that reserve no longer exists. And that may not be nearly as far into the future as most seem to expect.
While the overall impression that is being bandied about, that the US will become energy independent, has been shot down more than enough times (see for example Chris Nelder, last year) there remains, however, a broad complacency that, with increasing production from tight rock, in both oil and natural gas, there is no reason to have concern over future supplies.
If one looks at the make-up of the US supply of energy, natural gas has been steadily increasing its share, as has crude oil, to the cost of the coal market.
Composition of the US energy supply sources, supply shown in quadrillion Btu’s (EIA )
The break-out for June gives more explicit figures:
Figure 2. US Energy supply by Source for June, 2013.
The gap between supply and demand for petroleum products (particularly for transportation) can then be assessed by looking at the consumption side of the equation.
Figure 3. US energy consumption by sector (in quads, EIA )
The bull stirring in our China shop (pottery variety) continues to be the levels of petroleum that we need, and that is unlikely to decline all that much in the intermediate term.
The problem that the world faces is that the balance between available supply of crude oil and the demands for it now lie within very narrow range of production. It is still not that much more of a concern that additional oil this month comes from the US, rather than the Kingdom of Saudi Arabia (KSA) since, give or take a few weeks, supplies can still be purchased from different sources and rapidly shipped by tanker to where it is needed. But if the US were to be asked to meet an additional production need of 1 mbd over existing supply, because of even a short-term failure of supply from another country, it would not be able to meet that demand. (Short, that is, of draining the strategic supply).
Most of the other countries in the world are in a similar predicament. And that includes Russia. Russia gets more than half of its budget from oil and gas revenues, and with their economy flattening out it needs more revenue. It would help considerably if that help came in increasing volumes of oil and gas for export. But the remaining oil and gas deposits are being found in more remote parts of the country, where the expense of not only drilling the wells, but also of getting the product to market, requires a very large capital and time investment. Thus, while it would be nice if they could, they can’t be expected to meet an upsurge in external demand by turning the odd tap on an oilfield to produce additional supply.
And if one goes around the world, as I have been noting recently, outside of the KSA, there is virtually no-one else who can relatively rapidly respond to bring the global market into balance. But even the KSA capabilities to meet that demand are limited. I would suspect that they would get uncomfortable if they had to produce over 10 mbd for any length of time.
And this is where the kicker in the story lies, because, if that is the case, and conflicts around the globe continue to nibble away at the production capabilities in places such as Sudan, Iraq, Libya and their neighbors, then the additional global reserve between available supply and demand is going to increasingly tighten. It is a relatively imperceptible change every month. A little less oil flows down the Alaskan pipeline (439,686 bd in August against the average ytd of 528,572 bd); South Sudan is running about 100 kbd behind the figures for January 2012; Libya continues to suffer from the actions of the militia that control two of their oilfields to the point that production is now around 1 mbd below normal production for the country. There are some indications that the situation is now improving, with flows returning to around 700 kbd but this is still only half of the original volumes. And while the problem is political, rather than technical, the optimism of the Libyan oil minister who projects a return to production levels of 1.6 mbd is perhaps difficult to justify realistically.
Figure 4. Recent changes in Libyan oil production (WSJ )
Libya is, perhaps, with Iran, an exemplar of the nations with the potential to produce more, but who are constrained by immediate political problems. Iraq, who might otherwise also be in the group, is challenged also to develop the fields that are required for it to bring in the additional volumes of oil to the world market.
If these countries remain at their current levels of production, and there is little to indicate any positive change in the near term, then the narrow band over which KSA production fluctuates to keep the balance may not be enough for much longer.
Complacency that there is currently enough oil and natural gas to go around, at current levels of price, lets the market focus on other, more immediately pressing issues. But the slow erosion of the remaining global production surplus continues, and accumulates, and the time when this becomes evident may only be when that reserve no longer exists. And that may not be nearly as far into the future as most seem to expect.
Read more!
Labels:
Alaska pipeline,
crude oil,
Iran,
Iraq,
KSA,
Libya,
Russia,
South Sudan,
US energy
Sunday, September 29, 2013
Tech Talk - Iran and a slight cough toward CNN
There has been considerable comment this week over the telephone call between President Obama and the President Rouhani of Iran. Certainly the election of a new President in Iran gives the opportunity for a fresh start, particularly given the belligerent attitudes of his predecessor. However the cynical side of me does wonder if there is more driving this than simply the change of personalities.
There are two points that need to be considered, as a possible new relationship between the two countries might slowly coalesce out of the mists of diplomatic effort. Firstly the major driver seen in moving Iran toward a more positive position is said to be the increasing bite that sanctions, and particularly oil sanctions, are having on their economy. As sanctions have tightened, so Iranian oil production has fallen, with reports suggesting that oil exports have fallen from 2.2 mbd to May’s value of 0.7 mbd. The reduction in income that this has had on the Iranian economy is significant, with the currency officially devalued to half, though the effect has been more of an 80% fall from peak, as inflation has reached 42%.
Easing sanctions to allow more oil flow would significantly improve the situation, although there is concern, expressed for example at CNN, that the increase in oil flow would weaken the positions of the Kingdom of Saudi Arabia and Iraq. They suggest that the advent of Iranian oil (presuming that they can bring 1.5 mbd to the market relatively quickly) is foreseen as having a potential impact on the United States in that it may, at least transiently, produce a glut in the market. That would drive down prices, until such time as KSA could drop production and bring the supply and demand back into balance, raising prices back to around $100.
In a peaceful world such a scenario might have some viability, but consider what is really happening in the world of global supply. Instead of the KSA moving toward a supply of 12.5 mbd (which was only a capacity number in the first place) they have backed this down to 12 mbd and have talked recently as lowering that number further as they hire more and more rigs to help sustain existing production at just under 10 mbd. Iraq, which was promising to rapidly increase production toward a target of 11 mbd, is instead considered by the IEA likely to reach no more than 6 mbd by 2020. Further with the ongoing increase in violence in the country being able to sustain current production at around 3 mbd and increase it beyond 3.5 mbd as the Majnoon field comes on line. However Shell’s target for the field is already below initial estimates for this year, and it is discussing lowering the 2017 target from 1.8 mbd to 1.0 mbd. There has recently been an outbreak of violence in Kurdistan, which might portend that even in this relatively stable part of the country oil production and security is becoming a greater target.
These events suggest that future increases in production from around the region are not as assured as one might hope. At the same time, while there are those who continue to expect the United States to become oil-independent in the next few years, the reality is somewhat different, and further increases in production much above current figures become more difficult to justify. If Russia, similarly, is unlikely to increase production – which it is not – then the questions that should be asked are rather where is the world going to get the additional 1 mbd that it requires every year to balance increasing demand against supply.
Over the course of this year Saudi Arabia has had to increase production from 9.1 to 9.96 mbd to keep supply in balance, and prices stable. At the same time production from Libya, which has run at around 1.6 mbd had fallen to 150 kbd at the beginning of this month. Hopes that this could be increased back up to 700 kbd rely on tribal militias that control strategic parts of the country, and their long term co-operation is dubious, while the fields and pipelines in the east remain shut down. It seems reasonable to anticipate that there will be at least a million barrels a day of Libyan production held off the market for some time.
If one goes around the world one sees that Brazilian promises of production increase are behind schedule, as are promises of production increases from countries such as Veneuela. And suddenly one is left with not much in the way of places left to balance off the current declines in supply and increases in demand.
At this point that 1.5 mbd of potential supply from Iran starts to look a little more promising as an answer. It might allow KSA to ease back on production levels that might be starting to impose a little strain on their infrastructure. It would help to provide balance if production increases around the world fail to show on time. One should recognize that negotiations to bring Iran back into the fold are going to take at least a year or two before it is realistic to anticipate full return to supply, but even the easing of sanctions a little might cause the flow to China, India and Asia to increase to meet the burgeoning demands that they have, and oil is still to some degree fungible.
But in that regard, Iran has also just recently reached 100% output from the first of the nuclear power stations at Bushehr and is about to start construction of the second unit. Nuclear fuel will be provided by Russia, and spent fuel returned to Russia. It is a 1,000-megawatt unit, and since the unit was built under supervision by the International Atomic Energy Agency it is not subject to sanctions.
Figure 1. Bushehr Nuclear Plant
If the protocols that worked to make this happen can be expanded, then it is possible that, though negotiation, the tension in the region can be eased. This could well have benefits all around, most particularly for ensuring that, for at least a sadly few more years, there will be enough oil on the market to meet demand at a reasonable price.
Figure 2. Location of the Bushehr Plant
There are two points that need to be considered, as a possible new relationship between the two countries might slowly coalesce out of the mists of diplomatic effort. Firstly the major driver seen in moving Iran toward a more positive position is said to be the increasing bite that sanctions, and particularly oil sanctions, are having on their economy. As sanctions have tightened, so Iranian oil production has fallen, with reports suggesting that oil exports have fallen from 2.2 mbd to May’s value of 0.7 mbd. The reduction in income that this has had on the Iranian economy is significant, with the currency officially devalued to half, though the effect has been more of an 80% fall from peak, as inflation has reached 42%.
Easing sanctions to allow more oil flow would significantly improve the situation, although there is concern, expressed for example at CNN, that the increase in oil flow would weaken the positions of the Kingdom of Saudi Arabia and Iraq. They suggest that the advent of Iranian oil (presuming that they can bring 1.5 mbd to the market relatively quickly) is foreseen as having a potential impact on the United States in that it may, at least transiently, produce a glut in the market. That would drive down prices, until such time as KSA could drop production and bring the supply and demand back into balance, raising prices back to around $100.
In a peaceful world such a scenario might have some viability, but consider what is really happening in the world of global supply. Instead of the KSA moving toward a supply of 12.5 mbd (which was only a capacity number in the first place) they have backed this down to 12 mbd and have talked recently as lowering that number further as they hire more and more rigs to help sustain existing production at just under 10 mbd. Iraq, which was promising to rapidly increase production toward a target of 11 mbd, is instead considered by the IEA likely to reach no more than 6 mbd by 2020. Further with the ongoing increase in violence in the country being able to sustain current production at around 3 mbd and increase it beyond 3.5 mbd as the Majnoon field comes on line. However Shell’s target for the field is already below initial estimates for this year, and it is discussing lowering the 2017 target from 1.8 mbd to 1.0 mbd. There has recently been an outbreak of violence in Kurdistan, which might portend that even in this relatively stable part of the country oil production and security is becoming a greater target.
These events suggest that future increases in production from around the region are not as assured as one might hope. At the same time, while there are those who continue to expect the United States to become oil-independent in the next few years, the reality is somewhat different, and further increases in production much above current figures become more difficult to justify. If Russia, similarly, is unlikely to increase production – which it is not – then the questions that should be asked are rather where is the world going to get the additional 1 mbd that it requires every year to balance increasing demand against supply.
Over the course of this year Saudi Arabia has had to increase production from 9.1 to 9.96 mbd to keep supply in balance, and prices stable. At the same time production from Libya, which has run at around 1.6 mbd had fallen to 150 kbd at the beginning of this month. Hopes that this could be increased back up to 700 kbd rely on tribal militias that control strategic parts of the country, and their long term co-operation is dubious, while the fields and pipelines in the east remain shut down. It seems reasonable to anticipate that there will be at least a million barrels a day of Libyan production held off the market for some time.
If one goes around the world one sees that Brazilian promises of production increase are behind schedule, as are promises of production increases from countries such as Veneuela. And suddenly one is left with not much in the way of places left to balance off the current declines in supply and increases in demand.
At this point that 1.5 mbd of potential supply from Iran starts to look a little more promising as an answer. It might allow KSA to ease back on production levels that might be starting to impose a little strain on their infrastructure. It would help to provide balance if production increases around the world fail to show on time. One should recognize that negotiations to bring Iran back into the fold are going to take at least a year or two before it is realistic to anticipate full return to supply, but even the easing of sanctions a little might cause the flow to China, India and Asia to increase to meet the burgeoning demands that they have, and oil is still to some degree fungible.
But in that regard, Iran has also just recently reached 100% output from the first of the nuclear power stations at Bushehr and is about to start construction of the second unit. Nuclear fuel will be provided by Russia, and spent fuel returned to Russia. It is a 1,000-megawatt unit, and since the unit was built under supervision by the International Atomic Energy Agency it is not subject to sanctions.
Figure 1. Bushehr Nuclear Plant
If the protocols that worked to make this happen can be expanded, then it is possible that, though negotiation, the tension in the region can be eased. This could well have benefits all around, most particularly for ensuring that, for at least a sadly few more years, there will be enough oil on the market to meet demand at a reasonable price.
Figure 2. Location of the Bushehr Plant
Read more!
Labels:
Brazil,
Bushehr nuclear plant,
China,
CNN,
crude oil production,
Iran,
Iraq,
KSA,
Libya,
Majnoon,
oil demand,
Russia
Thursday, June 20, 2013
OGPSS - Insecurity in the Middle East
The continuing conflict in Syria, and the slow spread of violence in the region around it, continue to make it difficult to make accurate predictions about the future of oil exports from the region. Within Syria itself production had fallen into decline about ten years ago, before the current struggle began. The precipitate drop over the last two years has, however, been much more dramatic. As Energy Export Databrowser noted from the BP statistic review, production fell by 49% last year.
Figure 1. Syrian oil production showing the recent fall in volume. (Energy Export Databrowser ).
As with most oil-producing nations oil consumption had, on the other hand, been steadily rising with net exports (some is exported as crude and re-imported as refined product) falling to around 100 kbd. The conflict has, however, also reduced internal consumption at similar rates earlier in the conflict.
Figure 2. Syrian production and consumption until 2011. (EIA )
At the same time that Syrian exports have sensibly disappeared, the exports from Iran have continued to fall. Data through the end of last year shows that sanctions continued to bite, with exports falling 31% last year.
Figure 3. Oil production, consumption and exports for Iran (Energy Export Databrowser)
Much of the oil from Iran goes to China, India and Turkey. In May 2013 the total exports are reported to have fallen to 700 kbd although individual monthly numbers fluctuate given the complexity of now getting oil into the hands of customers. (H/t Gail - that report may only cover Chinese imports, since Bloomberg reports a different set of numbers, and an IEA estimate that Iran is averaging 1 mbd of exports this year.) India is hoping that the change in the Iranian Presidency will lead to an easing of sanctions. In the interim, the exemptions that China, India and Turkey are receiving to some of the sanctions have just been extended another six months. Part of this comes from the cuts those countries have already made. India, for example is now down to around 117 kbd around half that of a year ago.
Oil imports into China are reported to have increased, perhaps because the Chinese have just agreed to buy a number of Chinese drilling rigs. Total exports are projected to fall to 1.3 mbd over the current Iranian fiscal year (which started in March). If Iran is having to store more of its oil in off-shore tankers, this may explain the fall in regional tanker availability over the past month.
In a recent post I discussed my concern over the likelihood of Iraq being able to achieve the increased volumes of production within the time frame that their Central Government has suggested. However, as Leanan caught recently, Kurdish Iraq is moving more and more toward independent action in regards to their oil. From the Turkish side a pipeline will be allowed, that can go to the border, but not cross it. Mysteriously it will likely then fill, over time, with a flow of 1 mbd. Turkey is working with BP to develop the resources of Kurdish Iraq. In the interim Turkish demand has stabilized to a greater degree than it has in its southern neighbors.
Figure 4. Oil imports and consumption in Turkey (Energy Export Databrowser)
To a degree the instability is feeding off itself. Egypt continues to have problems in ensuring an adequate supply of fuel, and while Iraq and Libya have agreed to help, they prefer cash up front for the delivery, and that is proving to be a bone of contention. The country has reached the point where domestic production can no longer keep up with consumer demand, and these imports are going to become more critical to the budget, and, as a follow-on, national stability.
Figure 5. Change in oil consumption and the need for more imports for Egypt (Energy Export Databrowser)
The hope is that a pipeline can be built from Iraq, through Jordan, but that requires that a mutually acceptable line of credit be established, and that appears to be a problem. Egypt has the same soft-credit deal with Libya for a supply of a million barrels a month. The price, however, will be at that of the world market.
Unfortunately as the level of violence continues to grow one starts to get into an almost inevitable snowball effect, and there is a consequent negative impact on much industry, likely including that of oil production. The most likely consequence will be a further fall in the regional export of oil, which has a follow-on consequence in that the customers who have lost this supply (Japan has given up all Iranian oil for example) must then go onto the world market to find an alternate source of supply.
As those sources become even scarcer than they are already, marginal amounts of oil become more critical to maintaining a global balance. But such supplies don’t become available at the drop of a hat.
It seems to be a drum that I beat perhaps a bit often, but it is a message that bears repeating. Without significant and ongoing investment in the more difficult regions of the world, funds to identify the necessary availability of resource, and then to drill, in a timely manner, to prove the resource and start the process of turning it into a reserve, the oil balance cannot be sustained at a viable and acceptable price. It does not matter how glowing a set of reports are put out about how we can all relax because the world has plenty of oil in shale.
The largest of those resource sites is in Russia, where there may be as much as 75 billion barrels. But two things should be remembered. The first is that peak oil is reached, not when we run out of oil, but when we start producing less each year than in the previous. And the second is that getting much of the oil in the shale into the proven reserve category is going to take a fair amount of time, after which production rates, going from the results seen, for example, in the Bakken will decline at such a rate that a continued and expansive program of expensive drilling will be required to sustain production. And all this time the flow of oil from existing reservoirs will continue to fall.
Figure 6. A pretty wall hanging . (EIA)
Editorial Note: Because of one of those delightful family events that occur from time to time, this series will be on hiatus for a couple of weeks, since we will be traveling, when I would otherwise be writing.
Figure 1. Syrian oil production showing the recent fall in volume. (Energy Export Databrowser ).
As with most oil-producing nations oil consumption had, on the other hand, been steadily rising with net exports (some is exported as crude and re-imported as refined product) falling to around 100 kbd. The conflict has, however, also reduced internal consumption at similar rates earlier in the conflict.
Figure 2. Syrian production and consumption until 2011. (EIA )
At the same time that Syrian exports have sensibly disappeared, the exports from Iran have continued to fall. Data through the end of last year shows that sanctions continued to bite, with exports falling 31% last year.
Figure 3. Oil production, consumption and exports for Iran (Energy Export Databrowser)
Much of the oil from Iran goes to China, India and Turkey. In May 2013 the total exports are reported to have fallen to 700 kbd although individual monthly numbers fluctuate given the complexity of now getting oil into the hands of customers. (H/t Gail - that report may only cover Chinese imports, since Bloomberg reports a different set of numbers, and an IEA estimate that Iran is averaging 1 mbd of exports this year.) India is hoping that the change in the Iranian Presidency will lead to an easing of sanctions. In the interim, the exemptions that China, India and Turkey are receiving to some of the sanctions have just been extended another six months. Part of this comes from the cuts those countries have already made. India, for example is now down to around 117 kbd around half that of a year ago.
Oil imports into China are reported to have increased, perhaps because the Chinese have just agreed to buy a number of Chinese drilling rigs. Total exports are projected to fall to 1.3 mbd over the current Iranian fiscal year (which started in March). If Iran is having to store more of its oil in off-shore tankers, this may explain the fall in regional tanker availability over the past month.
In a recent post I discussed my concern over the likelihood of Iraq being able to achieve the increased volumes of production within the time frame that their Central Government has suggested. However, as Leanan caught recently, Kurdish Iraq is moving more and more toward independent action in regards to their oil. From the Turkish side a pipeline will be allowed, that can go to the border, but not cross it. Mysteriously it will likely then fill, over time, with a flow of 1 mbd. Turkey is working with BP to develop the resources of Kurdish Iraq. In the interim Turkish demand has stabilized to a greater degree than it has in its southern neighbors.
Figure 4. Oil imports and consumption in Turkey (Energy Export Databrowser)
To a degree the instability is feeding off itself. Egypt continues to have problems in ensuring an adequate supply of fuel, and while Iraq and Libya have agreed to help, they prefer cash up front for the delivery, and that is proving to be a bone of contention. The country has reached the point where domestic production can no longer keep up with consumer demand, and these imports are going to become more critical to the budget, and, as a follow-on, national stability.
Figure 5. Change in oil consumption and the need for more imports for Egypt (Energy Export Databrowser)
The hope is that a pipeline can be built from Iraq, through Jordan, but that requires that a mutually acceptable line of credit be established, and that appears to be a problem. Egypt has the same soft-credit deal with Libya for a supply of a million barrels a month. The price, however, will be at that of the world market.
Unfortunately as the level of violence continues to grow one starts to get into an almost inevitable snowball effect, and there is a consequent negative impact on much industry, likely including that of oil production. The most likely consequence will be a further fall in the regional export of oil, which has a follow-on consequence in that the customers who have lost this supply (Japan has given up all Iranian oil for example) must then go onto the world market to find an alternate source of supply.
As those sources become even scarcer than they are already, marginal amounts of oil become more critical to maintaining a global balance. But such supplies don’t become available at the drop of a hat.
It seems to be a drum that I beat perhaps a bit often, but it is a message that bears repeating. Without significant and ongoing investment in the more difficult regions of the world, funds to identify the necessary availability of resource, and then to drill, in a timely manner, to prove the resource and start the process of turning it into a reserve, the oil balance cannot be sustained at a viable and acceptable price. It does not matter how glowing a set of reports are put out about how we can all relax because the world has plenty of oil in shale.
The largest of those resource sites is in Russia, where there may be as much as 75 billion barrels. But two things should be remembered. The first is that peak oil is reached, not when we run out of oil, but when we start producing less each year than in the previous. And the second is that getting much of the oil in the shale into the proven reserve category is going to take a fair amount of time, after which production rates, going from the results seen, for example, in the Bakken will decline at such a rate that a continued and expansive program of expensive drilling will be required to sustain production. And all this time the flow of oil from existing reservoirs will continue to fall.
Figure 6. A pretty wall hanging . (EIA)
Editorial Note: Because of one of those delightful family events that occur from time to time, this series will be on hiatus for a couple of weeks, since we will be traveling, when I would otherwise be writing.
Read more!
Labels:
crude oil production,
Egypt,
Iran,
Iraq,
Kurdistan,
Libya,
Middle East,
oil consumption,
Syria,
Turkey
Subscribe to:
Posts (Atom)