Showing posts with label renewable energy. Show all posts

Sunday, June 3, 2012

Rising Energy Prices and their impact

As the United States continues through the interminable process that will end with the national elections in November, the continued poor state of the economy is playing an increasing part in the debate over the likely outcome. What seems to have slipped from the discussion, however, is the contribution that energy costs are making in their impact on the different economies around the world including that of the United States. That awareness is becoming more evident in the UK, particularly in the debate over Scottish Independence. The recent Uswitch report notes:
Energy bills have more than doubled in the last 8 years – if this trend continues bills could reach £1,582 a year by 2015 and £2,766 by 2018. But almost six in ten people (59%) say that energy will become unaffordable in the UK if the average bill hits £1,500 a year, with the average household bill today already £1,252 a year.
Yet the increasing reliance on “green energies” in the United Kingdom, and particularly Scotland, are already recognized as leading to major current and future cost increases, with consequent impacts on the strength of the economies that they support.
Figure 1. Relative energy sources for Scotland and the UK in 2010 (Scottish Government)

 The growth of renewable energy in Scotland has been remarkable over the past decade, and has received consistent support to grow beyond the current levels. The major growth has been in the use of wind turbines, which – as I saw in a recent trip to the UK, are now more prevalent than ever. (And, more encouragingly, were also turning in greater proportion than I had seen in the past).

Figure 2. Installed capacity for renewable energy in Scotland through 2010 (Scottish Government)

  Current plans and projections would increase capacity from the roughly 4.4 GW shown above to a total of 28.8 GW being possible with pipeline and projected other projects. And in 2010 Scottish turbines produced more power from turbines than from hydro power for the first time.


Figure 3. Scottish electricity from renewables by source (Scottish Government) 

 Of these, however, only 3.3 GW have progressed beyond the planning stage. Yet, given that renewable sources have supplied nearly 20% of the need at present, this suggests a much greater role in the future, with less need for more conventional fossil fuels. Currently Scotland gets most (around 75%) of its electricity from five power stations, there are the two coal-fired power stations at Longannet and Cockenzie, one gas-fired station at Peterhead, and two nuclear power stations at Torness and Hunterston. These stations will be phased out as the transition to greater reliance on “wind and wave” with a target of 16 GW to be contributed in 2020.

Figure 4. Path to a Scottish Renewable Energy Future (Scottish Government ) 
 (A. Deployment projection based upon an extrapolation of the annual deployment levels experienced in 2007-08. 
B. Deployment projection based upon an extrapolation of the annual deployment levels experienced between 2009 and the start of 2011. 
C. Deployment projection, based on Scenario B above, adjusted for the improvements in the planning/consent system that were introduced in recent years but which have not yet impacted upon actual deployment rates. 
D. The 100% target line is a straight line extrapolation between current installed capacity and the estimated levels of capacity required to achieve 100% of gross consumption from renewables in 2020. 

This hypothetical line is incorporated to identify and acknowledge the scale of the challenge. In reality, it is recognised that deployment will not follow a straight line and would be expected to accelerate towards the latter part of the decade, particularly given the potential magnitude of offshore wind deployment.) 

 The political beliefs of the Scottish National Party (SNP) now in power, which include a desire to reject nuclear power and move to greener sources of electricity is, however, bumping up against the realities of cost and practicality. The Institution of Mechanical Engineers in the UK has released a report that concluded:
The Institution’s findings suggest that the original renewable energy target split for Scotland of 50% electricity, 11% heat and 11% energy for transport, making the overall 20%, and subsequent revision of the electricity generation target to 100%, did not appear to be supported by a rigorous engineering analysis of what is physically required to achieve a successful outcome in the timescale available. 
During the research for this report, First Minister Alex Salmond announced that the Scottish Government had increased the overall percentage target for energy from renewable sources to 30% by 2020. In light of this report’s analysis, this aspirational target appears to represent an ambition that cannot be justified from an engineering perspective.
The Scottish Government has responded, in part, by emphasizing the goal of reducing energy consumption in the country by 12% by the year 2020. Yet significantly raising energy costs and demanding that society reduce demand are not obvious ways of immediately stimulating economies to return to national prosperity. About 750 million British pounds (BP) ($480 million) worth of power came on line in 2011, but the investment required to meet targets in the future will be much higher. The estimated cost for the next 17 GW of capacity is $70 billion (46 billion BP). The Scottish GNP runs around $225 billion (145 billion BP) and there is increasing question over the ability of the country to be able to attract the funding needed to achieve its targets. 

 Yet the concern that worries me more as these debates continue is that while an increasing reliance on renewable energy sources may well be politically promoted, the financial and technical ability to reach those goals is becoming increasingly unavailable. (See particularly the IME report). For, while the focus of the debate remains on that side of the supply, the construction of alternate power sources to meet the anticipated demand are not being properly addressed.

 In Scotland there is now talk of a new coal-fired power station at Grangemouth following the cancellation of a carbon capture and sequestration project at Longannet. The Cockenzie coal-fired plant will close next year, though there are hopes that it might be replaced with a natural gas-fired plant. But these things take time to permit and construct, and should the required pace of renewable sources falter, then the conservation of energy that the Scottish Government would like to see as a voluntary activity might come to be an involuntary need instead, with consequent significantly more severe impact on industry and the Scottish economy. 

 Why is this relevant to the American election? Well unfortunately, though at a slower pace, there seems to be a similar argument being made in the United States to speed up the phase-out of coal-fired power, as perhaps evidenced by the recent decision to close the Big Sandy coal-fired power plant in Kentucky, under EPA pressure. There is a presumption in discussions of the future energy costs for the country that cheap natural gas will be an easy replacement for coal. However, much of that future relies on the low prices of natural gas, and as Chesapeake are finding, just because there is a market, does not mean it is a profitable one. You can’t make up the difference between producing natural gas for $5 a thousand cu ft (kcf), and selling it at $2/kcf by increasing the volume that you sell, and thereby realize a profit. When all the dust settles it is likely there will be less natural gas on the market, at a greater price, but that is a different story. For now one can only be concerned that the failure to recognize that energy prices are playing their part in restraining national economies seems to have become a neglected part of the national discussion, which is a pity – both in Scotland and in the USA.

Read more!

Wednesday, June 15, 2011

Will Renewable Energy Rescue Us All - BP and the IPCC reviews

The people of the world are going to continue to use energy. The fundamental question that this future reality poses relates to the sources from which the energy will be produced. The vast majority of the current energy supply comes from fossil fuels, but, whether it is because of the belief that fossil fuels are going to be the cause of calamitous climate change, or because of the belief that viable production of fossil fuels cannot be sustained at increasing rate, there is a recognition that alternate and sustainable forms of energy are going to have to play an increasing role in the energy mix in that future. However the rate at which those energy supplies are brought into the mix, and the levels that they can achieve are subject to considerable discussion.

The 2011 BP Statistical Review of World Energy in recognizing this, added two new sets of information to their 2011 review of fuel use around the world. The first of these documents the amount of commercial electricity that comes from renewable sources, and the second covers the amount of biofuel that is produced each year. Looking at the amount of electricity generated, the greatest renewable source is currently hydro-electricity, for which BP reports:

Rising use of hydro-electricity around the World in million tons of oil equivalent (divide by 50 to get a rough measure of the equivalent in mb/d) (BP Statistical Review)

The report notes that the increase in the last year, at 5.3% this is twice the historical average, has come mainly through growth in the Asia Pacific region. Note also that this is for electricity generation, Biomass contributes more enery, but a lot is burned directly for heat.

NOTE THAT THIS POST HAS BEEN UPDATED

Other forms of electricity generation have also grown:

Growth in the supply of electricity from renewable sources in million tons of oil equivalent (BP Statistical Review)

The greatest growth has been in Europe, and the overall trend would appear encouraging. In terms of the liquid fuels that must be produced to replace petroleum products in transportation BP shows that ethanol is being most actively developed in the Americas, while in Europe the emphasis is on biodiesel. Combined the growth over the last decade is shown as follows:

Biofuel production in millions of tons of oil equivalent (again divide by 50 to turn this into a rough estimate in mbd). (BP Statistical Review)

To put these numbers into context, however, one needs to recognize how small a portion of the global supply that these supplies now meet. With a global demand getting close to 90 mbd, a biofuel supply that is just over 1 mbd is not currently making much impact, although if the growth rate of 13.8% in 2010, were to be sustained, it could start to have an impact in a few years.

If one looks at the global contribution to power, bearing in mind that the category of biomass includes everything from trees, through brush wood to dung requires some degree of husbandry to be sustainable, the distance that these technologies must grow before they are significant contributors can be realized.

Relative contribution of different energy sources to global power in 2008 (IPCC Special Report on Renewable Energy )

The BP review, while providing a widely referenced source of statistics about energy use at present, and in the past, does not cover future use, however. And the quantity of renewable energy that will be available plays a critical part in helping to plan for that future. It is thus of interest to note that the Intergovernmental Panel on Climate Change (IPCC) has just released a report on Renewable Energy. In the summary press release, the report is cited as showing how up to 77% of global energy could be achieved from renewable sources by 2050.

The report has already received some significant criticism but since it is useful to know how one can grow renewable energy to that level, that fast, I did follow up on one of the references. Steve McIntyre notes that it can be traced back initially to Chapter 10 of the report, and from there back to a paper that admits to the 77% only being achievable if nuclear power is shut down, no CCS power plants are built and there are drastic steps forward in the efficient use of energy. Since those are likely unrealistic I’m not going to chase after that. But what I do find interesting is where the IPCC anticipate that the growth will likely come from. And that can be found in this couple of charts, showing the progress to 2030, and then that achieved by 2050.

Anticipated growth in renewable energy sources to supplies in 2030 and 2050 (For comparative purposes the global electricity demand in 2008 is cited as 61 EJ/yrear). (IPCC Special Report on Renewable Energy)

The IPCC report notes that in order for any meaningful progress to be made there must be significant policy changes as well as moves to ensure the adequate levels of innovation will be achieved that are required to make the progress assumed. (Which is in my book assuming that one can legislate technology, which as we have seen with the cellulosic ethanol story is not necessarily so). But one should also be cautious about the speed of politicial change. There is a lesson, for example, that has just emerged from the UK.

Back in 2007 the Department of Energy and Climate Change (DECC) in the UK commissioned a study on the coming of peak oil that has just been released, and which may explain the complacency of the UK Government. That report noted that while the UK is less dependant on oil to fuel its economy than other OECD nations, the oil that it does use is difficult to replace since it fuels some 70% of national transportation. The report looked at various time frames for peak oil (pre-2010; 2010 to 2015; mid 2020’s; late 2030’s) and concluded that only the first two would pose a problem. By increasing production from the FSU countries and increasing investment in production to meet demand the report justified the medium and long term scenarios. (However at the same time the report saw price remaining around $60/bbl, which is unrealistic already). The conclusions included the following:
•While global reserves are plentiful, it is clear that existing fields are maturing, the rate of investment in new and existing production is being slowed down by bottlenecks, the economic downturn and financial crisis and that alternative technologies to oil will take a long time to develop and deploy at scale;
•The UK economy would be initially relatively robust to higher prices; however, if peak oil happens before 2015 there would be negative economic consequences for some of the main importers of UK goods and services resulting in a negative impact on the UK economy in the longer term. If the peak happens later, it would be possible to mitigate the impact through greater end-use efficiency and the production of sufficient quantities alternative liquid fuels.
•Given the uncertainties around the timing of peak oil and its implications for the UK, there are no obvious additional policies the UK government should pursue to minimise the likelihood of a 'peak oil' scenario and to be prepared to mitigate its impacts in addition to those already in place
.
In reviewing changes since the initial report, the summary notes that while not believing in a near term “peak” the authors do not preclude a risk of a supply crunch.

The Guardian article notes that the DECC minister is now starting to have a bit of a re-think. This is driven, apparently, by the rising concerns in industry about the growing signs that all in not as well in petroleum supply as the DECC report would have it. But the speed of bureaucratic change in thought means that it has taken four years to realize that there might be a problem. It doesn’t bode well for the adoption of forward thinking strategies. Unfortunately it doesn’t bode well for assuring that the world has enough energy for its needs either.

UPDATE: Bishop Hill has a post on the relatively incestuous relationship between those authoring the report, the trade associations for renewable energy in Europe and the UE management. Not that I am condoning that it any way, but it does give a measure of what may very well define the outer edges of what, if all buttons were pressed, might be achievable. However even the little that I have read and commented on shows that it is a hopelessly optimistic view of what can be achieved within the time frames assigned, and as a result Government which believes their predictions, and the populations that trust the Governments to take care of them, are going to be significantly dis-served.

Read more!

Friday, April 22, 2011

Drought, renewable energy, Texas, London and Florida

The Governor of Texas has asked the denizens of the state to pray for rain. The state has not had serious rain for months, and the drought conditions have turned severe.

The current drought conditions in Texas.

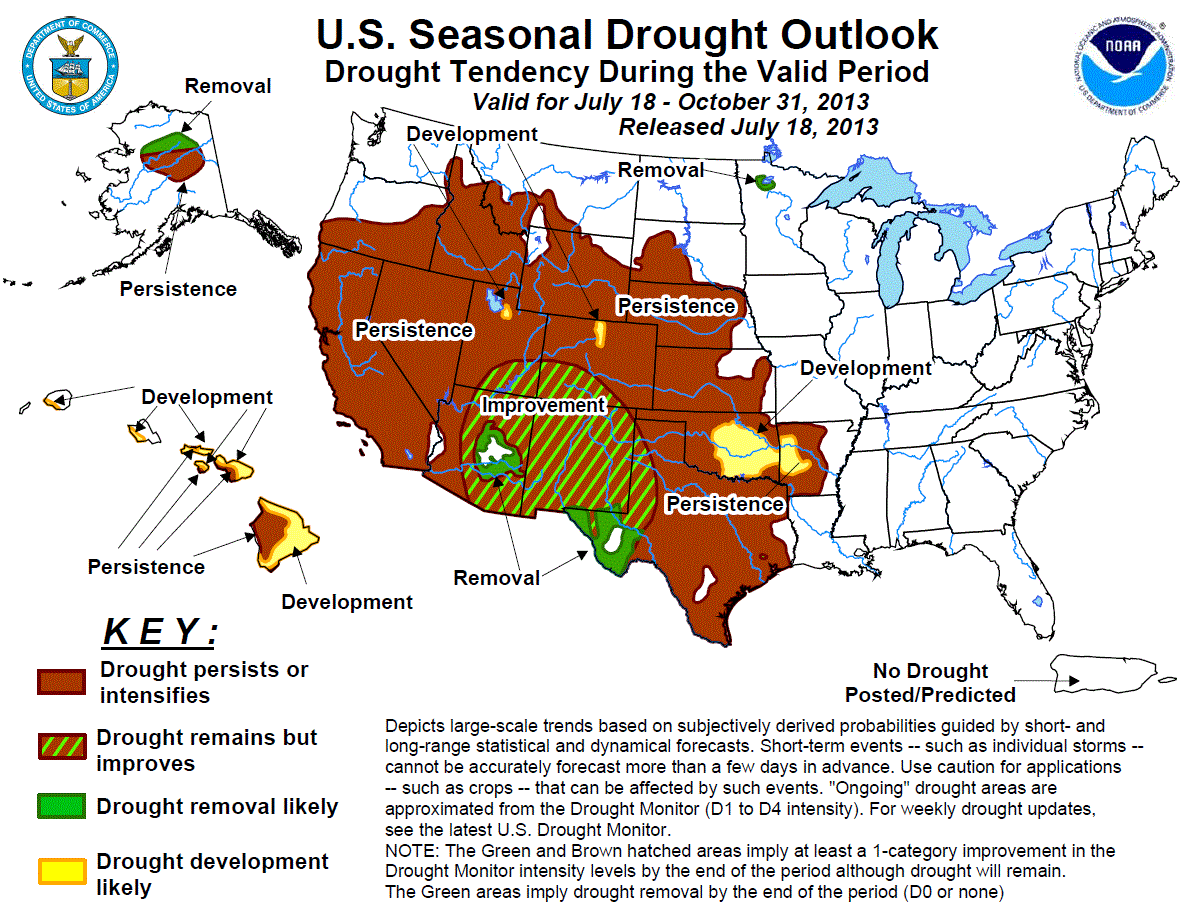
Conditions are not anticipated to get any better in the next few months. The recent predictions are that the conditions will persist in the area through July.

Predictions of the weather changes through July (NOAA )

Droughts around the world are one of the unfortunate consequences of changing weather, in much the same way as we have seen high snowfalls in other parts of the country this past winter. There will likely be cries about the underlying causes (with folks forgetting that droughts have occurred throughout history), but this post was started because of a potential event-changing occurrence.

This week Thames Water, which supplies 687 million gallons of water a day to the inhabitants of London and the immediate vicinity, was running its first water desalination plant. The region has faced droughts in the recent past as have other regions of the United Kingdom. Earlier solutions included building large water reservoirs, that at Kielder is the largest man-made reservoir in Europe. There is, however, only a certain limited amount of land that can be made available for this use, and so desalination proves an alternate way of supplying the increasing global demand for water.

In the United States droughts have threatened the viability of nuclear power stations, since the shortage of cooling water (as we recently learned again in Japan) is essential to safe plant operation. And therein lies one of the rubs to the situation. As the spokesman for Thames Water noted, the intent is not just to run the plant when there is a drought, since that is going to be too late. Rather at times of lower rainfall the plant (which can produce up to 150 million gallons a day) will pump clean water into the reservoirs, maintaining their integrity, and building up a reserve that will reduce the drought impact if it occurs. The plant was apparently completed last June at which time it was expected that it would just be used in times of drought. Within the last year that thinking has changed, and the plant is now running intermittently, partly to train operational staff, partly potentially also to help meet demand.
According to the Environment Agency, average water use is 148L per person per day in the UK and in the south-east of England it’s as high as 170L (far higher than the government target of 130L). Despite the popular perception of London as an overcast, rain-soaked city, its rainfall rate is, in fact, on a par with Rome, Dallas and Istanbul.

Schematic of the flow path through the desalination plant.

One question that I had relates to the amount of power that will be needed at Beckton. A calculation assuming that it takes 4 kWh to produce a cubic meter of fresh water, suggests that it will need a 21 MW plant. In 2009 the company CEO noted
The (20 MW) plant will be the first in the world to generate all its energy on-site, from renewable sources, including recycled cooking oil.
However the plant has been controversial, not least because although planning to use rapeseed oil, it could also burn palm oil, which is apparently cheaper. That is much more controversial. Planning permission for a second plant nearby at Southall, was refused in June 2010.

Biofuel powered stations in the UK, which includes that in the Tees Valley, where a plant burning 300,000 tons of recycled wood and specially grown wood from plantations, have had a somewhat mixed reception.

But to get back to the original idea of desalination, the largest plant in the United States is in Tampa with a maximum projected size of 35 million gallons/day, though it currently only produces some 25 million, sufficient for 10% of the region’s water needs. It went on line in 2008.
The plant uses about 44 million gallons per day (mgd) of seawater from a nearby power plant’s cooling system, which is pretreated with sand filters and a diatomaceous earth filtration system to remove particles. Reverse osmosis filters then separate 25 mgd of freshwater from the seawater. The unused concentrated seawater is diluted with up to 1.4 billion gallons of cooling water before it is discharged to the bay and that dilution is why environmental studies show no measurable salinity change in Tampa Bay related to plant production.
Which brings us back to Texas. In the latest report on desalination in the state, two possible developments are cited. There is a plan to install a 2.5 million gallon a day plant at Brownsville and a 1 million gallon a day facility on South Padre Island. Unfortunately the South Padre Island initiative failed in a bond election last year, and its future is considered doubtful. Meanwhile the Brownsville Public Utilities Board is considering combining a renewable energy source (shades of the UK) into the plant, in order to leverage funding, and possibly qualify for DOE funds.

But in the meantime, as the discussion continues, the drought gets worse. The discussions started with an initiative in 2002. As those in Texas may find out the hard way, waiting until the crisis is upon them makes it too late to construct the solution that might have helped. It appears that those in the UK and Florida were just a little more prescient. It might be noted that the initial planning for the Florida plant started in 1996.

Read more!

Thursday, March 31, 2011

President Obama's Blueprint for Energy, the world situation and the current TWIP

On Wednesday President Obama used a visit to Georgetown University to draw attention to a new Blueprint for a Secure Energy Future. The document provides that path through three mechanisms:

a) To develop and Secure America’s Energy Supplies by:
Expanding Safe and Responsible Domestic Oil and Gas Development and Production
Leading the World Toward Safer, Cleaner, and More Secure Energy Supplies

b) To Provide Consumers with Choices to Reduce Costs and Save Energy by:
Reducing Consumer Costs at the Pump with More Efficient Cars and Trucks
Cutting Energy Bills with More Efficient Homes and Buildings

c) Innovating Our Way to a Clean Energy Future by:
Harnessing America’s Clean Energy Potential
Winning the future through Clean Energy Research and Development
Leading by Example:
The Federal Government and Clean Energy.

The problem that I have had with the Administration’s Energy Policy since it first came to power is that it lacks an understanding of the time element in proposing answers. And let me put up a graph from the latest This Week in Petroleum to explain why I feel that this concern is now strengthened.

As I mentioned in my comment on Dr Saleri’s remarks that oil production bounced back after the revolution in Iraq, the TWIP has put up a plot showing how neither Iran, Iraq nor Venezuela have recovered the levels of oil production that existed in country before they had problems. Only Kuwait, after two years, was able to bounce back.

The drop in production from countries following conflict (EIA TWIP )

In all cases the flow of oil was disrupted for more than a year. Consider the current situation where, with supply and demand more closely now in balance, we have the risk of more than 2 mbd of oil disappearing from the world market for a couple of years. With a concomitant rise in demand of 1.4 mbd this year that means we need NOW to find ways of addressing the coming shortfall – not in 2020, but in 2011.

In that regard, how does the President’s new Blueprint stack up? Let’s go through the three different parts that I outlined above, in turn.

a) Developing and Securing America’s Energy Supplies.
The first part of this deals with increasing domestic oil and gas production, and the blueprint notes that the United States was importing 11 mbd when the Administration took office. President Obama, in introducing the plan, pledged that this volume will be cut be a third by 2020. One of the ways of doing this is to increase domestic production, and the blueprint contains this plot:


It looks a little more impressive than it is, because of the vertical scale, which in total is less than 1 mbd, and this makes the recovery of about 0.56 mbd look more significant than it is. Remember that the promise is that imports will fall by around 3.7 mbd and the gain in domestic production is tapering off in the plot above.

The most likely production gains will be achieved from the deep waters of the Gulf of Mexico (GOM). This is recognized in the document, which notes that while on-shore production from public lands increased from 109 million barrels in 2009, to 114 million barrels in 2010, that from the Outer Continental Shelf went from 446 million barrels to 600 million barrels. Yet with the problems that the industry has seen with the Deepwater Horizon disaster last year, the reduced production over that anticipated from the Thunder Horse platform and the slowed permitting and likely new drilling schedules it will be difficult to see how industry can maintain current production, let alone much increase it. However the Administration is currently developing a longer-term plan:
the Administration is developing a 5-year (2012-2017) comprehensive plan for offshore oil and gas exploration and production, which will ensure that areas with active leases, including the Gulf of Mexico and Alaska, are considered for further leasing and development. The strategy also calls for conducting studies to assess the potential oil and gas resources available in the Mid - and South Atlantic.
Sadly plans, in and of themselves, will not produce any additional oil. The President spoke of the importance of imports from Mexico and Canada. Unfortunately Mexican production continues to decline, and imports from there were down to 1.2 mbd in February. It would be helpful if resolutions in the American House of Representatives led to increased Canadian production but with Canada now heading for new elections that isn’t likely to happen in the short-term either. And Exxon Mobil, inter alia, has already responded to explain why there may a considerable gap between the President’s implication of vast untapped leases waiting to be made productive if industry would only get busy, and reality.

The Blueprint rightly draws attention to the “vast reserves of natural gas” and the potential that they hold, but much of the rhetoric in the blueprint is directed at the investigation of hydrofracking and ensuring that it is carried out “in a safe and responsible manner,” as though the thousands of wells that have used this technique already were not. The meetings and studies proposed will not, in reality, contribute much in the way of new gas to the nations need. Production is likely to be more tied to the price that can be obtained for the gas delivered to a pipeline, in contrast with the price for LNG delivered to the same pipeline from foreign sources. And at the moment, with the world having a surplus of NG, and more countries seeking to get onto this bandwagon, it is unlikely that the shale gas operators will be able to recover the full price of production in the next year or so from sufficient new production to have that much impact.

And so we turn toward the plan for the USA to lead the world towards safer and more secure energy supplies. Part of that answer seems to be based on persuading the BRICS nations not to grow their demand for oil so fast. It is also encouraging them, where possible, to switch from burning oil for power generation to using natural gas. (As though the price differential in itself won’t be a more powerful argument). The Administration is however encouraging the collection and use of methane from agriculture, landfills and wastewater, as well as the more usual sources.

The Blueprint notes that the United States would work as an energy partner to safely develop the oil and gas reserves in the pre-salt prospects off Brazil, though I suspect that US participation is not going to change the current progress and production in those parts. Further, in working to make bio-energy sustainable:
The Global Bioenergy Partnership will soon be launching a capacity building initiative in West Africa to encourage the transition away from the traditional use of biomass through effective forest management, to improve agricultural production, and to help countries capture the benefits that sustainable modern bioenergy can provide for energy access and food security.
While more energy for Africa is certainly needed, I am not, myself, convinced that those nations will not, instead, get the majority of their new energy from the indigenous coal supplies that seem to be plentiful. (In light of current developments in Japan, the encouragement of nuclear power was more euphemistic than usual). But while the blueprint also talks of transitioning fleets to natural gas and hybrid-diesel – though the EU is less than enthused about diesel emissions – none of this is going to have much impact other than to hope that by persuading other folk to buy less, the price won’t be as high as it otherwise might be.

b) To Provide Consumers with Choices to Reduce Costs and Save Energy
So how is the consumer to be helped? Well both by making more efficient vehicles available, and by producing more biofuel production. The goal remains one of getting a million “advanced technology” vehicles by 2015 and of increasing biofuel production. There is a slight snag, hidden in the report, however.
In 2009, the U.S. had only two factories manufacturing advanced vehicle batteries that power advanced technology vehicles and produced less than two percent of the world’s advanced batteries. But over the next few years, the United States will be able to produce enough batteries and components to support 500,000 plug-in and hybrid vehicles and will have the capacity to produce 40 percent of the world’s advanced batteries (2015). In part because of these strategic Recovery Act investments, battery costs are expected to drop by half (2009-2013).
The rest of the world had better not want too many of those advanced vehicles, since there will only be a few more than a million batteries produced by 2015. The Federal Government will begin buying plug-in hybrids this year, although only a hundred at first, and this will be one place where growth may reduce oil demand, although it is questionable whether the number on the road will be sufficient to perceptibly change the gasoline demand from the nation in the next nine years. But while the volume of fluid might increase, by increasing the percentage of ethanol in the mix to 15% (now allowed) some reduction in oil volumes might be achieved. However the source of the additional volumes is left as:
DOE and USDA have provided grants, loans and loan guarantees to spur American ingenuity for the next generation of biofuels.
Unfortunately as the experience with Range Fuels has shown, such hopes are no promise of success, and without an almost immediate success it is difficult to get to sufficient production by 2020 to have any significant impact on American supply. There is little evidence that the cellulosic ethanol process can be brought up to the needed level by then, and there are few alternative processes that can promise a significant contribution. Yet the government remains optimistic that
the Administration has set a goal of breaking ground on at lest four commercial-scale cellulosic or advanced bio-refineries over the next two years. In addition, the President has challenged his Secretaries of Agriculture, Energy and the Navy to investigate how they can work together to speed the development of “drop-in” biofuel substitutes for diesel and jet fuel.
One of the more promising sources is camelina but it has a limited growing range in the United States, and is not proving popular on the US farm, though it is now to be test grown by Airbus in Romania. (I am precluded from talking about algae).

In addition there are optimistic discussions about changing the way in which people travel, and the introduction of high-speed rail. Unfortunately the willingness of Republican Governors to shoot these plans down, no matter how well intentioned, makes much progress in this area unlikely.

The Blueprint goes on to talk about improving energy efficiency in buildings and through use of renewable energy. However the major fuel sources for electric power are coal and natural gas, so that changes here will likely have little impact on the amount of oil imported. Thus, even though the projections for the near term look promising for renewables, their overall effects on American consumption is likely to have little significance for some considerable time.


c) Innovating Our Way to a Clean Energy Future
The President proposes to eliminate fossil fuel subsidies, taking that money to help fund more research into developing clean energy innovation. Beyond that the clean energy future is concerned more with finding ways of saving energy, and particularly electrical energy than it is on reducing the need by the United States to import oil.

Given that we are likely to need as much fossil fuel as we can get over the next three or four years, as conventional supply tightens under the problems of MENA popular protest and government change, I continue to believe that the Administration, at the top, does not understand the problem.

We do not have the decades that Secretary Chu’s favored bugs will need to produce enough jet fuel at scale to meet a significant part of demand. I agree that we have to press forward to find long-term solutions to the coming shortages of oil, and then natural gas – but ignoring the reality of the precariousness of the current balance between supply and demand is becoming increasingly worrisome.

In short the Blueprint has really shown nothing new, or much learned from the experiences of the past year, which is sad, given that time is starting to run out rather fast.

Read more!

Tuesday, February 1, 2011

The ExxonMobil view of the future

A couple of weeks ago I reviewed the BP Energy Outlook to 2030, and noted, in passing, that there were a couple of assumptions that might be quite optimistic – though I did not get into the details of the forecast. ExxonMobil (EM) has also put out a forecast, and it could be informative to see what, comparatively, they anticipate for this same future period. I am going to try and follow the same steps that I did with the review of the BP plan, to make comparisons easier.

The first difference is in world population, which BP anticipates will grow by 1.4 billion by 2030, EM is a little more conservative, with growth closer to 1 billion for a total of 7.9 billion. (Current population is 6.9 billion. EM relies on the UN and the World Bank for its figure). In itself this changes the overall level of demand, since both expect that per capita consumption of energy will also rise. There is one oddity that I might initially mention (and yes I know the dollar base differs) but contrast these two graphs – the left is from BP and the right from EM.


While I did not get the scales exactly the same, you can see, to a first estimate, that the global GDP in 2030 for EM is roughly the same size as the Non-OECD GDP estimated by BP. (A quick check on Google says that the current GDP is at $58 trillion). This difference continues in the assumptions of the areas of greatest growth. While, as can be seen above, BP sees OECD growth as virtually flat and all the increment being from non-OECD, EM has OECD growing at 2% and non-OECD at 5%. But that will still only put the non-OECD at 40% of the global economy by 2030, which is the inverse of the BP projection.

Change in GDP does not however easily translate into changes in energy consumption, particularly given the much lower relative energy consumption of the non-OECD countries. EM sees energy use in the OECD staying relatively flat, the gain in GDP is accomplished with an increase in the efficiency of energy use. (Which agrees with the BP position). Thus by 2030 it is the non-OECD countries that will increase demand to the point that they will have an energy demand that is 75% higher than that of the OECD.

With that as background, where and how much energy does EM anticipate will be used in this future. To make the two forecasts simpler to follow I have had to convert since while BP works in millions of barrels of oil equivalent (mboe) throughout, EM uses Quadrillion Btu’s or Quads in places. (A barrel of oil is equivalent to 5.8 million Btu, or conversely 1 Quad is equivalent to 172 million boe). And then to make life a little more fun BP has used tons of oil equivalent, making the Quad equivalent to 24 million tons of oil equivalent. (Using 7.16 barrels to the ton to simplify future arithmetic). Having done that, and with a little Photoshop scaling, I can compare the two energy projections.

Comparison of BP and EM energy futures, (The vertical scale is in billions of tons of oil equivalent. )

One of the immediately obvious items is that the amount of coal use that EM is projecting is considerably less than that projected by BP, there is a little more use of oil, and about the same amount of NG.

BP had generated a graph that predicted that by 2030 oil’s share of the global market would continue to fall, while after an initial increase in percentage use, coal would fall on a parallel path with oil, so that, by 2030, both would share equally with natural gas at about 26% of the global energy market each. The remainder of the market, at about 7% each would be equally divided between Hydro, Nuclear and Renewables. Of these renewables (which include biofuels and biomass) would have the steepest increase.

Sources of Future Energy Supply (BP Energy Outlook)

EM on the other hand see the energy supply in 2030 being divided so that oil retains 32% of the overall; natural gas has risen to 26%, and coal has fallen to 21% of the overall. The non-fossil sources are divided 8% for nuclear, 3% for hydro and 11% for the renewables that include biofuels and waste (which is not separately identified by BP).

EM estimate of how fuel use will change over the next 20 years

The above plot shows percentage growth, rather than market share, so that while wind, solar and biofuel energy production grows strongly, by 2030 it is still providing only 3% of global energy.

Looking at the individual fossil fuels in turn – EM sees that India will provide the largest new market for coal, while Chinese demand will soon peak, and demand in the more industrialized nations declines in the face of increased concerns over carbon dioxide emissions.

Increased production from the Canadian oil sands will team with the growth of biofuels in a combined 5% contribution to global liquid fuels according to EM (this is a little less than that projected by BP, who has 2 mbd for oil sand and just over 4 mbd in biofuel growth). And, by 2030 EM expects that NGL supply will amount to about 10% of total hydrocarbon liquids, totaling around 11 mbd. This is quite a bit more than BP project (at about 4 mbd – though that is assigned only to the OPEC nations, and there could be more from other sources though that is not mentioned in the BP document).


EM’s answer to where all the additional oil is going to come from is Deepwater. It projects that by 2030 deepwater production will be at over 14 mbd. The more than doubling of production is anticipated to be almost across the globe, whether Africa, Europe, Latin America or North America.


Because of this emphasis on deepwater, and in order to provide reassurance against the likelihood of another major spill, EM discuss, within their document, the development of the Marine Well Containment System, which is designed to ensure against what happened this past year.

Natural Gas is the seen as the major growth fuel of the next 20 years, and EM anticipate that use of NG will rise to make it the second most popular fuel (bypassing coal but not oil) by 2030. Interestingly they see the supply of NG over the 2005 volumes as coming almost equally from conventional wells, from unconventional (gas shale) wells in the US and Canada, and from imports. (Though it doesn’t say where from). Unconventional supply is anticipated to grow five-fold.


In the end EM seems to be expecting more from natural gas than other fuels over the next twenty years, more so than BP. This seems to be a reasonable assumption, as I said when reviewing the BP projections, providing only that that there is that one new development (cheaper production and longer well life) that is needed for more viable shale gas production. This is particularly true when one looks at the primary sources of electric power generation, in the three main sectors of the world.


EM sees the United States and Europe being much more aggressive in reducing coal use, and expects a greater role to be played by nuclear power plants than BP.

In summary ExxonMobil has a much more positive view of the long term sustainability of oil as a fuel, with a much greater contribution from the deepwater than BP had projected. It sees the role of coal fading from the future energy field, while natural gas will continue to develop and gain market share.

Read more!

Wednesday, April 28, 2010

British future energy supply - some problems with the numbers


As I travel around the UK there are the odd sign of the coming General Election. Relative to the activities that one would see in the USA they are, however, indeed relatively muted, and the signs, even on the motorway, are no larger or long lasting than those that have, on occasion, decorated our front yard. But with the slurring remark about a voter by the current Prime Minister the entire MSM has become convulsed about the story. Having, in my distant youth, worn a live mike to the bathroom, I am entirely sympathetic with the poor politician, though he should be experienced enough to know better. But it does drive items, of what are really more important news, much deeper into the papers.

Even without that issue taking the space it now does, I had to meander back to page 40 to catch what should be, in reality, a much greater concern for the British public.
Britain could be forced to close 14 power stations if a proposed European directive becomes law, a move that would drastically cut power supplies and endanger energy security, the Confederation of British Industry has warned.
The timeframe is 2016, and the issue is to do with compliance with EU regulations on power station emissions, or closure. Those arguing for compliance with the anticipated regulation see no real problem, and expect the demand can be made up with supply from renewable sources. As a Greenpeace spokesman noted:
"Britain is gearing up for a six-fold increase in the amount of energy we get from clean sources in the next decade, so these CBI scare stories show that the French and German energy monopolies they represent are now seriously worried that the clean tech industry will effectively squeeze out dirty coal power in this country."
And here, of course is the rub. The CBI would have you believe that a quarter of the UK's electric generating capacity is threatened. While GreenPeace argues that increasing renewables negates the concern.


For a little check on these statements the UK Department of Energy and Climate Change (DECC) has issued projections for the generation mix that the UK can anticipate in coming years. Clicking through on Table D, the generation mix table, one finds:

Source Dept of Energy and Climate Change)

There are a couple of things that become obvious from this table. Firstly the current UK Government recognize and buy into the need to reduce overall current traditional power sources. There is the recognized roughly 25% reduction on coal power use (note that by 2017 it is too early to expect any impact from CCS). However it is also remarkable that the supply of natural gas to be used in power stations is anticipated to rise 42% by 2017, something which neither of these two debaters have brough to public attention. At the same time nuclear power generation is anticipated to drop by almost 50%, while renewables only increase by 46%, which is a whole lot less than the 600% that Greenpeace is stating.

The primary question becomes one as to whether or not the UK will be able to get enough natural gas to meet its demands and keep the pressure off renewables. At present there is a lot of complacency, given in part by agreements with Qatar over the supply of LNG. The agreement with Qatar will supply, though the Milford Haven terminal, some 20% of the UK need , which will then be re-gasified and fed into the national grid. But 20% of the national need still requires that the other 80% come from somewhere, since the volume will not even cover the rise in demand to meet the DECC projections.

One of the things I did today was to visit the Lancaster Maritime Museum (in the UK), and they have an exhibition on the gas that comes to the UK from off the coast here. Because of that supply natural gas has been the greatest supplier of energy to the county. In 2006, the latest year with figures available, the supply was for 13,669 GWh of natural gas, 12,545 GWh of petroleum products, 585 GWh of coal and 423 GWh of renewables. (no nuclear). Since 2006 the supply had grown relative to UK demand, now supplying 10% of the national need at a level that is expected to be sustainable for 40 years. What I found interesting was that this NG was coal based, rather than the conventional petroleum (i.e. algae) based origin of the majority of the natural gas in the North Sea. But that is still only 10%.

Now Rune, Euan not to mention Jerome and Rembrandt have posted regularly on the problems that Europe is going to face on natural gas supply. The doubts about the Russian ability to get Yamal and Shtokman into production on time continue. At present Shtokman is being pushed further back while Yamal is given greater priority. The Stern Report quoted the 2007 Gazprom report in seeing a steady increase in Russian supply.

Anticipated future Russian natural gas production.

But notice where the majority of the gas will have to come from after this year - Yamal. And is the investment being made to produce that gas, and won’t an increasing percentage be consumed by the growing Russian economy? There have been some questions over this past year as to whether the necessary investment has been made. And if not, given the quantities of Turkmen gas, and that of other adjacent states that may be heading to China rather than Europe, then additional supplies might not be available in a timely manner.

Which brings us back to the overall question. If there is not enough importable supply of natural gas to offset the decline in nuclear and coal –fired electric power production, then the increase in renewable energy sources that the British Government (as opposed to Greenpeace) anticipate will not be sufficient to meet the demand for power, within the likely term (if normal) of the next Parliament.

There is a widespread pessimistic anticipation in the UK, that the first thing that any new Government, regardless of party, will have to do is to carry out a drastic budget cut. With those cuts, and the lack of investment that they will also likely mandate, then that little page 40 story might get enough legs to move to page 1 before too awful long.

Oh, and why am I in Lancaster – well here is a 53-year old photo that might help explain it. And that may feed into another post, but we’ll just have to see about that.

Smithy House, St. John's Town of Dalry, 1956/7?

It has to do with the school uniform of the kid on the right.

Read more!

Wednesday, March 4, 2009

Jobs in a changing economy

The debate over the mixture of sources that will make up the supply portfolio from which America will draw its energy in the next twenty years is just beginning. Until now there has been a general acceptance of the need to find less polluting technologies. When this is combined with its flexibility, this has meant that for the past few years new fuel-fired power stations have focused on the use of natural gas. At the same time the growth of the renewable energy component, while small, has continued, most particularly for wind. Wind and gas-fired power sources tend, to a degree, to compliment one another, given that wind has to have a back-up that is flexible, for when it is not producing and this can be achieved relatively simply with a gas turbine. At the same time, the increasing cost of natural gas, means that the savings from the wind turbines will popularize their use.

In a world where energy demand has continued to grow, this meant that there was, given their initial small size and growth capacity, a continuing demand for both new gas power plants and for new wind farms and solar power plants. However we are now at a point of transition, and the new Administration has a different concept of the way to the future. Part of this new message is predicated on the need to conserve, and to use more efficient appliances. It has come out of a successful application in California, where demand has been kept down, by such changes. It is a message that has been adopted by many utilities that do not have to build new facilities if their growing customer base, instead of growing demand improves the efficiency of power usage, and can hold their overall demand steady. Because of the way that the utilities must sell this program, and the incentives that they provide for customers to conserve or change to more efficient appliances, there is a cost for this power. A local utility suggested that it was around $0.04 per kWh, considerably less than the cost to build new generating plant. Thus, at present, the movement to increase conservation and efficiency will be hailed as a benefit by both parties.

Unfortunately, if the power consumption level is held steady, then with no growth, the need can be met with existing power generation systems (recognizing there will still remain some small market for replacement). This means that the demand for new facilities and new power generation systems is diminished. This is particularly likely to be true in a time of recession. So if there is to be no business through growth in the economy and the power demand therefore, then if we are to sustain the demand for, and integration of, renewable sources into the grid we need to start replacing some of the older power plants, with different sources of energy.

Now this is where we bump into another problem. Much is made of the potential jobs that would be created if renewable energy systems were installed. A wind farm here, a solar farm there, and the jobs mount up. But in relative terms, once these farms are in place, the number of folk required to maintain and repair them will be small. Contrast that with say the natural gas industry where, as I tried to show yesterday, if you are not continuously drilling for gas these days, then the supply will drop. Thus we need a continuous supply of drill crews, someone to make and supply the steel for the drill strings, someone to mine the sand and treat it, and to make and mix the polymers for the hydro-frac, and then the folk in the storage facility etc etc.

It gets even more labor intensive if one goes into coal mining. There are miners, those that run the cleaning plants where the waste rock is removed, those that haul the coal around (pipelines are not nearly that popular) as well as those that make and maintain the machines (which have a high wear rate and rate of attrition). The mines need tires for the trucks and oil for the machines, and soak up a lot of electric power along the way. A study done on potential economic loss has been quite blunt on what some of these impacts might be. Rose and Wei found that on current rates of supply the coal industry would contribute roughly $1 trillion in the decade leading up to 2015, with some $362 billion in household income and some 6.8 related jobs. The then looked at both a 33% and a 66% replacement of the energy the coal produced with renewable or alternate power. At the 33% replacement rate they saw a drop in gross economic output of $166 billion, $64 billion drop in household income per year, and a loss of 1.2 million jobs. (These losses more than doubled with greater reduction in coal use).

Now there is a train of thought that rejoices in the change, and the simplicity of the new technology. But, on the other hand, it is going to put a fair number of people out of work. At a time when job creation is a vital need if we are to work our way out of this global recession, we may well see a drop in employment if the transition is enforced too dramatically.

I was born and raised in the North of England where the mining industry was the major employer. I would take the first bus of the morning to the mine, passing as I did in the half-hour journey, over a dozen mines. The mines were still in the transition from hand-won mining (see the Sunday Tech Talks) to machine-won coal. Thus each mine would employ around a thousand people. As North Sea oil displaced coal in the UK these mines closed. There was not nearly enough work to go around, and while the social compact in the UK meant that no-one starved, and most had housing, unemployment rates stayed very high for decades. The pubs, where miners congregated in the evenings suffered badly, as did all the other supports that a community grows, the stores, the sports, the entertainment, all diminished.

But as wages decline, and jobs, so other aspects of a society also diminish. Crime and violence often increase, and community health declines. As the debate over future energy policy increases in intensity the voices of those that will be thrown out of work by the changes, a community until now relatively silent, will begin to be heard. And then perhaps the debate over relative costs and benefits will be joined with more vigor, and fact from each side. This may, in the end, make the passage of some legislation more difficult than it now appears, it will likely depend on how deeply the recession bites, and how long before it starts to lift.

Read more!